We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Triple lock increase for April 2027 is 3.9% (probably)





Following earnings data published today we know that subject to a possible minor adjustment in October (see below) the triple lock state pension increase for April 2027 is likely to be based on the average earnings increase figure of 3.9%. This would mean the headline new state pension figure would increase from the current £241.30 per week to £250.70 per week in April 2027 (a £9.40 per week increase).
The triple lock increase is based on the highest of average earnings increases, CPI price inflation and 2.5%. The triple lock is a manifesto commitment rather than a legislated increase and it is usually announced in the budget (28th October 2026).
As CPI inflation is not predicted to increase above 3.9% and the minimum 2.5% won’t bite the triple lock is likely to be based on this earnings figure.
This would mean that the taxable full new state pension, which is usually calculated as 51 weeks at the new rate and 1 week at the old rate would be £13,027 for 2027/2028 which is £457 above the personal allowance for 2027/2028 of £12,570.
The CPI and earnings increase elements are as follows.
Earnings increase
The earnings percentage used for the earnings element of the triple lock calculation has been established through custom to be the July 2026 seasonally adjusted total pay including bonuses figure published today (15th September) of 3.9%. The July 2026 figure is the average of the year on year increase in earnings for the 3 months of May, June and July.
This July 2026 earnings figure can be subject to a small revision when further earnings data is published on 20th October. This publication occurs just before the budget takes place, which is when the triple lock increase is usually announced.
For example in 2024 the corresponding July 2024 earnings figure of 4% published in September was revised to 4.1% in October and the triple lock increase in April 2025 announced in the 30th October 2024 budget was based on this 4.1% revised figure.
And in 2025 the corresponding July 2025 earnings figure of 4.7% published in September was revised to 4.8% in October (there was no further revision in November) and the triple lock increase in April 2026 announced in the budget on 26th November 2025 was based on this 4.8% revised figure.
CPI Price inflation
The July 2026 CPI figure was 2.9%. August's figure is out tomorrow (16th September). And it is September's figure (published on 21st October) that is traditionally used for the price inflation element of the triple lock. We need to wait until 21st October to get final confirmation that the relevant CPI won’t increase above 4.1%.
Comments
-
Essentially then it's not the full increase promised if tax has to be paid on it. The whole point of this triple lock was for state pension to keep up with inflation
2 -
This is how the taxable full new state pension has compared to the personal allowance since its introduction in 2016/2017
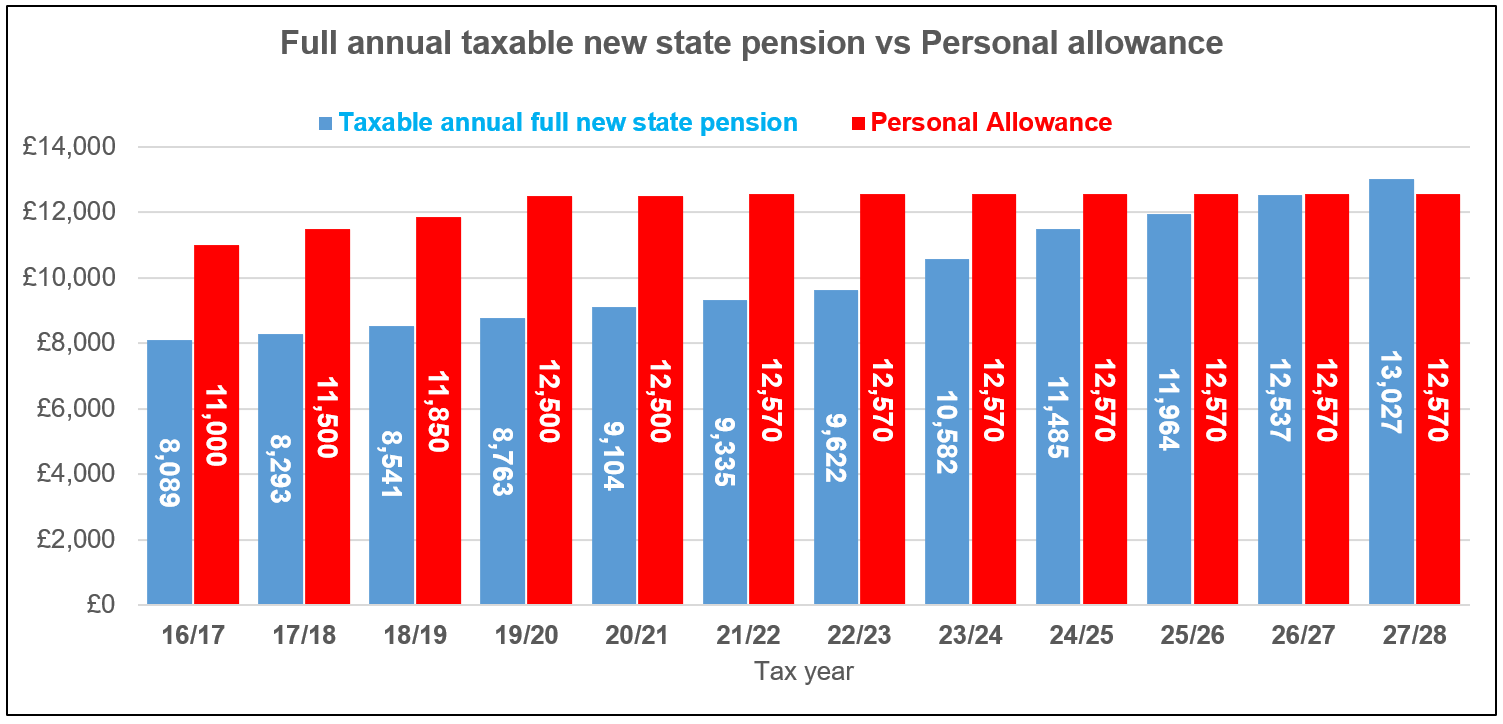
By my calculations the full new state pension will have increased by 1.1% per annum above CPI inflation since its introduction in 2016/2017 to 2027/2028, as only increases in 2018, 2022 and 2023 were based on CPI.
But when you take into account the extra tax in real terms through freezing of the personal allowance, the new state pension (net of the tax effect which can be thought of as negative state income) has for a basic rate taxpayer increased by only 0.4%pa above CPI price inflation rather than 1.1% since 2016/2017.
I came, I saw, I melted7 -
This is what the government said last year - no further details yet:
State Pension and Simple Assessment – The government will ease the administrative burden for pensioners whose sole income is the basic or new State Pension without any increments so that they do not have to pay small amounts of tax via Simple Assessment from 2027-28 if the new or basic State Pension exceeds the Personal Allowance from that point. The government is exploring the best way to achieve this and will set out more detail next year.
1 -
No, the point of the trippe lock was to deal with the erosion of the SP compared to earnings.
If it was just to keep it up with inflation then there's no need for the triple lock and just indexing it to inflation would achieve that objective
9 -
Surely the easiest way to ease the administrative burden is to make the personal allowance equal the flat rate pension amount? They could do that for everybody or just for people of pension age but the latter would risk the wrath of everybody else but the pensioners.
1 -
Of course Rachel Reeves expanded on what was said in the budget by confirming to Martin Lewis that those whose only income is the State Pension will not pay any Income Tax on it during this Parliament
An official HM Treasury spokesperson also supposedly said to journalists around 25th/26th August 2026 in relation to whether the Burnham government would follow through with what Rachel Reeves said "Pensioners whose only income is the full new or basic state pension without any increments will not pay income tax and we are committed to that over this Parliament."
However basic rate pensioners not affected by this concession (because they have other income or increments) can be argued not to be receiving the full earnings increase after allowing for income tax. That is unless something more far-reaching is announced in the budget.
Keeping this factual.
I came, I saw, I melted3 -
In addition to the 2.5% base, there is a tendancy for SP to increase by more than inflation over the long term. If inflation rises one year and average wages increase by the same amount the following year SP gets a double increase.
0 -
I fear that many people will be in for a shock next year, in the belief that 'those on just the State pension won't pay any tax' because they have misunderstood the rider 'without any increments'.
In round figures, someone on just the new single tier pension of £13K with not a penny from any other taxable income won't pay tax. But someone on the old basic State pension of £10K plus £3K of SERPS/SP2/inherited spousal benefits etc will receive a simple assessment tax bill of over £80.
6 -
I look forward to my facebook channel being full of people complaining that 20% of their entire pension is going to be taken away in tax.
6 -
My money's on them reintroducing a pensioner's tax allowance, withdrawn at a modest income level, like a couple of decades ago.
There's too many anomalies, cliff edges and potential "it's not fair" stories in the media if they simply say those on the basic/new state state pension with no increments won't pay tax.
1









Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.7K Mortgages, Homes & Bills
- 179K Life & Family
- 263.5K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards