Ready, steady… save!
You don’t need a chart to join in. Here are 2 ways to record your savings:
1. Cross it off
Pop a chart into your first post. Saved an amount? Cross it out! Read more »
£0.01 £0.02 £0.03
2. Write it down
Skip the chart and add updates to your first post. Read more »
“Another +£3 saved today. Go me!”
Use +£ before each new saving so it counts towards your total.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
The Top Regular Savers Discussion Thread
Comments
-
Bob - Progressive BS funding question. I suspect a £200 faster payment would not earn interest until the next banking day ie. tomorrow, but if you have £200 sitting in your current account earning zilch then it makes no difference so fund it today. I`m not sure if a debit card payment would be any quicker. As the interest payment is variable why would you wait until the end of the month? Get your money earning 7% as soon as possible.
1 -
First Direct
This 180 day rule may possibly be the case if the inactive savings account has a zero balance (I wouldn't know as I always leave £1 in open but inactive accounts). But I and my other half have left our FD savings accounts (originally matured regular savers) inactive between annual regular saver maturities for many many years and never had this problem. But to be on the safe side I just checked - we've just successfully made transfers both into and out of our inactive savings accounts although they've been inactive since last January .
EDIT: See https://www.firstdirect.com/help/useful-information/dormant-accounts/
A dormant or inactive account is one that hasn't been used for an extended amount of time (typically 2 years). We may prevent unauthorised transactions being made on inactive accounts by:
- freezing inactive accounts with a credit balance
- closing inactive accounts with a £0 balance
- closing eligible* inactive accounts with a credit balance of £10 or less and donating the balance to our charity partner. You can still claim your money back at any time.
2 -
Is this First Direct?
It must be a new policy if so. I've held a savings account for many years and the only activity is has is receiving the RS maturity once a year and me moving that money elsewhere. The rest of the time it sits there empty. Their policy states "typically 2 years" as the period an account is unused for it to be considered dormant. They normally warn you well before they do anything.
1 -
You'd consider it a close escape if you knew the area 🤔
2 -
Yes the SA has had a zero balance for the past year. I have a bonus SA with FD that has just over £2 in for several years, I don't recall doing any transactions with it for over a year and that has not had the ability to move money out removed. I think I'll put 1p in the SA to receive RS maturities and see how that goes this year. Also setting up a reminder for me to do some movement on the account after say 170 days, would / should keep it alive.
1 -
Yes FD and I think I did get a dormancy warning by email, which I didn't act on.
For some reason unknown to me FD seem to always take a hard line with me or make things difficult. And I've been a customer for over 20 years, just not a profitable one for FD.1 -
First Direct - inactive account
I also received an e-mail referring to my "Savings Account" … see below … the last two transactions were a transfer out of my maturity proceeds on 08 March 26 and transfer out of £0.12 on 06 April, the balance has been zero since then.
Interesting the date of the e-mail is 07 October, exactly 6 months later and it states "… we might need to freeze your account if it hasn't been used for 24 months" however I intend to not touch it until I transfer out my next maturity proceeds on 09 March 27, so I've ignored it too.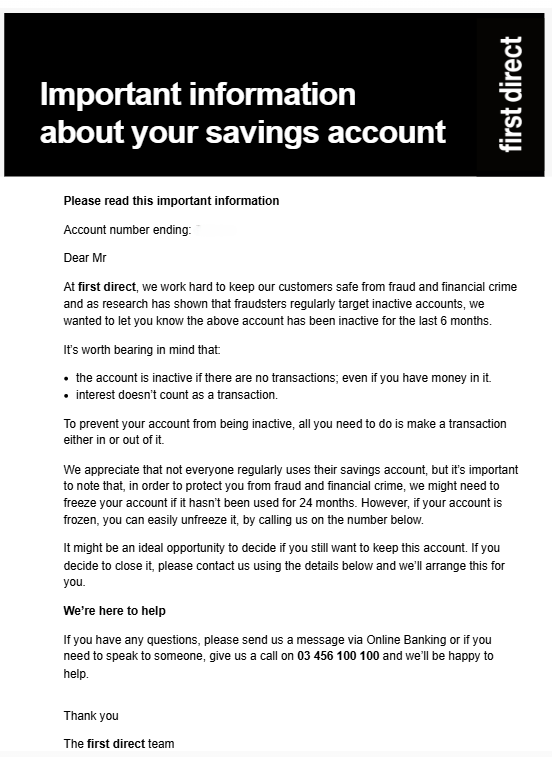 4
-
Mr Over62's Coop regular saver matured recently and he wanted to open a new one. The app redirects you to the website to do this but despite this, the application needs all details to be entered manually as nothing is prepopulated. The form was sent and a reply received that the Coop would consider it. Some time later, a link was received to another form asking for basic details again, including date of birth. A calendar was provided and the only way to enter the correct date was to click back a month at a time from October 2026 until the right month was reached. He is 73. 900 clicks? Life's too short. I messaged Customer Services to see if there was an alternative and they replied that the account was now open. So the form had not been necessary anyway.
4 -
Thanks, so just a warning at 6 months and no action until 24 months. That is not a problem for anyone who takes out a RS every year.
@Born2Save_3 you should consider complaining if your account has been active within the last 24 months and they froze it prematurely. Especially if you received this warning saying 24 months.
1 -
You/Mr Over62 should have been able to click on the year section of the calendar, where you will get a list of years, which you scroll until you get to correct year, click the correct year then click through the month's and click on the date required.
I find it still a pain and would prefer a box I typed in my date of birth, so much easier as quicker.
Fashion on a ration 2025 0/66 coupons spent
79.5 coupons rolled over 4/75.5 coupons spent - using for secondhand purchases
One income, home educating family2










Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.9K Banking & Borrowing
- 255K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.4K Work, Benefits & Business
- 606.1K Mortgages, Homes & Bills
- 179K Life & Family
- 263.9K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards