Ready, steady… save!
You don’t need a chart to join in. Here are 2 ways to record your savings:
1. Cross it off
Pop a chart into your first post. Saved an amount? Cross it out! Read more »
£0.01 £0.02 £0.03
2. Write it down
Skip the chart and add updates to your first post. Read more »
“Another +£3 saved today. Go me!”
Use +£ before each new saving so it counts towards your total.
We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Lifetime ISAs guide
Comments
-
@eskbanker sorry I have to ask you again here. I've seen one of your answers in this thread about LISA providers allowing over 40s to open a new account to transfer in or not.I am opening an account with Dodl and yes it seems it has allowed me to do this (though the money is still on the way). It says I cannot use the account until the money is transferred in. I suppose once the transfer is in, I can add this year's LISA allowance in anytime before 6 Apr 2026, is this right?0
-
Yes, they can't allow it before the transfer is received as this is what will make the account legitimate for someone over 40. You'll have the option to add money as soon as the transfer history paperwork is processed.1
-
EQi are now allowing new customers and should be in the DIY section. Their LISA offering is particularly good for OEICs as they have no buying or selling fees and 0.2% p.a. custody fee, capped at £40 p.a.
https://eqi.co.uk/info/how-it-works/new-pricing
1 -
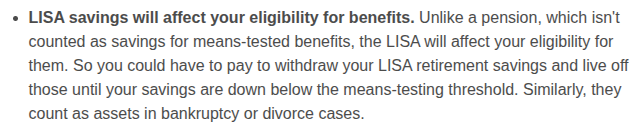
I don't understand why I haven't seen anything warning people against putting money into LISA's if there is a chance of them needing to go onto benefits. If this happens then you are forced to withdraw your money and then get the penalty due to the withdrawal charge. If only us and the financial adviser hadn't advised him to put money into a LISA it would have made quite a big difference to him.
Not once have I seen a warning about this on any of Martin's posts and think there will be plenty young people who could do with this flagging more explicitly.
0 -
It's not really a LISA issue as such, but one of the rules for means-tested benefits, which do take into account any savings and other assets, regardless of penalties needed to access them - these could include other types of accounts beyond LISA, such as fixed term products.
Nobody is forced to withdraw their LISA contents unless they don't have anything else to live on, and I don't think anyone would suggest committing to a LISA without some sort of readily-accessible emergency fund, as the withdrawal penalties are well publicised - are you saying that a financial adviser recommended otherwise?
0 -
The discussion seems to be quite dead here but still might have more luck then in more general forums so i will copy what i posted in different place, it is relevant to LISA and MAYBE someone did this before:
"I've asked this question a few years ago and the responses were mixed (if it is possible) but as I am approaching this problem now I wonder if anyone actually did it and can share details of the solicitor who did this sucesfully.
The situation is:
I bought a house in 2020, I am the only person on the mortgage/deeds etc, I live in the house with my wife and daughter.House worth about £340k now.
Wife has LISA account opened in 2019 with about £35k now, she never owned any house anywhere hence as far as we know she is a "first time buyer".
She want to be added to the mortgage now, potentially during remortgage next year or after remortgage (product transfer according to halifax) and want to use her LISA as a deposit.
As far as i know she can't just do it directly during remortgage but as i did research as long as she "buy in" into the house (transfer of equity) she should be allowed to use LISA without penalty as long as she fullfill all other conditions (FTB, house price < 450k, live in a house etc, mortgage involved). Apparently it's in the quote:
"GOV.UK's Conveyancers: Lifetime ISA technical guidance, an investor can use their LISA to purchase a property as a joint owner with someone who already owns it"
I know she might be liable for stamp duty but as i said house price 340k, mortgage 105k, deposit £35k (from lisa) hence i think she is below stamp duty threshold.
I know we need to use solicitor to do transfer of equity/deal with claiming lisa (from AJ bell), deal with land registry update but i am struggling with finding one who will be willing to do this.
Any help?
"
I got a quote from some company which i enquired if it is possible, they admitted "yes" quoting this sentence but the quote is about 2k (i don't even know if it's for the whole process or 2k for me and 2k for wife;) so I am quite reluctant to pull the trigger, I hoped it to be less then 1k, 2k seems like normal house purchase which we are not trying to do..
0 -
Although at least part of the underlying reason for the equity transfer is LISA-related, the core question is really about conveyancing costs and so might be better posted on this board:
0 -
You should be able to get a written quotation and breakdown from them and also get them to clarify whether it is for the whole process. I would be surprised if the £2k isn't for everything. They would still have the same duty to protect your wife's interests as if she were buying at arms length. Perhaps they have included the cost of searches etc, which you might wish to waive. A breakdown would show that.
Alternatively, she has the option of using the LISA towards retirement.
0











Categories
- All Categories
- 356K Banking & Borrowing
- 255K Reduce Debt & Boost Income
- 456.3K Spending & Discounts
- 248.5K Work, Benefits & Business
- 606.2K Mortgages, Homes & Bills
- 179.1K Life & Family
- 264K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards