We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
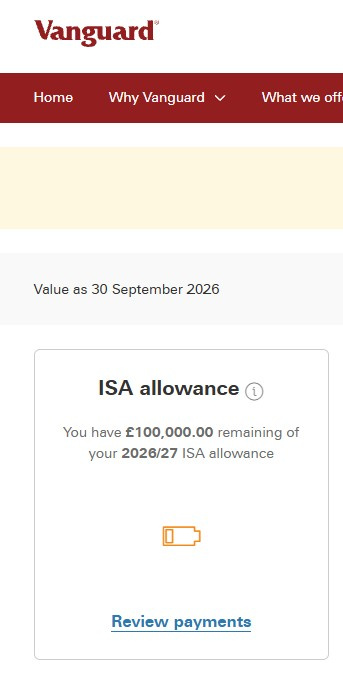
My ISA allowance is considerably larger than yows!





Comments
-
No large flexible withdrawals made (or APS allowance transferred in) I assume?
1 -
Yes, indeed you've spotted the issue. I did indeed make a £100k withdrawal. But a bit of a boo-boo on their part to suggest that as a remaining allowance, innit!
0 -
If you withdrew £100k from a flexible isa, that number could be correct.
2 -
They are right. Vanguard ISA is flexible, so your allowed to re contribute any withdrawals you make in the same tax year, so they are right at the moment if you took 100k out.
1 -
Yes they can put £100K back , but that £100K is not what is left of the OPs 26/27 allowance, which will be maximum £20K.
It is badly worded/inaccurate .
0 -
I've already used my £20k allowance for this year. The only thing that's correct, IMHO, is the empty battery symbol….
0 -
How else would you suggest they show how much they can replace in this year ?
As far as I know all flexible ISA report it like this, when you withdraw they increase your allowance by the same amount.
1 -
Not sure what the issue is here. A withdrawal increases the available ISA allowance to be utilised with that provider during this tax year. So, they are correct.
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.7 -
As others have said if it's a flexible ISA (which it looks like it is), then this is correct and nothing wrong with it at all.
If you have £100k in your ISA and after already contributing £20k in this tax year, then your remaining allowance would show £0.
But now that you've taken that £100k out, your remaining allowance will show £100k as that's how flexible ISAs work. So if you put the £100k back in then your remaining allowance would show £0 again.
If however you had not used your allowance this year yet before you had taken out £100k, then your remaining allowance would have showed £120k remaining.
Here's the MSE guide on how they work: What is a flexible cash ISA? How it works and whether you need one
2 -
This is exactly how things should work. The £100k withdrawal comes first from the £20k current year allowance you have used, so although you have subscribed to this ISA, you have your full 2026/27 allowance unused through the flexible withdrawal and can now use that wherever you like. The other £80k is a 2026/27 only allowance you can used exclusively with Vanguard.
0






Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.5K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards