We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Help DMP not DRO or IVA-should this be in benefits?
Comments
-
I was using my pip to pay them and my needs were suffering more and more as the debt got higher and higher, cost of living hasn’t helped , and I need carers and home help . I can start having them more now which will be a big help and make my life easier .., I hope if it gets sorted I didn’t know you could offset it.
2 -
Understandable but your priorities need to change. PIP is there to cover the additional help you need to live a decent standard of life, not to subsidise your creditors. Just leave it off altogether and make sure you spend it on things that make life easier.
If you've have not made a mistake, you've made nothing1 -
does anyone know the list of trigger amounts for the different expenses
0 -
Again, as said before, trigger amounts only apply to insolvency solutions, not debt management.
In debt management your budget is whatever you spend money on, as its no ones elses buisness but yours, least of all your creditors.
I’m a Forum Ambassador and I support the Forum Team on the Debt free wannabe, Credit file and ratings, and Bankruptcy and living with it boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com. All views are my own and not the official line of MoneySavingExpert.For free non-judgemental debt advice, contact either Stepchange, National Debtline, or CitizensAdviceBureaux.Link to SOA Calculator- https://www.stoozing.com/soa.php The "provit letter" is here-https://forums.moneysavingexpert.com/discussion/2607247/letter-when-you-know-nothing-about-about-the-debt-aka-prove-it-letter1 -
The trigger amounts for are relevant for debt management because a lender should not query a budget where the amounts are under the trigger figures.
1 -
I have a quote for adaptations as I am having a second surgery on my left thumb which is already partially amputated. Due to the damage and the accelerated arthritis in the cmc and mcp joint and shoulder arthritis and my spondylolithesis in my spine(whole spine is full of arthritis too) I am getting a quick release steering ball and an easy release handbrake adaptation done. I live out in the sticks and I need that car. I’ve been told I need to get a private assessment done too to cover the DVLA. This will all come out of my pip.
I am going to apply for a blue badge and the car bottom book value is £4500, with these adaptations which I need to keep my independence and the no service history for the 4 years I have had it and completely wrecked AC , had a quote 3 years ago for £700-800 at least to repair . What’s the chance if this DHMEF fails and me keeping hold of the car if I go down the route of DRO?0 -
so where do I find trigger amounts
0 -
Googling seems to suggest you need to be a registered Money Advisor to Access the up to date figures for insolvency
Think this is a Scottish website.
https://aib.gov.uk/systems/common-financial-tool
"You need to be authorised to access the CFS trigger figures on the Common Financial Tool.
BASYS users
Money advisers with BASYS access can log in to the CFT using their BASYS log in details.
Non-BASYS users
Money advisers without access to BASYS can register for access to the CFT by selecting register on the log in screen."
0 -
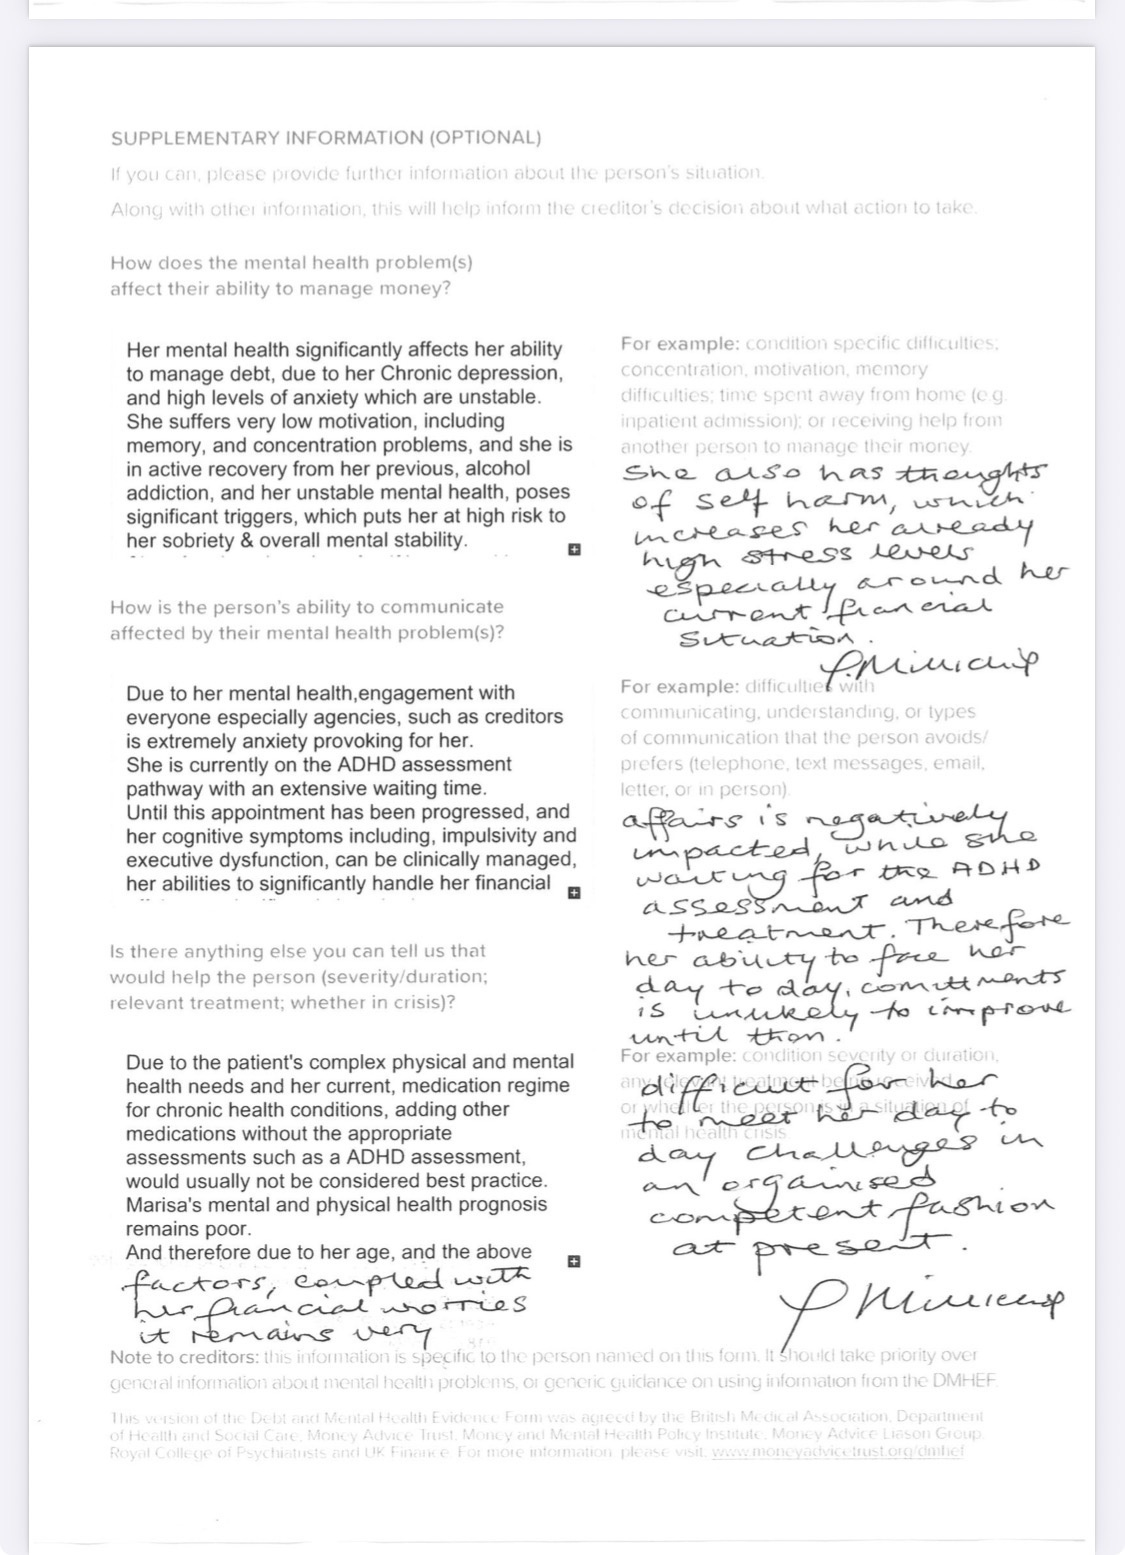
Back of DMHEF form he filled in
he changed some of it which I’m a little disappointed with. I suppose he had to be careful what he puts, long term he doesn’t really know and he can’t commit to that. Not sure now of my chances of write offs or what to do
0 -
Only debt advisors are privy to that information.
Honestly, I wouldn`t want you to overthink the budget thing, its fine if your doing it just for yourself, but the only info you should share with a creditor/debt collector is the figure that comes in, and the figure that goes out, as they have no right to see anything else, and even that information should be given at your discretion.
Personally I would never share financial information with any lender, debt collector, or debt purchasing company, as it gives them some kind of importance, and makes them think they can dictate to you how you spend your money, it passes the power to them, and that`s a situation I would not be comfortable with, I believe control should firmly rest with the debtor, and it is they that call the shots, not the other way around.
I’m a Forum Ambassador and I support the Forum Team on the Debt free wannabe, Credit file and ratings, and Bankruptcy and living with it boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com. All views are my own and not the official line of MoneySavingExpert.For free non-judgemental debt advice, contact either Stepchange, National Debtline, or CitizensAdviceBureaux.Link to SOA Calculator- https://www.stoozing.com/soa.php The "provit letter" is here-https://forums.moneysavingexpert.com/discussion/2607247/letter-when-you-know-nothing-about-about-the-debt-aka-prove-it-letter2











Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.6K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards