We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Early-retirement wannabe
Comments
-
Out of interest, do you have any plans to help keep your brain ticking over? Have you had a private project brewing for years that is finally going to get the green light?
Not as such. The plan is to enjoy normal UK life, as I haven't really had much of that to date, having spent so many years travelling. To date, I've spent a cumulative 4.79 years travelling outside of Europe, and that was all travel, not work. Adding in the time spent travelling around the UK and Europe and that will be well over 5 years on the roads, more than 10% of my entire life to date.
So I'm doing things I've enjoyed in the past, which includes starting to play the card game bridge again for the first time in many years, and will soon involve gym classes and swimming. More computer games and perhaps reading might play a role, and whatever may come along.
Once we get to autumn I'll turn my mind to travel again, having not been out of the UK after returning from 500 days travelling the Americas back in January 2024. A few of the trips/areas I'm particularly interested in going to are:
- An overland trip from Kuala Lumpur down through Sumatra to Denpasar, seeing Lombok and Komodo islands, then fly to Darwin and travel down to Alice Springs. Then fly to Sydney to meet old friends and see the area I used to live in back in 2000. That will be split into at least 2 separate legs, and tick off a lot of things I want to see, as well as completing a London to Sydney overland trip.
- A Roof of Africa overland trip, from Morocco to Egypt, if the route ever opens up again.
- A trip from Addis Ababa up to Alexandria, if Ethiopia and Sudan open up again. That would complete a London to Cairo overland trip via the eastern route.
- Mt Nyiragongo in eastern Congo, and a few other things in that area. I have only seen mountain gorillas in that area, none of the other attractions, but like the other places it hasn't been very safe for some years now.
- Various places in Turkey - I have visited a number of times, but there are so many great historical sites that I keep finding new areas I would like to see.
- A Silk Road route through the 'Stans, probably in a couple of separate legs
- China - a huge country with a lot of interesting things
- Indonesia and Phillipines - very big places I have barely seen.
Out of that lot, Turkey may well be the first, sometime next winter.
Easy enough to do a real terms model with frozen tax thresholds to see how large the impact might be at 58, 68, 78 etc. Assume say 3% pa inflation?
Mathematically, it is trivial, but it is just making guesses at politics rather than financial forecasting. The standard neutral long-term assumption is that all thresholds move in line with earnings, otherwise everyone eventually becomes an additional rate taxpayer. However, the long-term might be very long, and it is just guesswork what parties might do with thresholds, and when they will do it.
Triple Lock has much the same issue - it is all political guesswork.
Usually, the rate of inflation would be largely irrelevant, as everything would broadly increase either in line with it, or at a slightly different but highly correlated rate. But politics has made it a very real consideration, and nobody can sensibly forecast inflation more than about 2 years out.
So at best any modelling is just scenario and sensitivity analysis. The results of that would not affect my actions, so I don't bother with it other than thinking about how it might influence decisions.
The main decision that it will affect will be around when I commence DB benefits, as they are inflexible once in payment so are particularly vulnerable to political/policy change risk. What does seem clear is that it will be more likely that keeping DB and State Pension income as low as possible will be the lowest political risk, so having a lower income from these sources for longer will be preferable than choosing a higher income from them for a shorter period. Even if when I get to age 55, thresholds are broadly as they are now, it will still be preferable to take a lower pension for longer, as that will mean I have more in DC which is more flexible and hence easier to respond should thresholds get played with at any future date.
7 -
learning bridge is certainly exercising my brain, and I am doing some weight bearing strength classes and lots of Pilates to try and get the body in a fit state to enjoy the opportunities that retirement offers. It's all good stuff
I’m a Senior Forum Ambassador and I support the Forum Team on the Pensions, Annuities & Retirement Planning, Loans
& Credit Cards boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com.
All views are my own and not the official line of MoneySavingExpert.5 -
EDIT: Just reread your post and noticed that your wife is indeed doing this! Apologies …
Thanks and congratulations. I’ve benefitted from your posts here, and am in a similar situation. I need to do more analysis of our expenditure though
One question / suggestion, but can you put your wife’s redundancy into a DC pension? Inflation is such that by my calculations I’ve got big underspends in the annual allowance from previous years and if my place goes down the VES route* then that’s what I’d do to avoid tax.Or is it needed for bridging between now and 55?
Congrats and well done once again!
Si
*Sadly I don’t think VR will be an option1 -
Congratulations, it's really interesting to read your thought process about which pots of money to use at which stage, and why.
Do you now need to amend the thread title to "Early Retirement Dunnit"? 🤣
1 -
Sadly he cannot, as the original post was by @Marine_life not @hugheskevi
2 -
Oops … !!!
0 -
Our household is now fully early-retired! My wife received her August salary and redundancy payment on Friday. Slightly annoyingly, the redundancy payment isn't yet final, but the final amount will only be slightly different to what has been paid.
I have put all of my exit payment that would have attracted higher rate tax into a pension and sorted out the in-year income tax refund so my position is all finalised. I will wait until my wife's redundancy is finalised before I make her pension contribution.
Preparation and cash management
We are both aged 48. In recent months I have sold all of our stocks and shares ISAs. This was due to 3 reasons:
- These resources will be used to fund the period when we are aged between 48-54 so there is a very short investment horizon available
- The transfer ban that will apply from April 2027 from stocks and shares ISAs to cash ISAs
- The decent interest rates on cash available at the moment
The stocks and shares ISAs were then transferred to flexible cash ISAs, and from there I withdrew from the flexible cash ISAs to deposit funds in regular savings accounts and fixed rate accounts that will pay interest in the 2027/28 financial year, when neither of us will be taxpayers, as the interest rates on non-ISA cash were a bit higher than ISAs. I left enough in the easy access cash ISA for our needs until the 1 year fixed accounts mature.
This results in us receiving 4.86% interest across all of our cash holdings, none of which will be taxed. This amounts to £1,797 per month, which is a nice contribution, albeit declining over time and a decent chunk of it being offset by inflation.
We also have a preposterous amount of replaceable funds in our cash ISAs available - slightly over £400,000. We have a fully offset mortgage of just over £500,000 so at the end of the financial year I will briefly fully fund the cash ISAs and then return the money to the offset account at the start of financial year 2027/28 to preserve the replaceable funds balance. In due course the unwrapped savings will use up to £300,000 of the replaceable funds.
I plan to keep large amounts of flexible deposit headroom until we reach 55 and can access our personal pensions, at which time I will move the tax-free lump sum and amounts up to higher rate tax for both of us from the pension into ISAs.
Current financial position
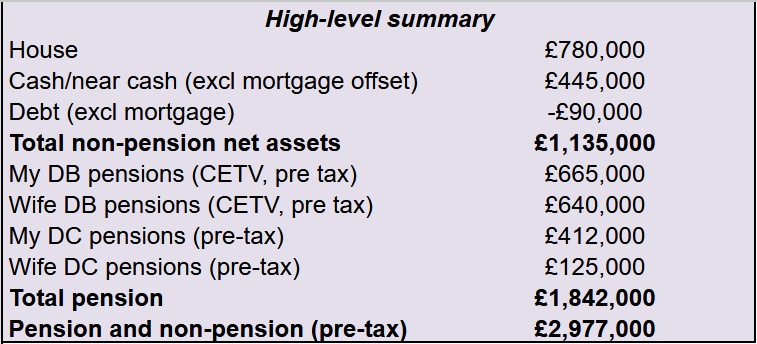
The mortgage is fully offset, so I exclude both the mortgage debt and the offset savings from the figures above. Almost all the Debt is 0% credit cards, which is giving a bit over £4,000 a year in interest. Some of that had transfer fees involved, but most of it was fee-free and so is pure profit.
In due course, about £45,000 (gross) will go into my wife's DC pension, and she will get a tax refund of around £28,000 (pension higher rate and PAYE overpayment combined). That will leave about £580,000 in our DC pots, which is about 50% in equities, 25% bonds and 25% other.
Future funding sources and amounts
The future falls into 3 periods, and about £80,000 p/a after tax should be available in all future years once the amounts from all sources are totalled.
(1) Now to age 55 - funded from cash savings, and if necessary withdrawals from the mortgage offset savings account which will then be replenished from DC at age 55. The cash savings should fund around £53,000 p/a of spending after allowing for all debt repayment and funding of a few known forthcoming expenses such as purchasing a chello for my wife, an air con unit in our main bedroom, and a holiday to Iraq at some point when things settle down there.
(2) Age 55-68 - funded from our Defined Benefit pensions (about £57,770 p/a combined, after tax), supplemented by withdrawals from DC pension to fully use our basic rate income tax allowances. Once all pensions are in place, we will repay the mortgage using the funds in the mortgage offset savings account.
(3) Age 68 - DB and State Pensions, £77,800 combined after tax
I plan to take maximum tax free lump sum from the DC pensions at age 55 and put them into an ISA. I will also commence DB pensions at that time so as to keep them as small as possible. This will limit exposure to higher tax in the future, as having a smaller income for longer is likely to be the best approach to guard against tax increases (either actual increases or fiscal drag) from future administrations. All surplus will go into ISAs. Over time, that will move all the funds from DC pensions into ISAs.
Regular expenses
All of our regular, predictable expenses are set out in the table below. This excludes travel, holidays, car/house repairs and decoration, capital spend such as white goods, car, or phone replacement, food, entertainment such as eating out, entrance costs, and clothes and running gear.
Annual
Monthly
Share
House bills, incl regular maintenance
£4,328
£361
33%
Council tax and green waste
£4,252
£354
32%
Pet costs (insurance, food, vet)
£1,375
£115
10%
Club memberships (running, bridge, National Trust, rambling, concert band, leisure centre)
£1,374
£115
10%
Car bills (Insurance, VED, MoT, Breakdown, Service, Cleaning)
£685
£57
5%
Medical (Contact lenses, dental, and eye checks)
£563
£47
4%
Other (Mobile phones, VPN, password manager, haircuts, presents, e-storage)
£584
£49
4%
Total
£13,161
£1,097
100%
Distant future
The table below shows our survivor pensions; as and when one of us dies the survivor will have an annual income of around £50,000 after tax.

We expect to sell our current house when we are about 75 as we are living in a 6 bed house that will increasingly become difficult to maintain as we age. We expect to move to a much smaller property in the area. That will release a lot of cash, but we do not have any particular plans for that - it can just be used for care costs if necessary.
Social side of things
Both of us have significantly increased our non-work activities. We are fortunate to have an excellent leisure centre we are both members of, and I have started doing several classes as well as swimming in recent months. We both also run with our local running club. Along with walking our Huskamute dog 3 times a day between us, that is quite a lot of exercise.
I've started to play the card game Bridge again, and will play more as we get into the winter months. My wife spends a lot of time playing music and playing in concert bands.
I've also found it interesting to spend quite a long time listening to various history podcasts - having done a lot of past travel, it is more interesting to understand how history and geography all fits together across time and continents. There is also much more time to engage with things like sporting events, news, politics, and following things more closely than I did when working.
I expect to spend less time with personal finances though, once I've sorted my wife's redundnacy finalisation, pension contribution and tax refund, there won't be a great deal to do. I'll still do things like bank account switching and exploiting 0% credit card offers though.
18 -
Congratulations @hugheskevi and Mrs HK. You've planned hard for this and it's great to see how your future plans are mapped out too.
Enjoy every moment of your retirements!
3 -
Great work! Out of interest, do you have protected pension ages for all of your pensions to allow access at 55?
0 -
All of our pensions have a protected minimum pension age. Most are 55, including the DC pensions, but some of the DB pensions have a protected minimum pension age of 50 as we joined them before 2006.
However, the DB pensions with the minimum pension age of 50 come with rules around revaluation and indexation that makes taking them before age 55 prohibitively expensive due to the size of the reduction applied for early access. I'll still consider taking them before 55, although I doubt I will take mine before then. My wife is more marginal however, so she may take the DB pension at some point between age 50 and 55.
0












Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.7K Mortgages, Homes & Bills
- 179K Life & Family
- 263.5K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards