We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Chancellor urged to delay ISA changes




Comments
-
I completely agree. Savers may be reluctant investors for a variety of reasons.
0 -
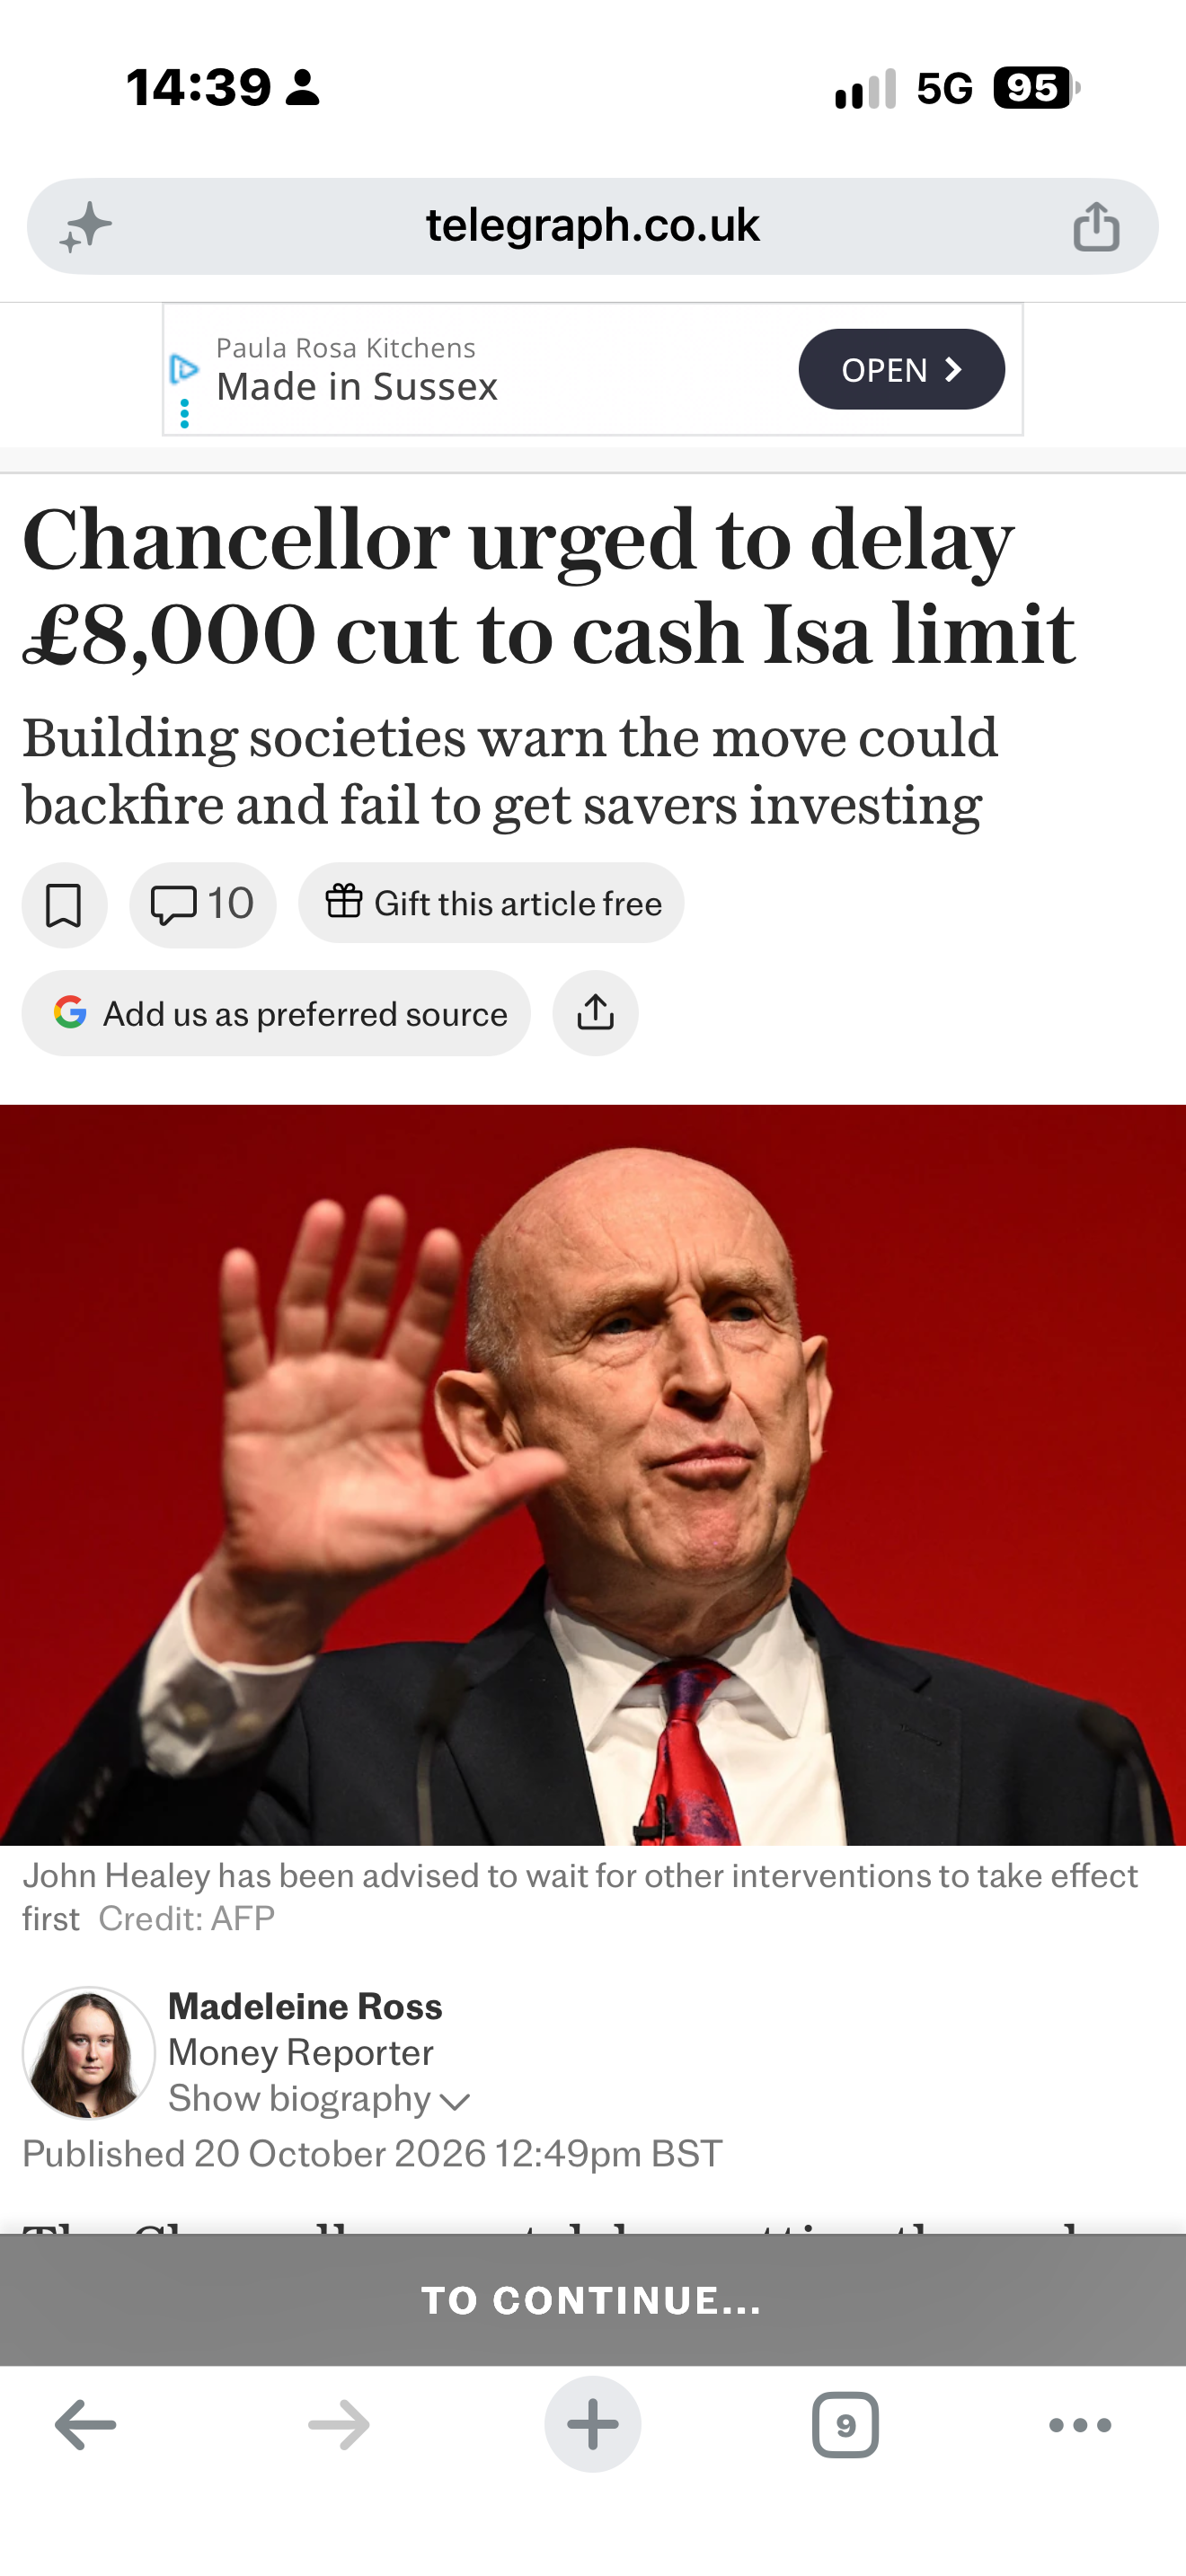
The Chancellor must delay cutting the cash Isa limit for two years because of fears the tax raid will backfire, building societies have urged.
Lenders said John Healey should pause plans to reduce the annual £20,000 cash Isa limit to £12,000 for the under-65s, as was proposed by former chancellor Rachel Reeves in her last Budget.
Ms Reeves made the change to encourage more savers to invest their money, rather than keeping it in cash. But experts have warned that the reforms are not enough to encourage savers into the stock market on their own, and that Labour should wait to see the outcome of other interventions – including an advertising campaign featuring a cartoon squirrel – before making such significant changes.
It comes after Mr Healey backed down on rumoured changes to capital gains tax at next week’s Budget because of fears that it could push wealthy investors overseas.
Sarah Harrison, chief executive of the Building Societies Association (BSA), told The Telegraph: “We are calling for the Chancellor to pause the proposed cash Isa changes for two years, allowing the other measures designed to encourage investment to take effect before deciding whether further reform is needed.
“Adding complexity and cost to a system that works well for savers makes little sense when so much else is changing. A pause would give the Government time to assess the evidence and make sure any reform genuinely helps people build their financial confidence.”
Other efforts to increase retail investment include improving access to automated financial advice, changes to the risk warnings that prospective investors see, and a new first-time buyer Isa.
Ms Harrison added: “We support the Government’s ambition to help more people invest, but weakening cash Isas risks being counterproductive.”
The BSA pointed to research from the University of Bristol suggesting that savers with a cash Isa were 83pc more likely to also invest.
But Michael Healy, of investment firm IG, said: “The changes to the cash Isa allowance were a step in the right direction, but they did not go far enough.
“The BSA is confusing correlation with causation. The fact that cash Isa holders are more likely to invest does not prove that generous cash Isa allowances encourage investing, or that delaying reform would help more people build wealth.
“The focus must be on getting more people investing. This requires less generous incentives to hoard cash, greater stability when it comes to investing taxes, and a bold new approach that makes investing habitual.”
Shadow chancellor Andrew Griffith said: “You name it, Labour will tax it. Even if it’s your savings that you put in a Government-backed Isa, which you were told would keep your money free of tax.
“But the best way to encourage that investment is by lowering the tax burden and simplifying the tax system – not making it more complex and punishing people for choosing to keep cash savings.”
Forecasts suggest that rather than moving into investments, the changes will push savers to instead keep cash outside the tax-free wrappers. The Treasury estimated that the measure would raise an extra £95m in savings tax by March 2031.
Concerns that savers would bypass lower limits – either by transferring funds from investment accounts back into cash ISAs or by holding cash-like instruments like money market funds – forced the Treasury to introduce stricter rules for tax-free accounts.
This included a 22pc charge on interest earned on cash held in investment accounts, and a ban on investors holding only cash-like assets.
In 2024-25, nearly £100bn was held in cash Isas. This number is likely to be higher for 2025-26, when rumours of the cash Isa changes became widespread.
The final Office of Budget Responsibility assessment of how much the reduced limit will make the Treasury is expected to be published at the Budget next week.
Further reforms to Isas, including more details on the new first-time buyer Isa, will also be published by Mr Healey, The Telegraph understands.
A Treasury spokesman said: “As has always been the case, decisions on tax are a matter for the Chancellor to set out at fiscal events, rather than routinely commenting on rumour, speculation or proposals.”
4 -
The changes won't encourage savers to invest more. It will just cause them to keep more money in tax-bearing savings accounts, thus raising more in tax.
If savers wanted to put some of their money into investment ISAs, they would anyway.
I consider myself to be a male feminist. Is that allowed?4 -
Not sure if the Telegraph was deliberately trying to provoke debate for the sake of it, but it's hardly surprising that a building society rep wants people to save more, while an investment company one promotes more investing - it's almost like they each have vested interests… 🙄
7 -
Actually I'm an example of someone where this is actually working and is encouraging me to invest more. I currently have a much too large amount of cash in savings, a large 6 figure sum currently, of which I have no pressing need or actual goal for, it's just sitting there and this amount will only go signifcantly up year after year by 5 figure numbers (if current circumstance continue). I've always been extremely cautious about investing and only have a few thousand pounds in a Stocks & Shares ISA (which has performed rather well over the years) and this rule is going to actually encourage me invest more. I might even put my whole allowance in S&S ISA rather than just the 8k. Mind you I was already thinking that I should start to move towards investing so it's not like this new rule was the only reason I'm doing this, I would have likely invested some of the ISA allowance anyway but this definitely has been a little extra push and reason to do it now. The timing just meant this did have it's desired effect on me but I can see why it won;t be as effective for most others.
3 -
Me too. I'm not against investing but I just procrastinate and don't get round to it (apart from a DC pension in a default fund). I will definitely be putting £8k in a stocks and shares ISA next April instead of leaving it in a taxable savings account. Some of us do seem to need a bit of a push.
0 -
But as we understand the new rules at the moment we'll still be allowed to put our money in money market funds as long as you have at least £1 in equities so it'll be easy to get around.
1 -
If you are now encouraged to put more into an S&S ISA, why aren't you doing this straight away, why wait until next April?
0 -
That's very true - but there is also the nasty (IMO) new rule that under 65s won't be able to xfer from S&S ISA to cash ISA. I have got a small amount of money in Royal London MMFs and they have made a slight loss when I last looked. In a cash ISA, the same money would have made a moderate gain.
0 -
I already said in my post!
I'm a procrastinator who takes a while to get around to doing stuff. I can generally find more enjoyable things to do with my time than educate myself on investing. But once I lose £8k from my ISA allowance I'll probably pull my finger out.
0









Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards