We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
LISA and FTB ISA


If you currently hold a LISA, but will most likely not have purchased a home before the First Time Buyers ISA is implemented, will you be able to use both to purchase a property? If you can have both would this mean you can invest a larger amount of money each tax year, rather than the current £4,000 limit?
Comments
-
AFAIK the details of the FTB ISA aren't confirmed yet - but I would bet the house that you will not be able to combine it with the LISA.
A few years ago, alongside the LISA, there was also a HTB ISA (not to be confused with the HTB Equity Loan scheme), which served a similar purpose (though the maximum house price was lower and the bonus was only added when it was redeemed). You couldn't use those simultaneously.
With that said - are you buying with a partner? Both of you can benefit from these schemes on the same purchase.
Know what you don't1 -
Thank you for the help.
I'm not planning on buying anytime soon but just looking to the future so could be with a partner or not.
My other thinking is that you could still add to the LISA but use it for pension rather than a first property, whilst using the new FTB ISA for a house and maximising government contributions on both. However, I would not have much time to build a large deposit with the FTB ISA.0 -
The details are still to be decided (at the Budget 2026) and are currently under consultation.
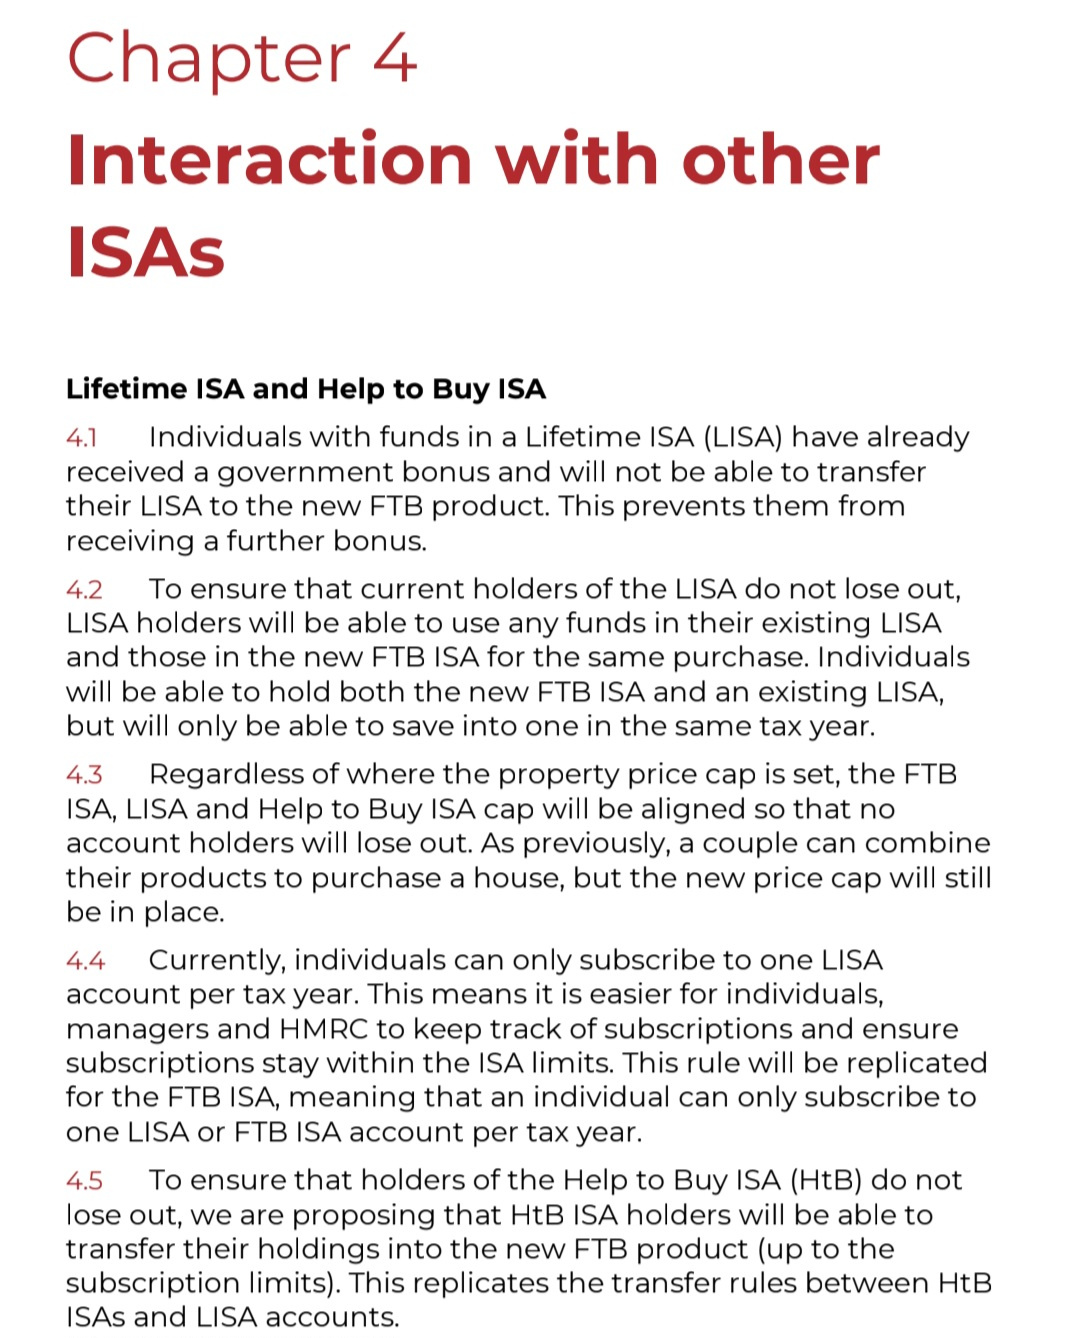 1
-
I stand corrected (thought it sounds like it achieves the same thing by only allowing you to contribute to one per tax year).
With that said, I definitely agree with that strategy - it would have been unfair to potentially make the FTB ISA more attractive, when there is a penalty for withdrawing from the LISA. But also prevents people double/triple-dipping on the bonus by contributing to a HTB ISA, LISA & FTB ISA at the same time!
Know what you don't1







Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards