We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Investec Fixed Rate ISAS - unusual maturity condition




I applied for an Investec 1 Year fixed rate ISA yesterday and on reading t and c's after applying noticed that on maturity the interest appeared to have to be paid away into your linked account. this seemed really odd to me so went onto their chat and this was confirmed that on maturity the Isa transfers to instant access ISA with interest paid away to linked account. There is no alternative. Decided to talk to phone and told that number just switchboard no telephone support for online accounts and to go back to chat box if wanted to discuss matter.
Have done this and instigated a complaint as I have NEVER had an ISA account were the accrued interest has to be paid away to non ISA account. It seems mad to me as alot of peolple will wish to keep the total money ISA wrapped. Just putting this on here to warn people as the condition is quite well hidden in the informationn section.
Now in process of cancelling transfer and moving to a more sensible institution, just hope i mannage to do this as Principality not recieved transfer request and Investec say they have sent it so up to Principality. This this may be a fraught time sorting it out.
Comments
-
I'm not sure what the basis of your complaint is since its in the T&Cs you agreed to. I doubt you NEVER having such an account is grounds for a complaint.
It's not very common amongst ISA providers, but Investec are not alone in doing this.
1 -
Certainly an unusual provision but not unique - I recall seeing it on here before with providers such as UBL (I think).
0 -
I opened a 1 year fix with them in April of this year (£20K), and had not realised this was the case - but upon checking it does indeed appear that it is, so thanks for the heads up.
I guess it was in the T&Cs and I just didn't read them in enough detail. Quite annoying as that'll be £900 losing it's tax free status next year (and a bit of a double whammy with the regular savings tax rate increasing next year).
I can't really see a complaint going anywhere if it was indeed in the T&Cs, but good luck and let us know how you get on.
1 -
maturity the interest appeared to have to be paid away into your linked account. this seemed really odd to me
It's not odd. A number of providers do it that way.
Not sure what you have grounds for complaining about. If that's the product they offer and those are the terms of the product, it is up to them. Just as it is up to you whether you wish to accept those terms. And with you cancelling, you have made the choice not to accept them.
Just putting this on here to warn people as the condition is quite well hidden in the informationn section.
I disagree that it's quite well hidden. It is on page 1 of 4 on their product term sheet. The product term sheet is what you always look at when buying a new financial product. It contains all the key facts about the product without all the longer detail.
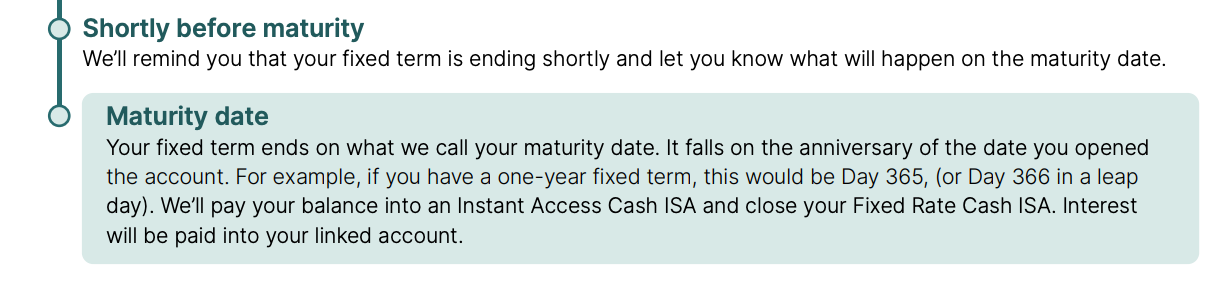
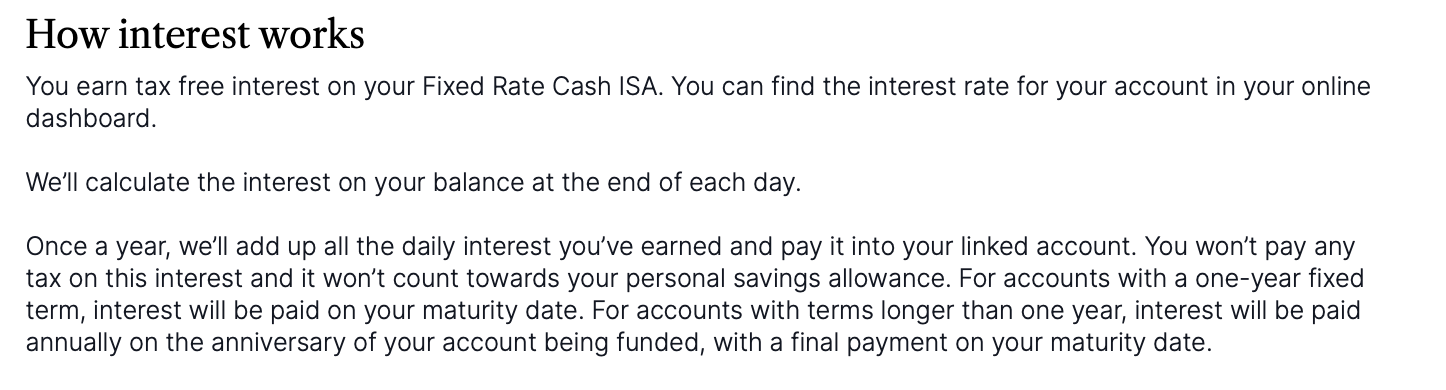
It also repeats it on page three under the section "How interest works".
 I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.1
-
The term raising a compalint was what Investec suggested when I said I wanted to feed back that I thought this was an usual way to treat interest. I am not looking for compensation just wanted to feed up the management that did not think this was a particularly good product.
I put the information on here to help other people as i certainly missed it initially.
For those chastising me yes i should have noticed but also it is the first time I have come across a product like this and am not a novice at isas or savings.
4 -
I find it curious that people don't think it is an odd provision to have in an ISA. It is a stupid provision to have in an ISA. Perhaps it was dreamt up by the same genius who thought it would benefit S&S ISAs if the government reduced the allowance for cash ISAs.
4 -
I find it curious that people don't think it is an odd provision to have in an ISA. It is a stupid provision to have in an ISA.
I think it's how you define odd.
It is "odd" in respect of it being a daft thing to have, and you have to wonder why there isn't an option to select to retain within the ISA or pay out.
However, it's not odd in the sense that it's unheard of.
Perhaps it was dreamt up by the same genius who thought it would benefit S&S ISAs if the government reduced the allowance for cash ISAs.
I wondered whether it's due to the background of Investec. They are a fund house that supplied income units which if you held them directly with them, rather than on platform, they required the dividends to be distributed. It's like they followed through on that mindset with their cash ISA.
For those chastising me yes i should have noticed but also it is the first time I have come across a product like this and am not a novice at isas or savings.
I don't think it's chastising you. It's more a matter of pointing out that not all products are the same and that the short key facts document (or whatever the provider in question calls it) should always be read as the short document is required to give the key facts about the product. Any unusual terms would be in that shorter document without you having to read the 20-30-page terms and conditions.
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.2 -
Probably this is the wrong place to mention it but I notice that with this new quoting system you don't get notified if someone quotes you.
0 -
You'll get notified when I quote your post directly like this (via the 'quote' button at the foot of your post), but not if I copy/paste some or all of your words into an unattributed quote (via the 'quote' feature of the text editor itself):
Probably this is the wrong place to mention it but I notice that with this new quoting system you don't get notified if someone quotes you.
The fact that directly quoted posts can no longer be edited has led to significantly increased use of the second route…
3 -
Thanks for pointing this out @ashteadgirl - I also opened an Investec 1 Year Fixed ISA (back in April) and missed this when scanning the Ts & Cs. 😕 I understand (as some have pointed out here) that it's not unheard of but it's certainly pretty unusual in my many years' experience of opening ISAs with many different providers. IMO it runs counter to the principle of building up as much of a savings pot as possible protected from tax (including the added interest) but hey ho, my bad for missing this! Thankfully I only put £4k of this year's allowance in this one.
2









Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards