We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Retirement Investment portfolio thoughts
Comments
-
I think in the past CGT, had a higher equity exposure. I assume ( maybe wrongly ) that the current low equity % is a management view that the markets are a bit toppy, and maybe due a significant corrrection.
0 -
The factsheet shows CGT's asset allocation since 2011.
Bear in mind that ILGs inflation linking moves from RPI to CPIH in early 2030 which, from historic data, will reduce the inflation-linked part of the return by about 0.9% pa.
0 -
I might be misremembering, but didn't you write to them at one point for a more detailed breakdown and it turned out their "risky" equities portion was quite a bit lower than the headline numbers would have suggested?
0 -
I don't remember that, but my memory is less reliable than (enter analogy of choice here). The asset allocation category is "equities/funds" and funds can be low risk… maybe CGT holds PNL or other wealth preservation funds.
0 -
Seems my memory was not too bad, but sadly the key image is lost to the Online Safety Act
However, due to the wonders of VPNs, I can resurrect:
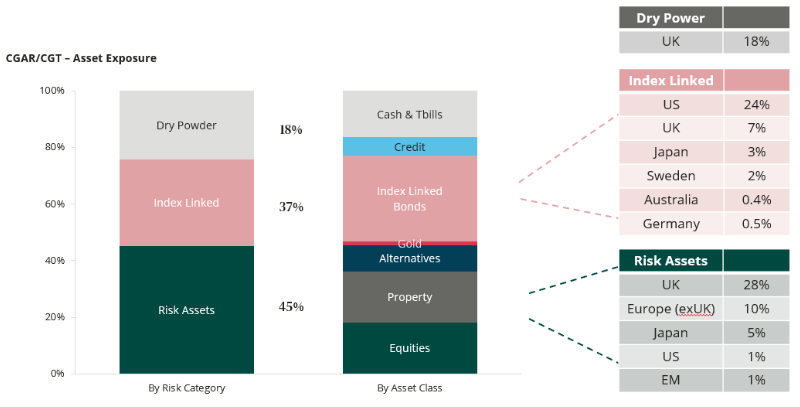
Cross-reference against the chart (March 2022) and you can see a big slug of property and smaller "alternatives" are included in "Funds / Equities"
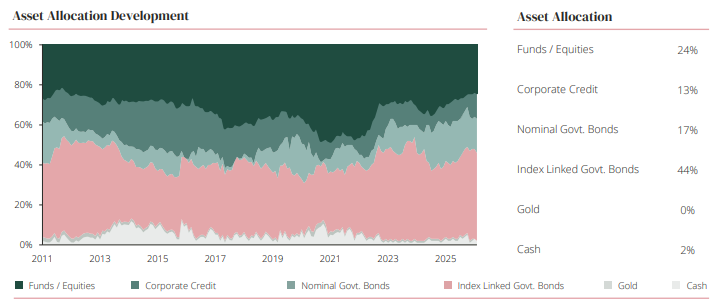
But property was not bricks & mortar, it was mostly REITs, and we know those are not low risk - as does Spiller having had them drag on his performance until he ditched most of them. Therefore I suspect the equities has been fairly stable over the past few years.
2 -
Impressive work, Poirot.
1 -
It looks like you've built a very solid position, and you've clearly put a lot of thought into your retirement plan. With a portfolio of this size and an early retirement target, even small decisions about asset allocation, withdrawal strategy, and tax planning could have a significant long-term impact. Have you considered getting a second opinion from a licensed financial advisor who specializes in retirement planning? Sometimes an independent review can either confirm your plan or identify areas you may not have considered.
-2 -
I avoid IFA, take too much in fees for little benefit imo. I tried before in my early years, very open ended answers.
Yes I got lucky with investment choices, but I do make mistakes, I'm currently in the red for MSFT when I invested over a year ago, only 4k invested, but is an example of smaller ventures.
After much thought and insight from the others above, I'll probably go for 70/20/10 VWRP/Glit ladder/MMF as the simplest and easiest option when the time comes to FIRE.
I'm going to keep on working for another few years max 6 years, as that is when my mortgage term end. Or when my investments 2.2 Mil, which ever comes sooner
The income portfolio I originally envisioned is too complex and the yields can change and will be a PITA to constantly having to rebalance and look for others. All VWRP just makes it simpler imo and withdraw when balancing needed
Glit ladder will be my Wealth preservation and just buy them in steps in time when I want to withdraw income and if I need the money etc.
"It is prudent when shopping for something important, not to limit yourself to Pound land/Estate Agents"
G_M/ Bowlhead99 RIP1 -
That's fair. If I'd had an experience where I felt the fees outweighed the value, I'd probably be cautious too. Your revised approach also sounds much simpler than your original plan, which can be a real advantage over the long term. Out of curiosity, what made you settle on the 70/20/10 allocation rather than something like 80/20?
0 -
Risk appetite, it's not set in stone atm, but 70-80% would be reasonable, I have alot of cash outside of tax wrappers, so I may put more into equities to balance this
"It is prudent when shopping for something important, not to limit yourself to Pound land/Estate Agents"
G_M/ Bowlhead99 RIP0









Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards