Ready, steady… save!
You don’t need a chart to join in. Here are 2 ways to record your savings:
1. Cross it off
Pop a chart into your first post. Saved an amount? Cross it out! Read more »
£0.01 £0.02 £0.03
2. Write it down
Skip the chart and add updates to your first post. Read more »
“Another +£3 saved today. Go me!”
Use +£ before each new saving so it counts towards your total.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Steadying the ship - a perilous voyage across the financial middle
Comments
-
Thanks for the update ed, it is always reassuring to hear things are ticking along, albeit with peaks and troughs. Saving over £1100 this month is impressive. Mine were nudged along by two PB wins; a £500 and a £25 - both reinvested automatically. Still not at £40k but our percentage win so far is 5.07% so far this year on the bonds in my name. Nothing since we withdrew £10k from Mr Sl's holding to buy the truck in March.
I've got to cram 6 months study into three weeks before my next exam on 14th November (eek blue screamy thing) - take care and keep on keeping on!
Save £12k in 2026 #2 I have banked £10,836.47 in 9 months, against a £10k target The Save £12k in 2026 thread is here
OS Grocery Challenge in 2026 I have a £3000 annual budget for 2026 - currently £2270.73 to the end of Oct
I also Reverse Meal Plan on that thread and grow much of our own premium price fruit and veg, joining in on the grow your own in 2027 thread brand new and sparkling - feel free to join us and say what and how you are planning
My keep within our budget diary is here5 -
Anyone else enjoying this being Ed's version of simplification 🤣?
 Mortgage start: £65,495 (March 2016)
Cleared 🧚♀️🧚♀️🧚♀️!!! In 5 years, 1 month and 29 days
Total amount repaid: £72,307.03. £1.10 repaid for every £1.00 borrowed
Finally earning interest instead of paying it!!!6 -
Wow - @Suffolk_lass - £500 is a lottery win! 😆
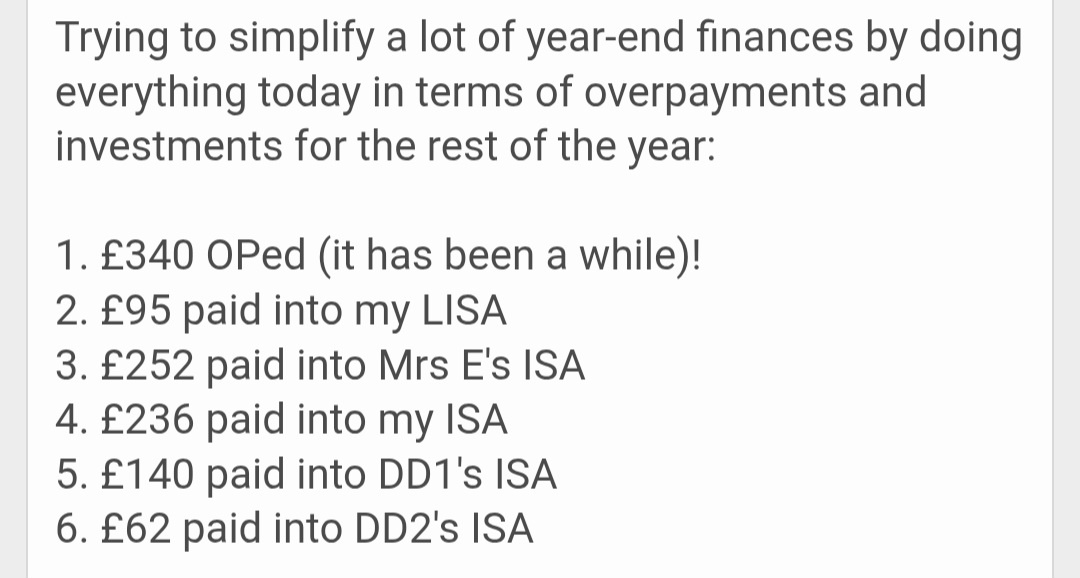
@South_coast - you should just be pleased I'm using my LISA 🤣£25.76 paid into my SIPP from personal spends for the rest of October - I have got into the habit of trying to add an ETF unit a day. It's only where I'm swimming in spare money because I haven't felt the need to buy anything for the month beyond beers and odd expenses on family days out.
I have reached the realisation that I am quite possibly at the end of my side hustle road 😯 Every day the AI emails come in from survey/tasker websites, and every day I reach the conclusion that I don't have time/headspace. Although I had often said to Mrs E that uni would "become" the time I spent on surveys, I don't think I'd ever properly accepted what this would mean in terms of changes to my routine/the wee dopamine hits that keep the financial machine chugging on… I also can't quite imagine getting to the end of uni (aged 47) and deciding "yay, time for more drudgery!"
My timeline looks like this (🤞) -
1. End of October - finish off long-term study around internet habits, get paid £40 and finish using Y Live - last payment expected mid-December. This would fill my trading allowance to within £5 or so. Possibly earn another £10 or so from Prolific just to use the full £1,000 allowance. Then "soft quit" Prolific - redirect emails to unread folder - leave the option to return if I need a wee cash injection at some future point where I have any spare time.2. Start/mid-December - pay increment of c. 6% due. This will add a small amount to my wages, perhaps £135/mth.
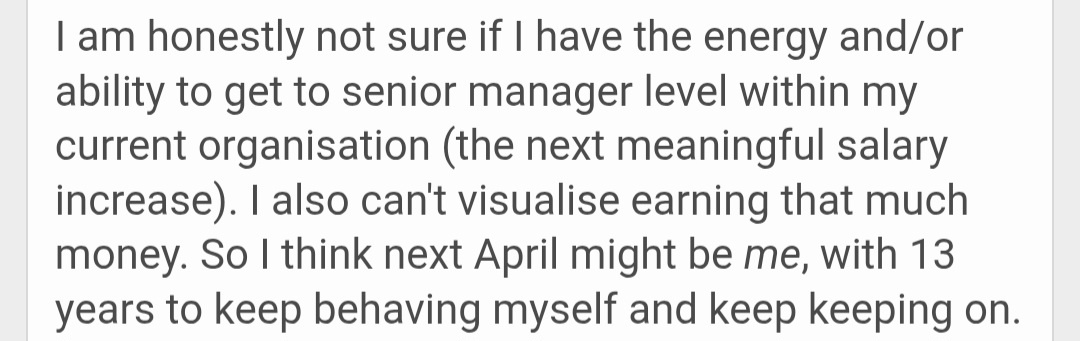
3. Late April - proposed salary change to an amount that would mean that I have to actively avoid losing some of our child benefit. I don't feel we can afford to lose any of this to tax. As such, any additional salary (or side hustle money above the trading allowance) would need to go straight into pensions. I feel that our pensions are good but that we've neglected wholesome things like mortgage overpayments, cash savings, and investing in our ISAs to bridge the gap to early retirement.
I am honestly not sure if I have the energy and/or ability to get to senior manager level within my current organisation (the next meaningful salary increase). I also can't visualise earning that much money. So I think next April might be me, with 13 years to keep behaving myself and keep keeping on. It feels like one of those strange "taper" points in the tax system, where any extra money is basically only going to be mine in 10+ years (unless I'm willing to be taxed 40%+ on it. I'm not!) Also the realisation that side hustle money has never been "free" - it has meant not doing something else. I'm going to have to re-learn how to spend the non-working/caring parts of my days. I am slightly jealous of Mrs E in that respect, who will have a day off once DD2 goes to school next year.
Thank you for humouring my Sunday noodling 😅
*Edit: Also chased Civil Service pensions for an updated value - they used to have a website that let you see a real-time estimate of this but it disappeared c. 18 months ago?
12 -
It won't just be me here. I've noticed the forums are quieter at the weekends. I love the couple of hours I get when everyone else in the household is asleep.
Dog now on lap, husband has just spilt porridge over the freshly cleaned hob. I cleaned it when I got home to remove the fat spatter, and again this morning, along with the newly "heat-treated" stainless steel hob top kettle he boiled dry while I was away for 3 nights.. ho hum!
Save £12k in 2026 #2 I have banked £10,836.47 in 9 months, against a £10k target The Save £12k in 2026 thread is here
OS Grocery Challenge in 2026 I have a £3000 annual budget for 2026 - currently £2270.73 to the end of Oct
I also Reverse Meal Plan on that thread and grow much of our own premium price fruit and veg, joining in on the grow your own in 2027 thread brand new and sparkling - feel free to join us and say what and how you are planning
My keep within our budget diary is here6 -
A busy wee morning!
Emptied, re-packed and then emptied the dishwasher, processed three loads of laundry, got rid of some recycling, and am currently cooking a Sunday roast (ham, roasties, Yorkshires, carrots and broccoli). Mrs E stormed through a toy clearout, and we are now much more ready for the festive period 😅
As is the style, when I stopping thinking about ways to save and invest money, I promptly came up with a way to save money! I realised that the settings on our dehumidifiers were set up for when we had them on the different floors of the house. Amended them both to match, increasing the time by a wee bit on one and decreased the time by a good bit on the other. Long story short, it will save 2 hours of usage a day, which will be £3-6 a month less electricity. I have set up a £3 SO to the mortgage in the spirit of good behaviour.8 -
Love looking for small savings and then repurposing the cash elsewhere. Always ,makes me think I am winning at the game.
Made it to mortgage free but what a muddle that became
In the event the proverbial hits the fan then co-habitees are better stashing their cash than being mortgage free !!8 -
Not a great week, feeling intensely anxious about small but important workplace decisions where approvals are sought but are never received. Unfortunately they're at the level of seniority where I don't have recourse without bothering the executive tiers of the organisation, and I'd be painted in a bad light if I went there…
I made a decent start to my first university assignment, although I need to be careful that I don't rest on my laurels, 5 weekends to go before it's due.
I made a £
3053 overpayment yesterday (travel-related budget lines each donated £10, not as if I'm going anywhere with all the stormy weather)!8 -
I am with you on this. More money would be great, but I can't see myself mustering up the enthusiasm to really push myself forward to go after it, when I'm doing fine with what I already get. I'm not quiet quitting, but I am perfectly happy to tread water now until retirement. Just need to try and still sound hungry when it comes to appraisal time 🤣
Mortgage start: £65,495 (March 2016)
Cleared 🧚♀️🧚♀️🧚♀️!!! In 5 years, 1 month and 29 days
Total amount repaid: £72,307.03. £1.10 repaid for every £1.00 borrowed
Finally earning interest instead of paying it!!!5 -
Same here, in all honesty. I did the big, shiny, well-paid, multi-national, corporate role and couldn't hack the illogical, inefficient politics …
Quite happy here, pootling along in a much smaller role, having gained useful experience that the business finds useful and helpful … 😊🤷♀️
KK
As at 16.10.26:
- When bought house £315,995 mortgage debt and end date at start = October 2039 - now £209,304
- OPs to mortgage = £20,180 Estd. interest saved = £10,393 to date
c. 17 months reduction in term
Fixed rate 3.85% ends October 2030
Read 79 books of target 52 in 2026 as @ 1st November.
Produce tracker: £348 of £400 in 2026
Watch your thoughts, they become your words.
Watch your words, they become your actions.Watch your actions, they become your reality.9 -
Harumph!
Month-end report was disappointing, to put it mildly. Savings rate of c. 30% but we went backwards by c. £1,000 (total) or £4,000 (strict/portable).5









Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.9K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.4K Work, Benefits & Business
- 606.1K Mortgages, Homes & Bills
- 179K Life & Family
- 263.9K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards