We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
bond ladder - now or later?
Comments
-
I should have thought this earlier..
I also have a ‘top up’ fund of 35k I’m using to bridge two years until my DB starts at 60. I could put that in CSH2 but if I can’t buy fractions then buying might be ok but selling might not be clean when I need 17500 out at the end (or more likely 19k for inflation).
so.. why not buy another 2 year gilt ladder?
- they’re ETFs and I’m already capped at £120 so 0 cost to hold (I’d pay 0.25%)
- no OCF (0.1% for CSH2) - so thats a 0.35% saving to offset potential lower yields vs MMF
- rates are good enough
- they’ll mature directly into cash ready to be moved to drawdown
if I put 17.5k in TG29 and TR29 they’ll mature to around 19.5k in 2029 and 20.5k in 2030. Just sweep all the cash into drawdown, take the TFC and set up monthly FAD for the rest and thats me for the year? (leaving enough for platform fees of course)
0 -
May I ask for what scenario / level of investment does a "bond ladder" take preference over a "Cash ISA ladder"
With £80k able to be put into an Cash ISA (both of us £20k each in March and £20k each in April) I thought I had done well to create a ladder of rolling maturities and plan to do again in 2027 (noting a potential reduction in annual cash limit coming).
The "bond ladder" brings some additional administration that the Cash ISA doesn't.
My only thought is that a "bond ladder" can lock in to yields for longer (Cash ISA is on rolling 5, 3, 1.5 fixes) is that the key advantage?
0 -
I think its mainly visibility of yields. you can see the yield you’ll get and you can lock those in 30 years out. with cash ISAs all you get is the rate you can see now for the longest fix they offer and then its a dice roll. I valued the certainty. So in my case I spent 67500 to get 10k per year guaranteed for 9 years. I couldn’t do that with a cash ISA ladder, I’d likely have to hedge with a larger balance
1 -
In my view a cash ISA and a bond ladder serve very different purposes.
A bond ladder provides steady long term ongoing income. But the downside is that if you need to sell in an emergency you are taking some level of risk that the price is low.
A cash holding, whether it is in an ISA or not, is for spending in the short trrm. If you want to be able to make large purchases at short notice then holding a large amount of cash is a sensible option with any interest being a secondary concern.
4 -
A rolling ladder (i.e., one where the proceeds of maturing rungs are used to purchase rungs at longer maturities) has interest rate risk - for short ladders, whether in savings accounts or bonds (or short duration bond funds which are essentially rolling ladders), the risk is relatively small. With nominal bonds and cash there is also inflation risk even with short ladders - as we saw only a few years ago, inflation can increase very quickly.
For collapsing ladders (i.e., where the proceeds of maturing rungs are used to cover liabilities, i.e., spent!), the cashflows are known in advance. One advantage of bonds (as you say) is that you can set up longer ladders (out to nearly 50 years in the UK), while a second advantage is that, with inflation-linked gilts, inflation protection can be built in.
Apart from the practical upper limit of about 5 years for fixed-term cash (there are a handful of 7 year products with relatively low rates) and the somewhat 'lumpy' nature of gilt maturities (particularly for ILGs), where the border between using fixed-rate cash (sometimes easier and sometimes with better rates - depending on tax) and bonds lies is a probably a 'how long is a piece of strong?' type question!
3 -
ah the joy of pension admin with tens of thousands at the click of a button.
doing what I thought was a simple partial transfer. log in to workplace pension yesterday - ‘sorry we can’t find your account’ and my balance shows empty.
I freak out.
I call them this morning - oh its frozen pending closure. What?? can you double check, should be a partial only. They check - oh yes its partial. we often just remove the balance as we’re selling assets to fund we can’t show an accurate balance. ignore the error message (and I guess ignore we just told you we are closing the account) it should all be ok in a day or two.
the importance of pension admin and explicitness in messaging, combined with the ‘oh it does that sometimes’ still surprises and disappoints me in equal measure
0 -
I had this with Royal London late last year. Did a partial transfer, received a letter saying they were going to close my account etc. Phoned them up and apparently this was a normal communication and they were not going to close my account. Put in a complaint and got sent a nice Christmas Hamper. Still think RL are hopeless as this has not the only issue. Same, app did not seem to report an accurate figure until the process was complete.
2 -
ah the joy of pension admin with tens of thousands at the click of a button.
I think they must all have their quirks.
With Scottish Widows (my workplace pension provider) it's always a adventure when I try to change my investments.
Over the past couple of years, as my planned retirement date has firmed up and I've been looking to build a collapsing gilt ladder to bridge from then until SPA, I've been moving tranches of pension from my multi-asset fund into individual gilts.
There have been at least three occasions when, despite their online system offering me a gilt to buy and accepting my order, it has sold the correct amount of multi-asset fund to cash but has failed to then buy the gilt. I email SW to ask what's going on, and then SW take a variable amount of time (in one case, three months) to put it all back like it should be. The three month one was treated as a complaint and they paid me £75 of goodwill money and £500 of restitution(?) into my pension.
Also, there was a period of a few months when their system wouldn't show gilts as being a thing you could buy, even though I'd done so before (and would do so again).
And another period when it refused to let you move more than £15k at once, so any larger transactions needed to be done as two or more separate changes (each with their own £9.95 fee).
It's all part of life's rich tapestry 😂
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Ofgem cap table, Ofgem cap explainer. Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Best kettle!
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.2 -
Thank you for the informed responses to my question, my knowledge is a little deeper now by learning of the lock-in-for-longer options, not having to hope/guess what the rate may be at the maturity of each fixed term Cash ISA and also of the inflation protections that can be built in.
I feel we are sitting on too much bridge cash (my risk appetite is much higher than zero risk approach of OH) but I can just about stomach it as we are currently getting 4.18% average return on the suite of rolling fixed term Cash ISA's and that rate will increase next month when the next maturity / reinvestment happens.
I will continue to learn and explore the options that a bond ladder may offer.
0 -
I can just about stomach it as we are currently getting 4.18% average return on the suite of rolling fixed term Cash ISA's and that rate will increase next month when the next maturity / reinvestment happens.
For comparison, here is the yield curve for nominal gilts:
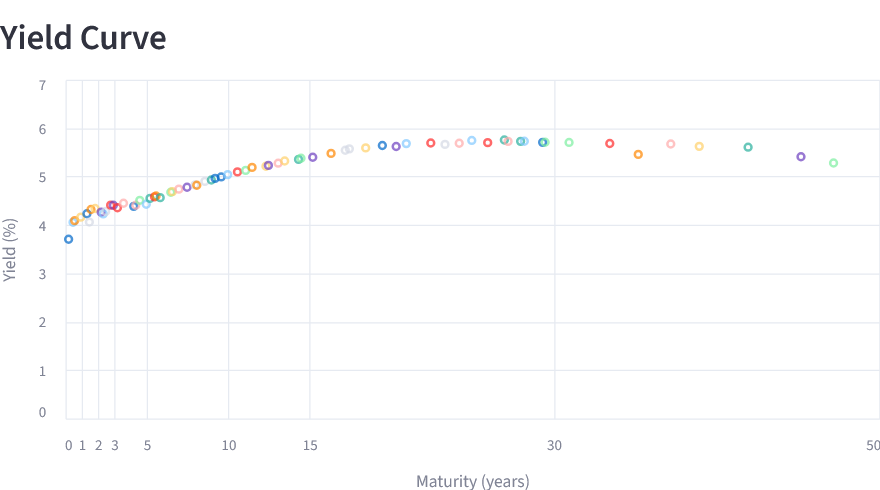
So you can get ~4.3% for 2 years, or ~5% for 10 years, when held to maturity.
For index-linked gilts it looks like this:
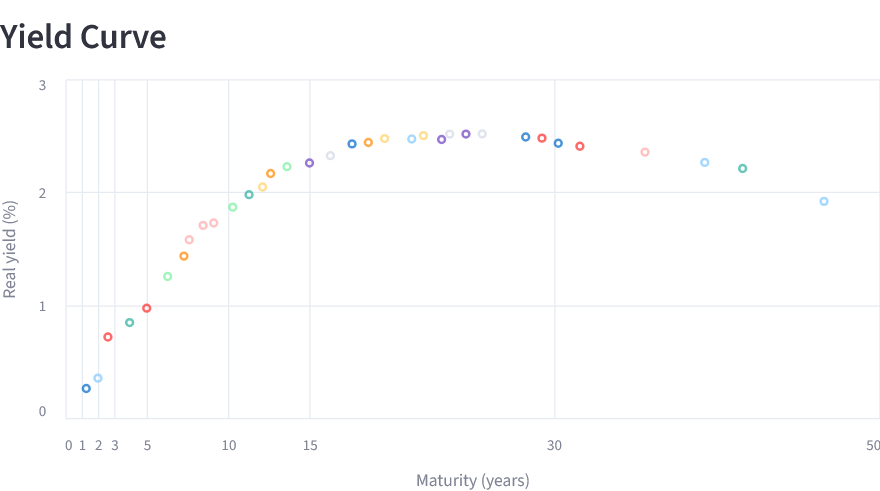
You can guarantee to beat inflation by ~0.35% for two years, or by ~1.87% for ten years.
Both curves from the LateGenXer tool here.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Ofgem cap table, Ofgem cap explainer. Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Best kettle!
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.2













Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.5K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards