We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
bond ladder - now or later?





been playing with bridges. I do plan to have this money mostly in fixed income. slowly moving into IGL5 with the view of maybe some CSH2 before retirement to fund the bridge each year as needed with low volatility funds or a bond ladder to lock in yields.
However, the question then is ‘when’.
playing with ChatGPT and latgenx bond ladder generator. If I set up a simple ladder for the top up bridge (only around £8500 a year) with a 2% increase per year, it costs me around £65k now, holding to maturity starting to pay out in 2029 for 9 years.
this is vs holding around 76k aside for the same thing in fixed income assuming 0% real return.
seems a decent saving, yields are good at the moment. But chatGPT has suggested waiting until closer to retirement and holding the funds in IGL5 instead (partially there, will have the rest by around april next year). The argument being - if yields rise, thats good for locking in the ladder later. And if yields drop, IGL5 should rise, countering that drop? Does this make sense? Might be chasing too much optimisation considering I’m less than 3 years out.
Comments
-
"And if yields drop, IGL5 should rise, countering that drop?" Then if yields rise, IGL5 should fall. IGL5 doesn't have magic properties. It should, in theory, keep you in a static position until you buy your bonds, but you are adding risk (it might go up or down, not in line with your expectations) and paying a fee to the fund manager. Here's the year-to-date chart:
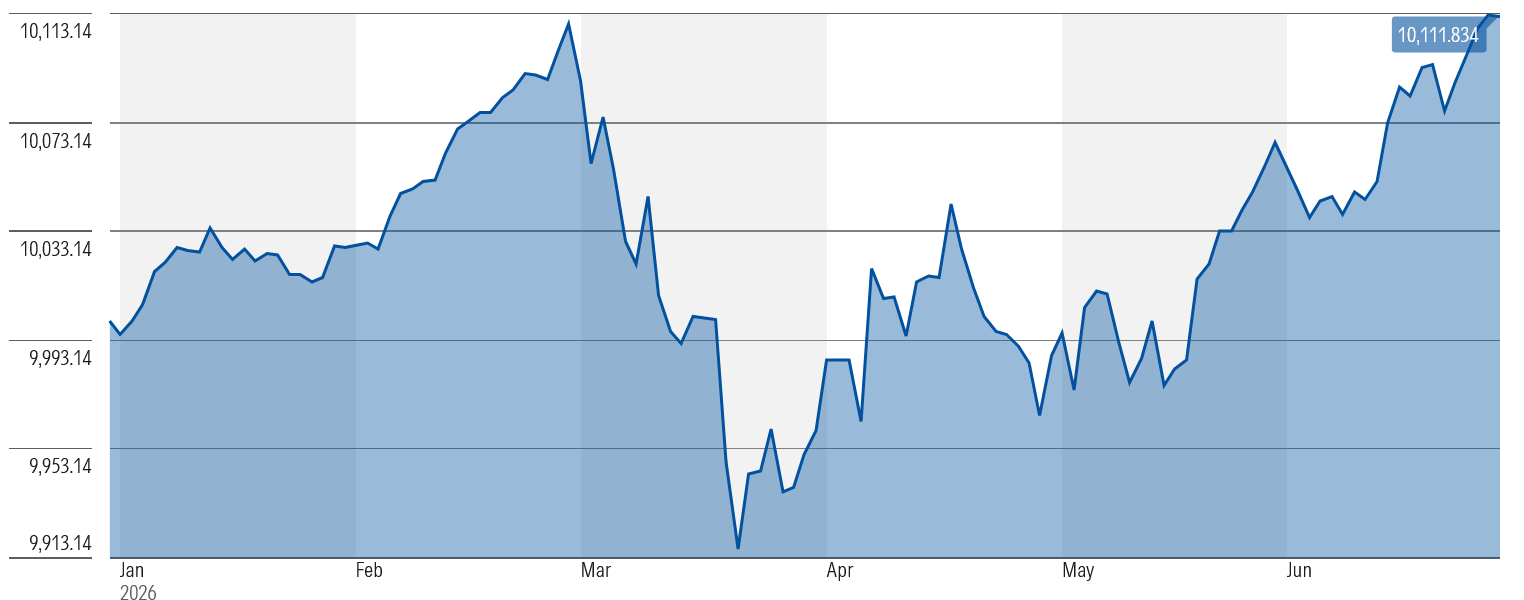
Is that the kind of volatility you are looking for in an effort to protect your funds?
If you are happy with current yields - if they meet your needs - then why not lock them in now. If you wait in IGL5 you might do better, you might do worse. Are you okay with doing worse, or will it derail your plans?
If I was looking as far out as 2038, I would be buying Index Linked Gilts. Currently they assume an inflation rate of about 3%. If it turns out to be 2% you lose out a little. If it's 5% (and remember, it was 10% not long ago), you make out. In any case, you protect the value of your bridge against prices in the supermarket, better than a fixed gilt.
1 -
That chart looks dramatic, but it's all within 1% up or 1% down from its starting value. 😀
2 -
2% drop in 3 weeks in March. Pretty interesting for a bond investment.
0 -
it wouldn’t derail if it dropped. Im only looking at around 9-10k per year for this portion of the bridge so it’s more about certainty of the bridge being secure. After state pension we are covered with SP and DB.
I still estimate to have 120-150k separate funds in VWRP that I don’t plan to spend down at all on desired income
0 -
Does your proposed gilt ladder contain inflation linked or nominal gilts?
I note (using lategenxer tool) that a 9 year ILG ladder starting in 2029 would cost about £72k to put together.
If nominal (and the 2% escalation you mentions suggests that) then there are a number of points that can be made.
Building the ladder now guarantees (in the absence of UK debt default) the planned income stream (although there's a decision as to what to do with coupons before the ladder starts - the lategenexer tool assumes you keep those in cash, but they could be reinvested in the first rung of the ladder). However, using IGL5 in an attempt to duration match does not guarantee the required income stream for several reasons, the main one being that the duration of IGL5 (~2.2, average maturity~2.3 years) does not match that of the implied delayed ladder (which starts with an average maturity of roughly 6 years, the duration will be smaller than that). The second one being that duration matching only works well where yield curves are and remain fairly flat with maturity and future changes in yields are small.
1 -
was plannign nominal yes and just doing a simple uplift. The thinking was partly simplicity vs linkers which I still don’t have a full grasp of, and so I’m more likely to stick with a nominal ladder. And partly if there is a severe inflation shock I can flex or live with a downturn in purchasing power for this relatively low portion of the bridge or draw a little extra from other funds if needed.
good point on the coupons. I was using Lategenexer with a 2.5% cash interest rate so I would likely just use MMF for that - again partly for simplicity setting up a dedicated MMF that exists to provide this specific income stream so I know in April each year I can draw whatever is in there for the year ahead
0 -
With that crazy Y axis it looks like the Himalayas, but as others have noted it's a variation between 9.9 and 10.1
"Is that the kind of volatility you are looking for in an effort to protect your funds?" - I imagine their thinking would be "yes"….?
1 -
I'm not sure that IGL5 is a good hedge against bond yield fluctuations for your timeline. The average maturity of that fund is around 2.5 years whereas your bond ladder final maturity is over 10 years away. So if yields drop before you start your ladder, you'll be worse off with this strategy.
If you're certain you will start the ladder then start it now. Even if you change your mind, it's easy to unwind.
1 -
I agree and I agree, but just to point out one thing, it's not quite comparing like with like. IGL5 is constantly refreshed by the manager. So, if you come back in 5 years, the bond ladder maturity will have shortened by 5 years. IGL5 will still sit at 2.5 years. I still wouldn't be using it for this purpose though.
1 -
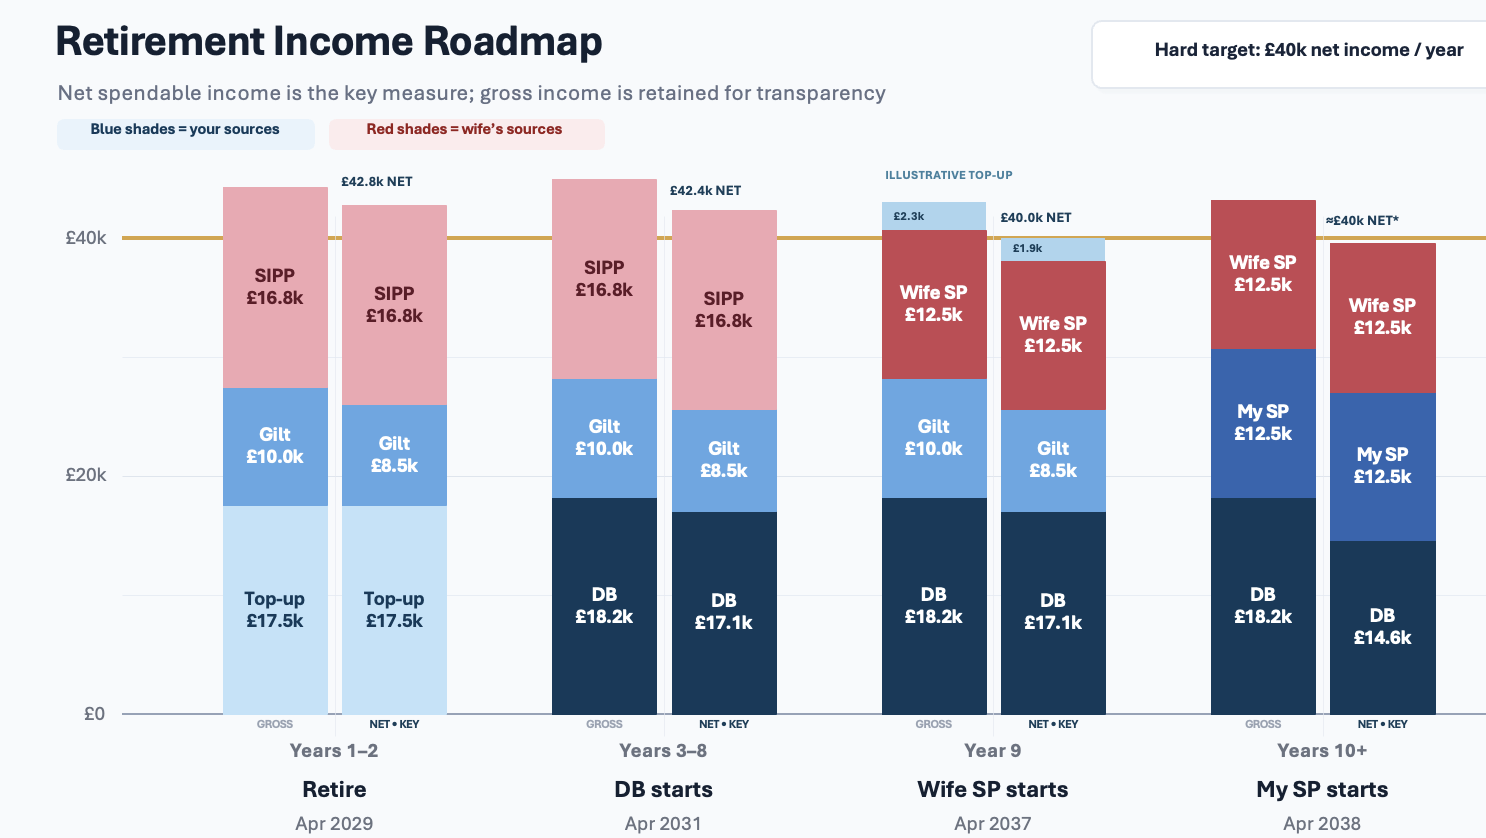
update. I've opened an account with AJ Bell and initiated a transfer of funds needed for the gilt ladder. Later as my workplace pension builds up funds I'll do a partial transfer to get the 'top up' amounts into MMF in AJ Bell too. That covers my DC portion of the bridge fully locked in with nominal funds. Gilt ladder needs 9k gross for 7.5k net, but I'm doing 10k gross per year to give me a little buffer and potentially putting aside some earlier years excess to self insure for inflation later on in the 9 year bridge. Linkers were a step too far for me in understanding them well enough to go that route.
here is the planned makeup of the bridge and then post SP where DB+2xSP covers all needs. all the lighter blue should be in place by the end of the year while keeping around 120k in VWRP. once that's set up I'll redirect all contributions back into VWRP hoping to build up to around 200k, while also pushing 22k a year into my wife's SIPP to leverage her personal allowance fully
getting real now
 3






Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.5K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards