We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Should I claim on my insurance?




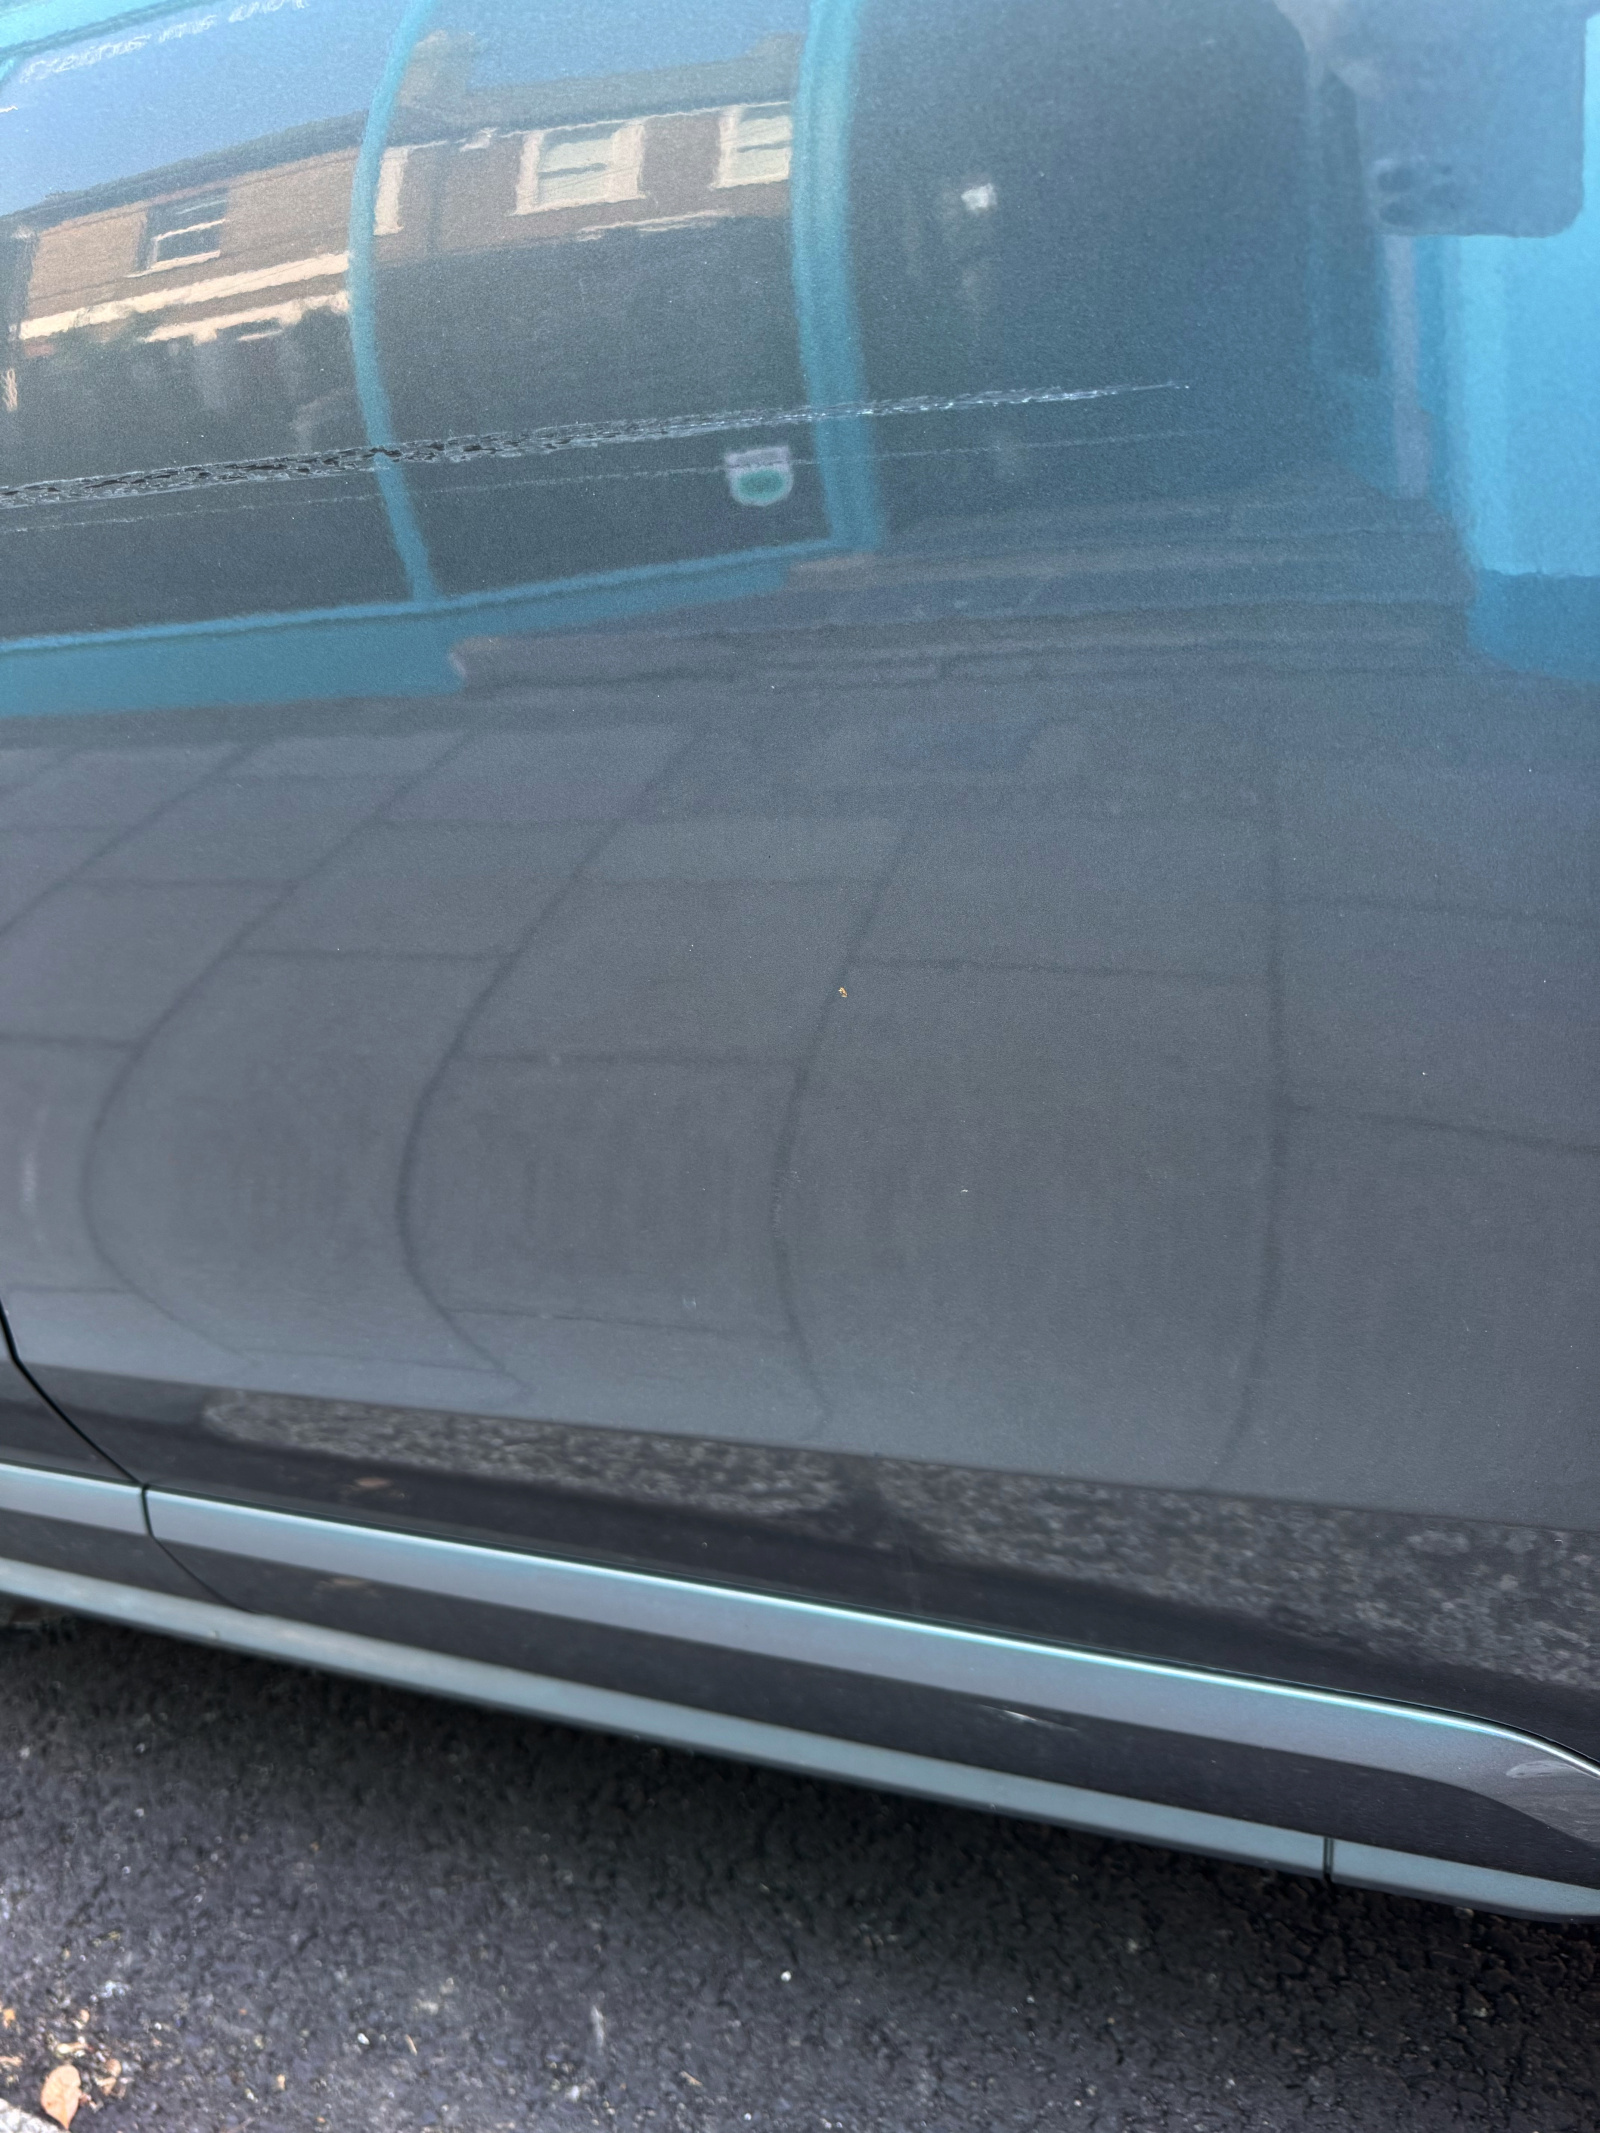
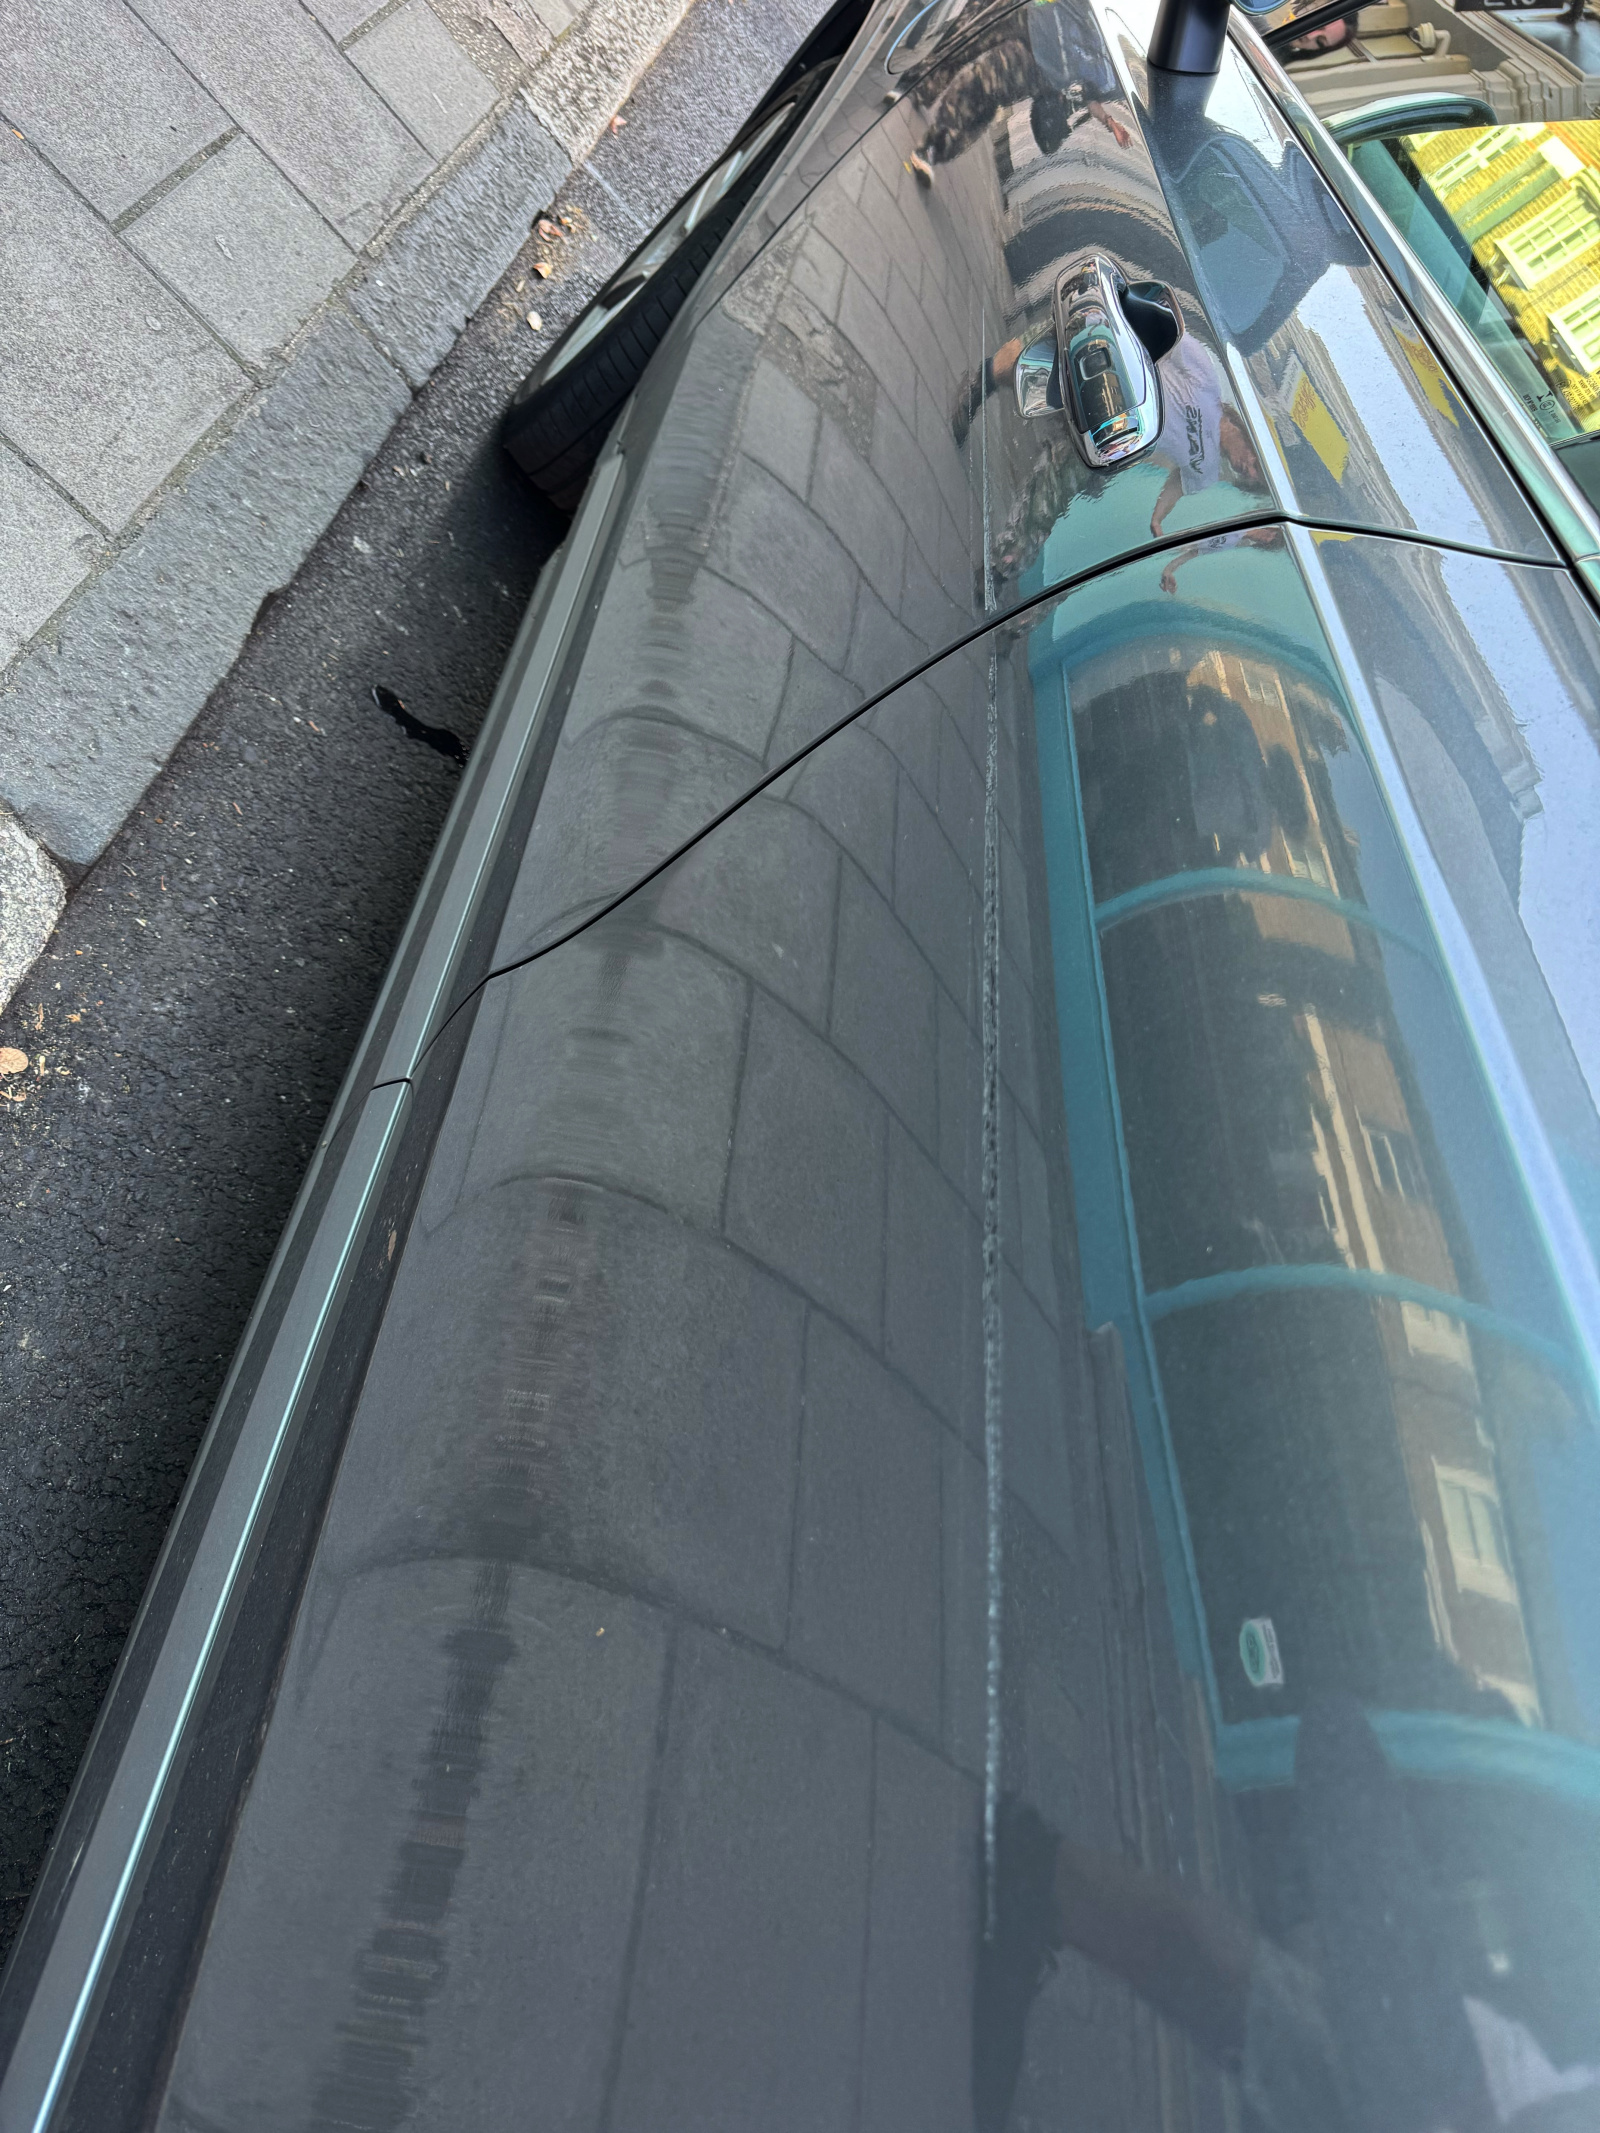
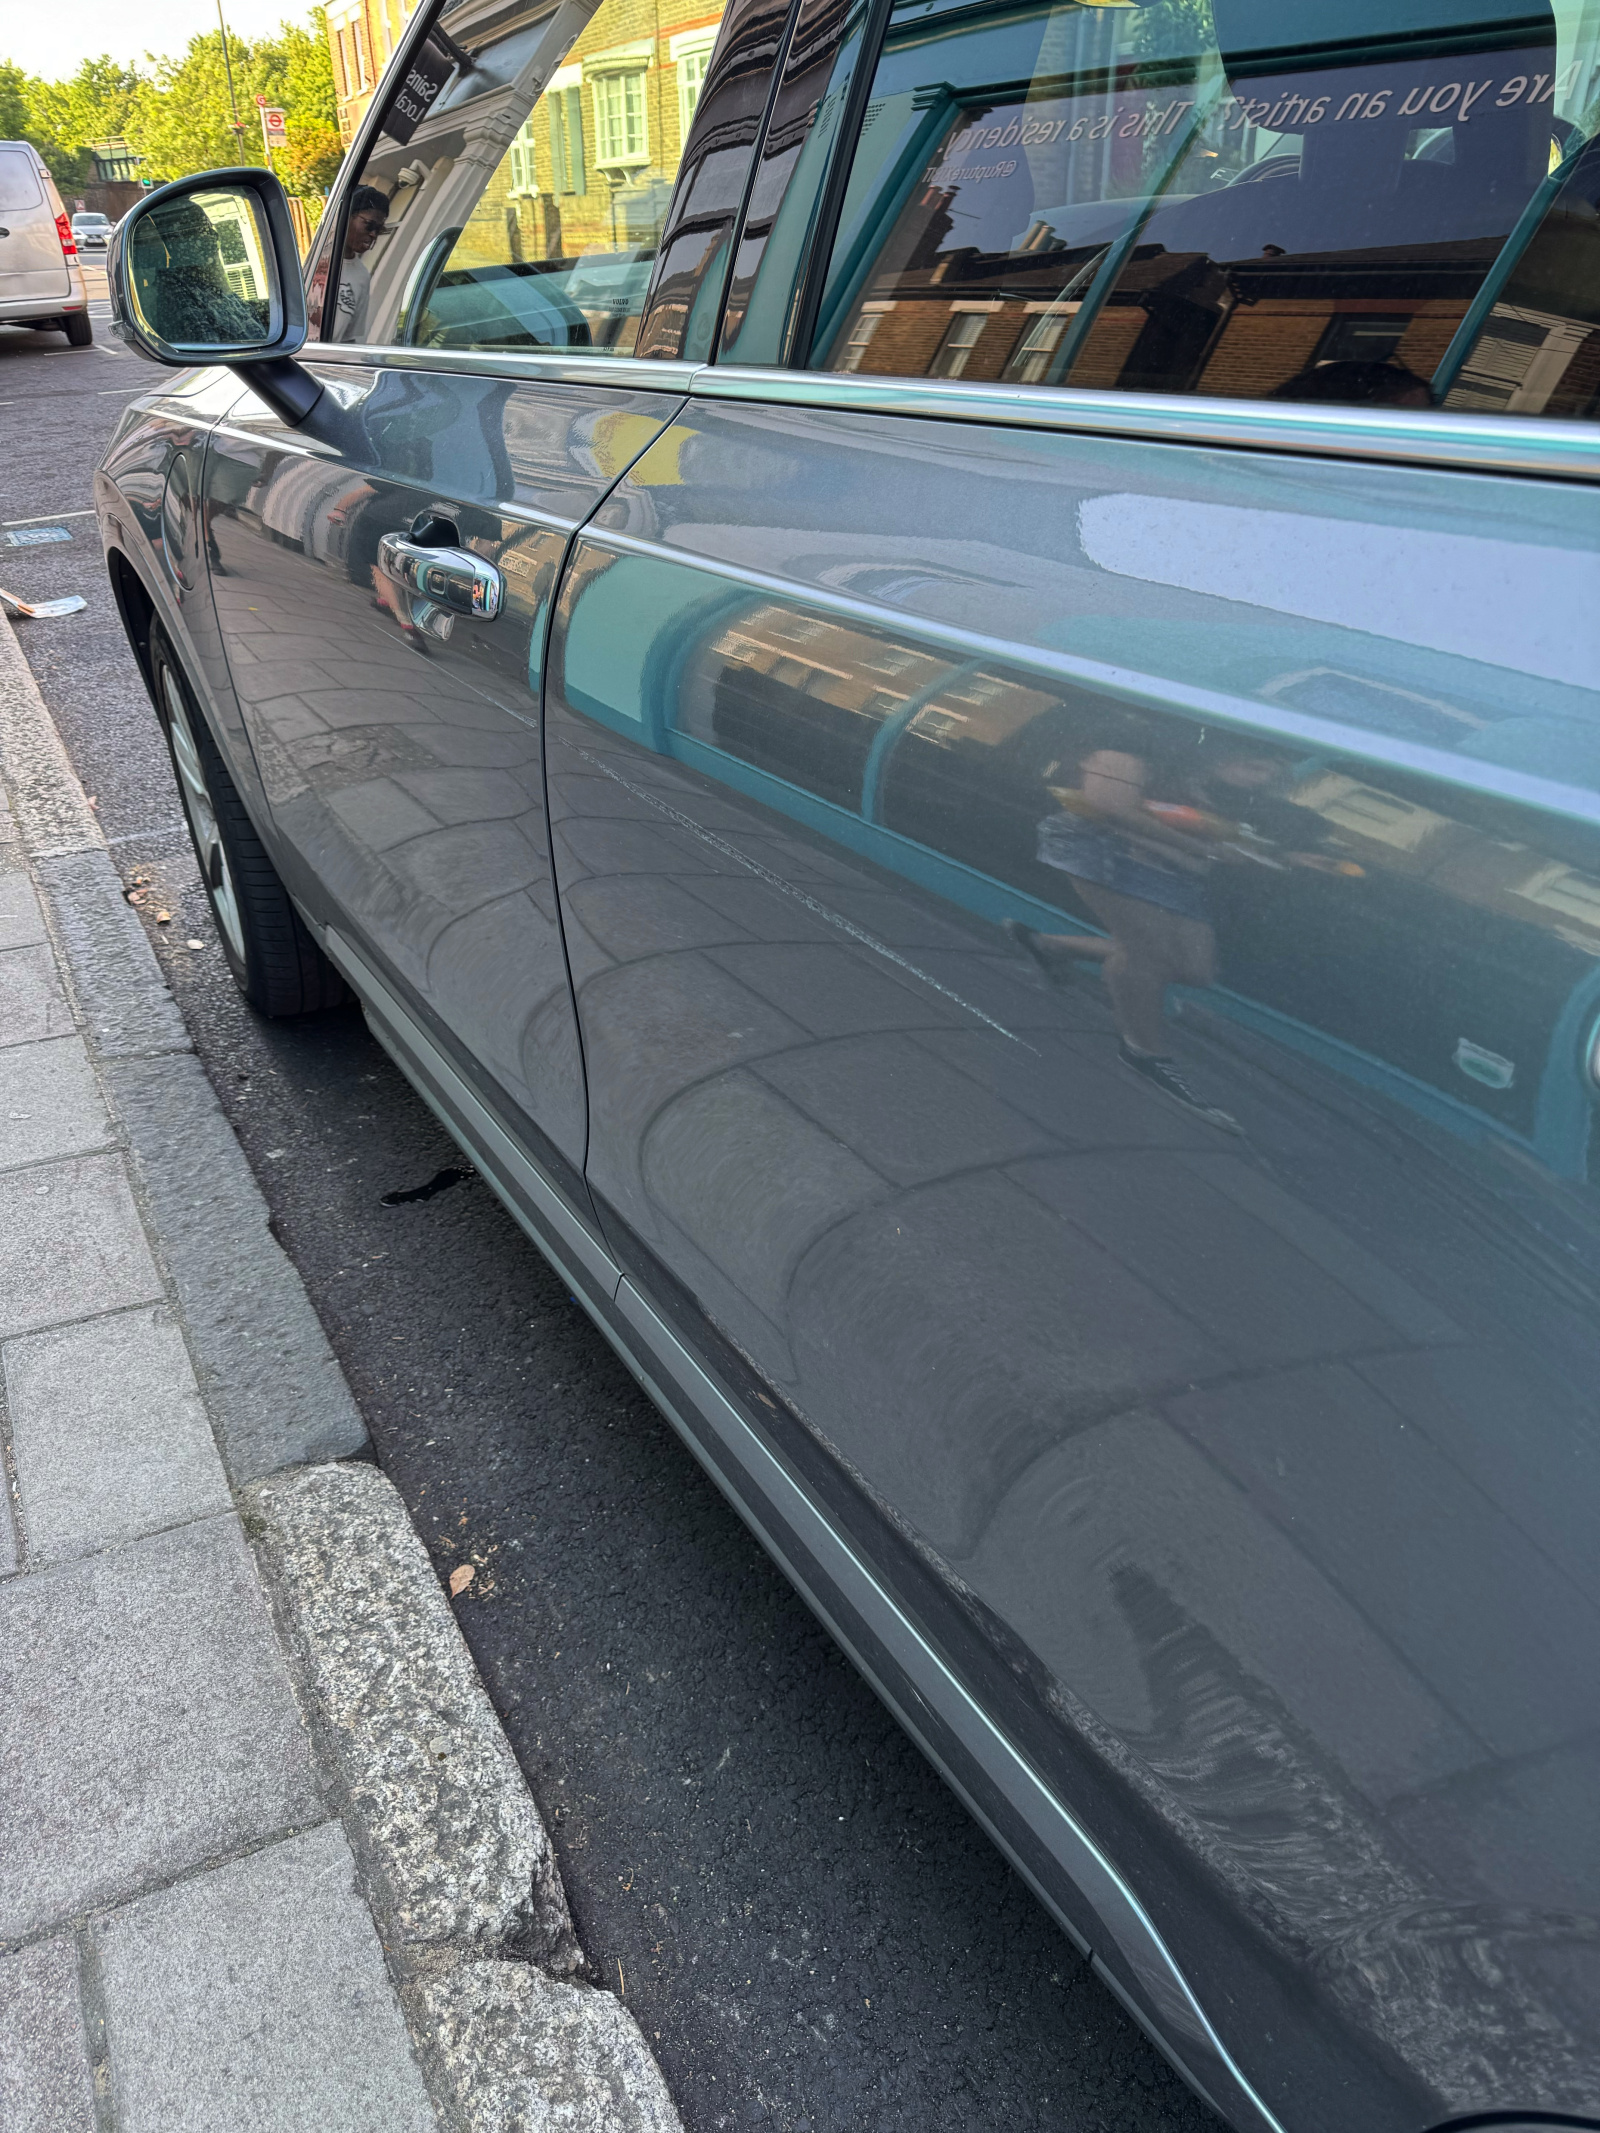
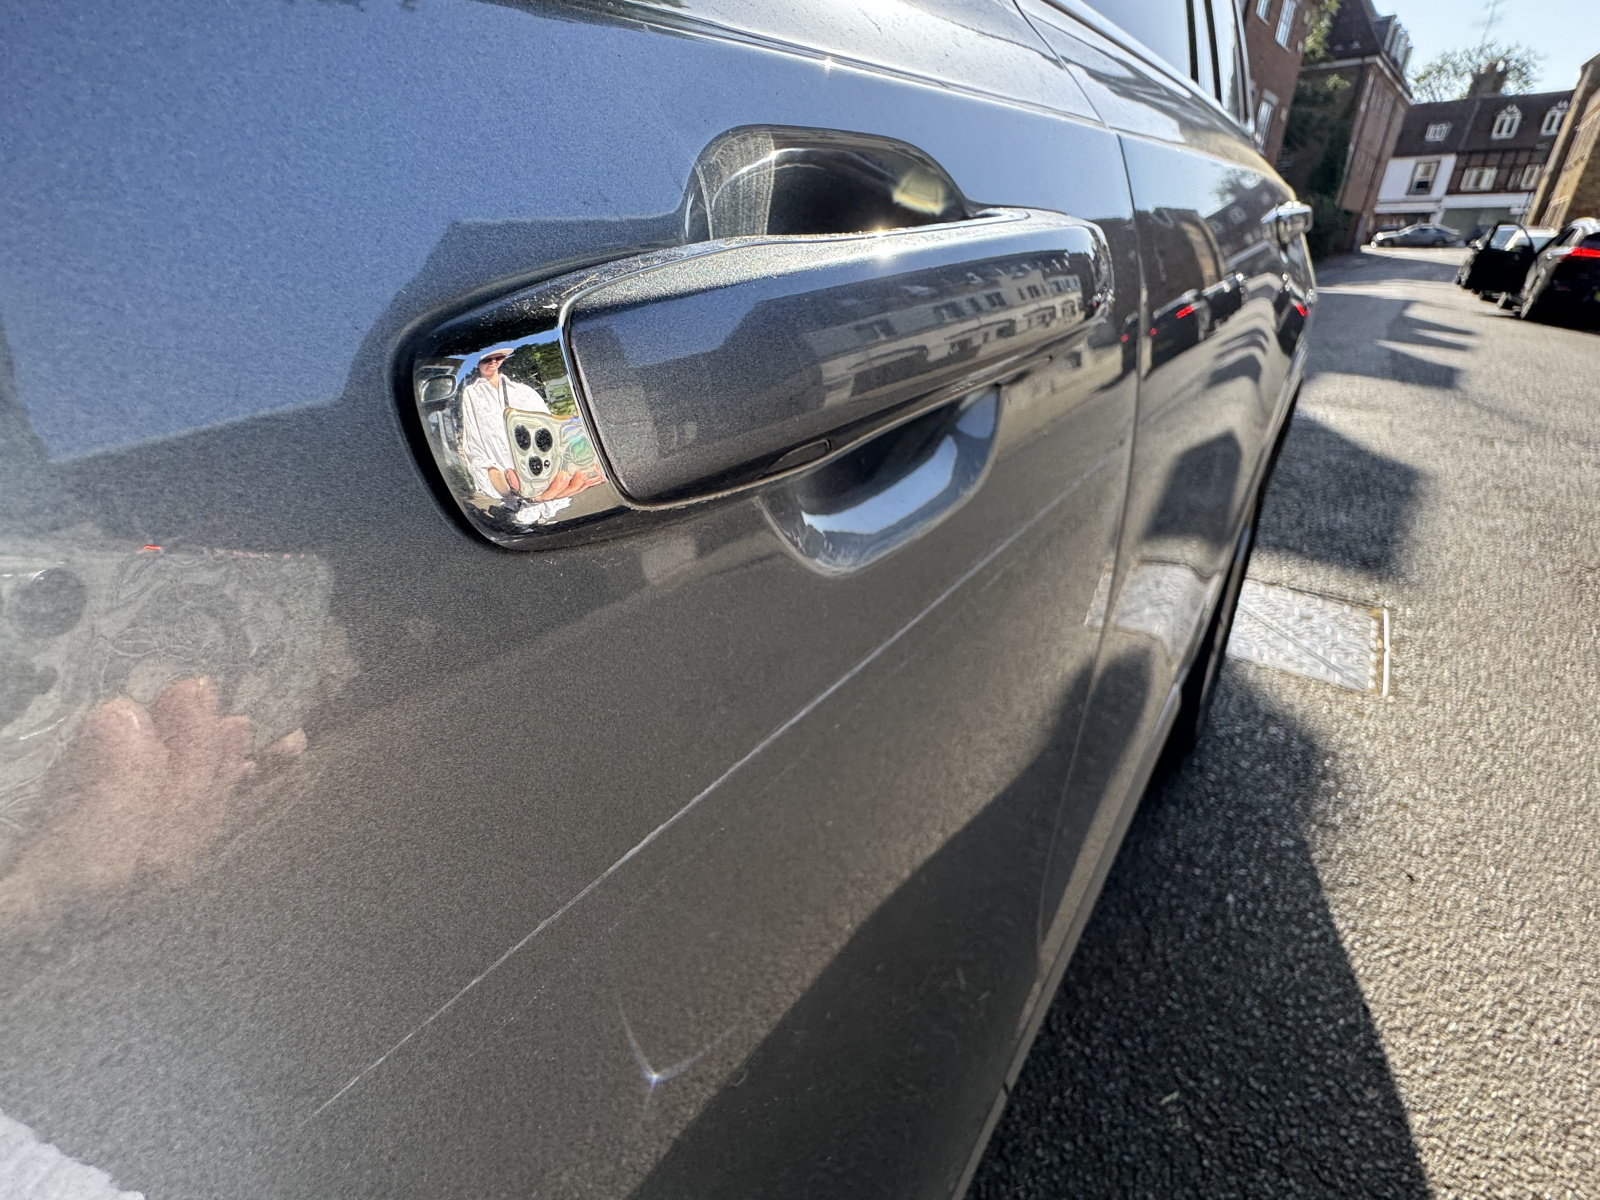
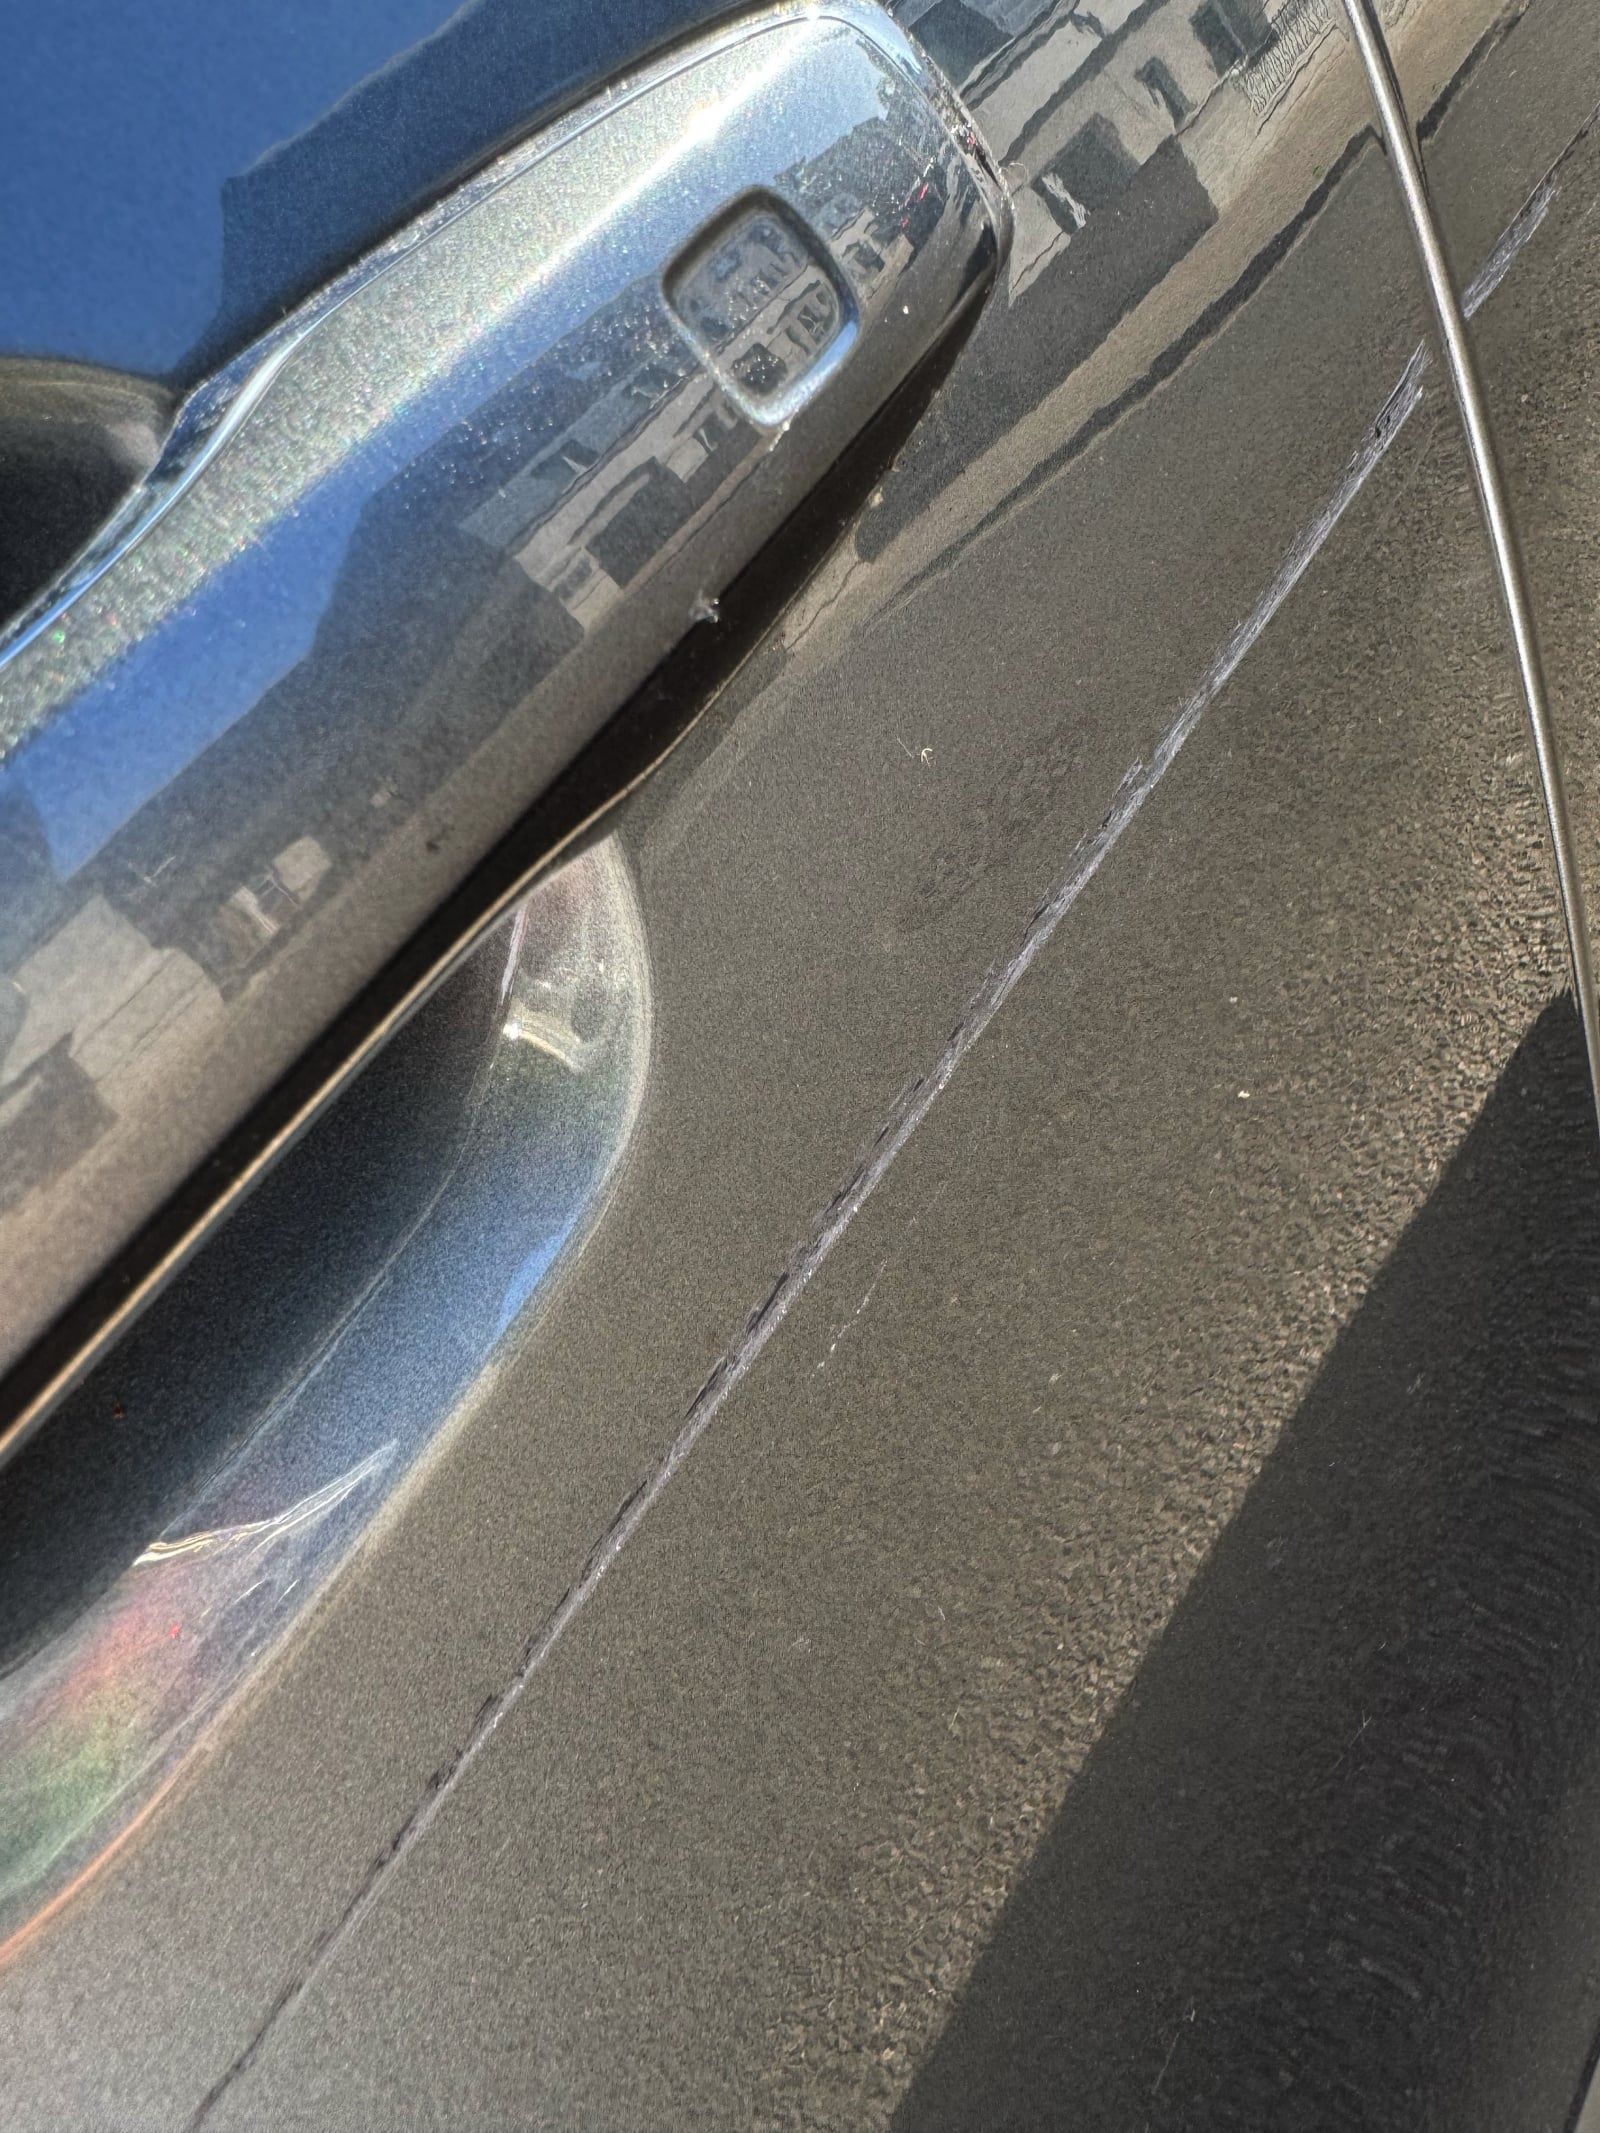
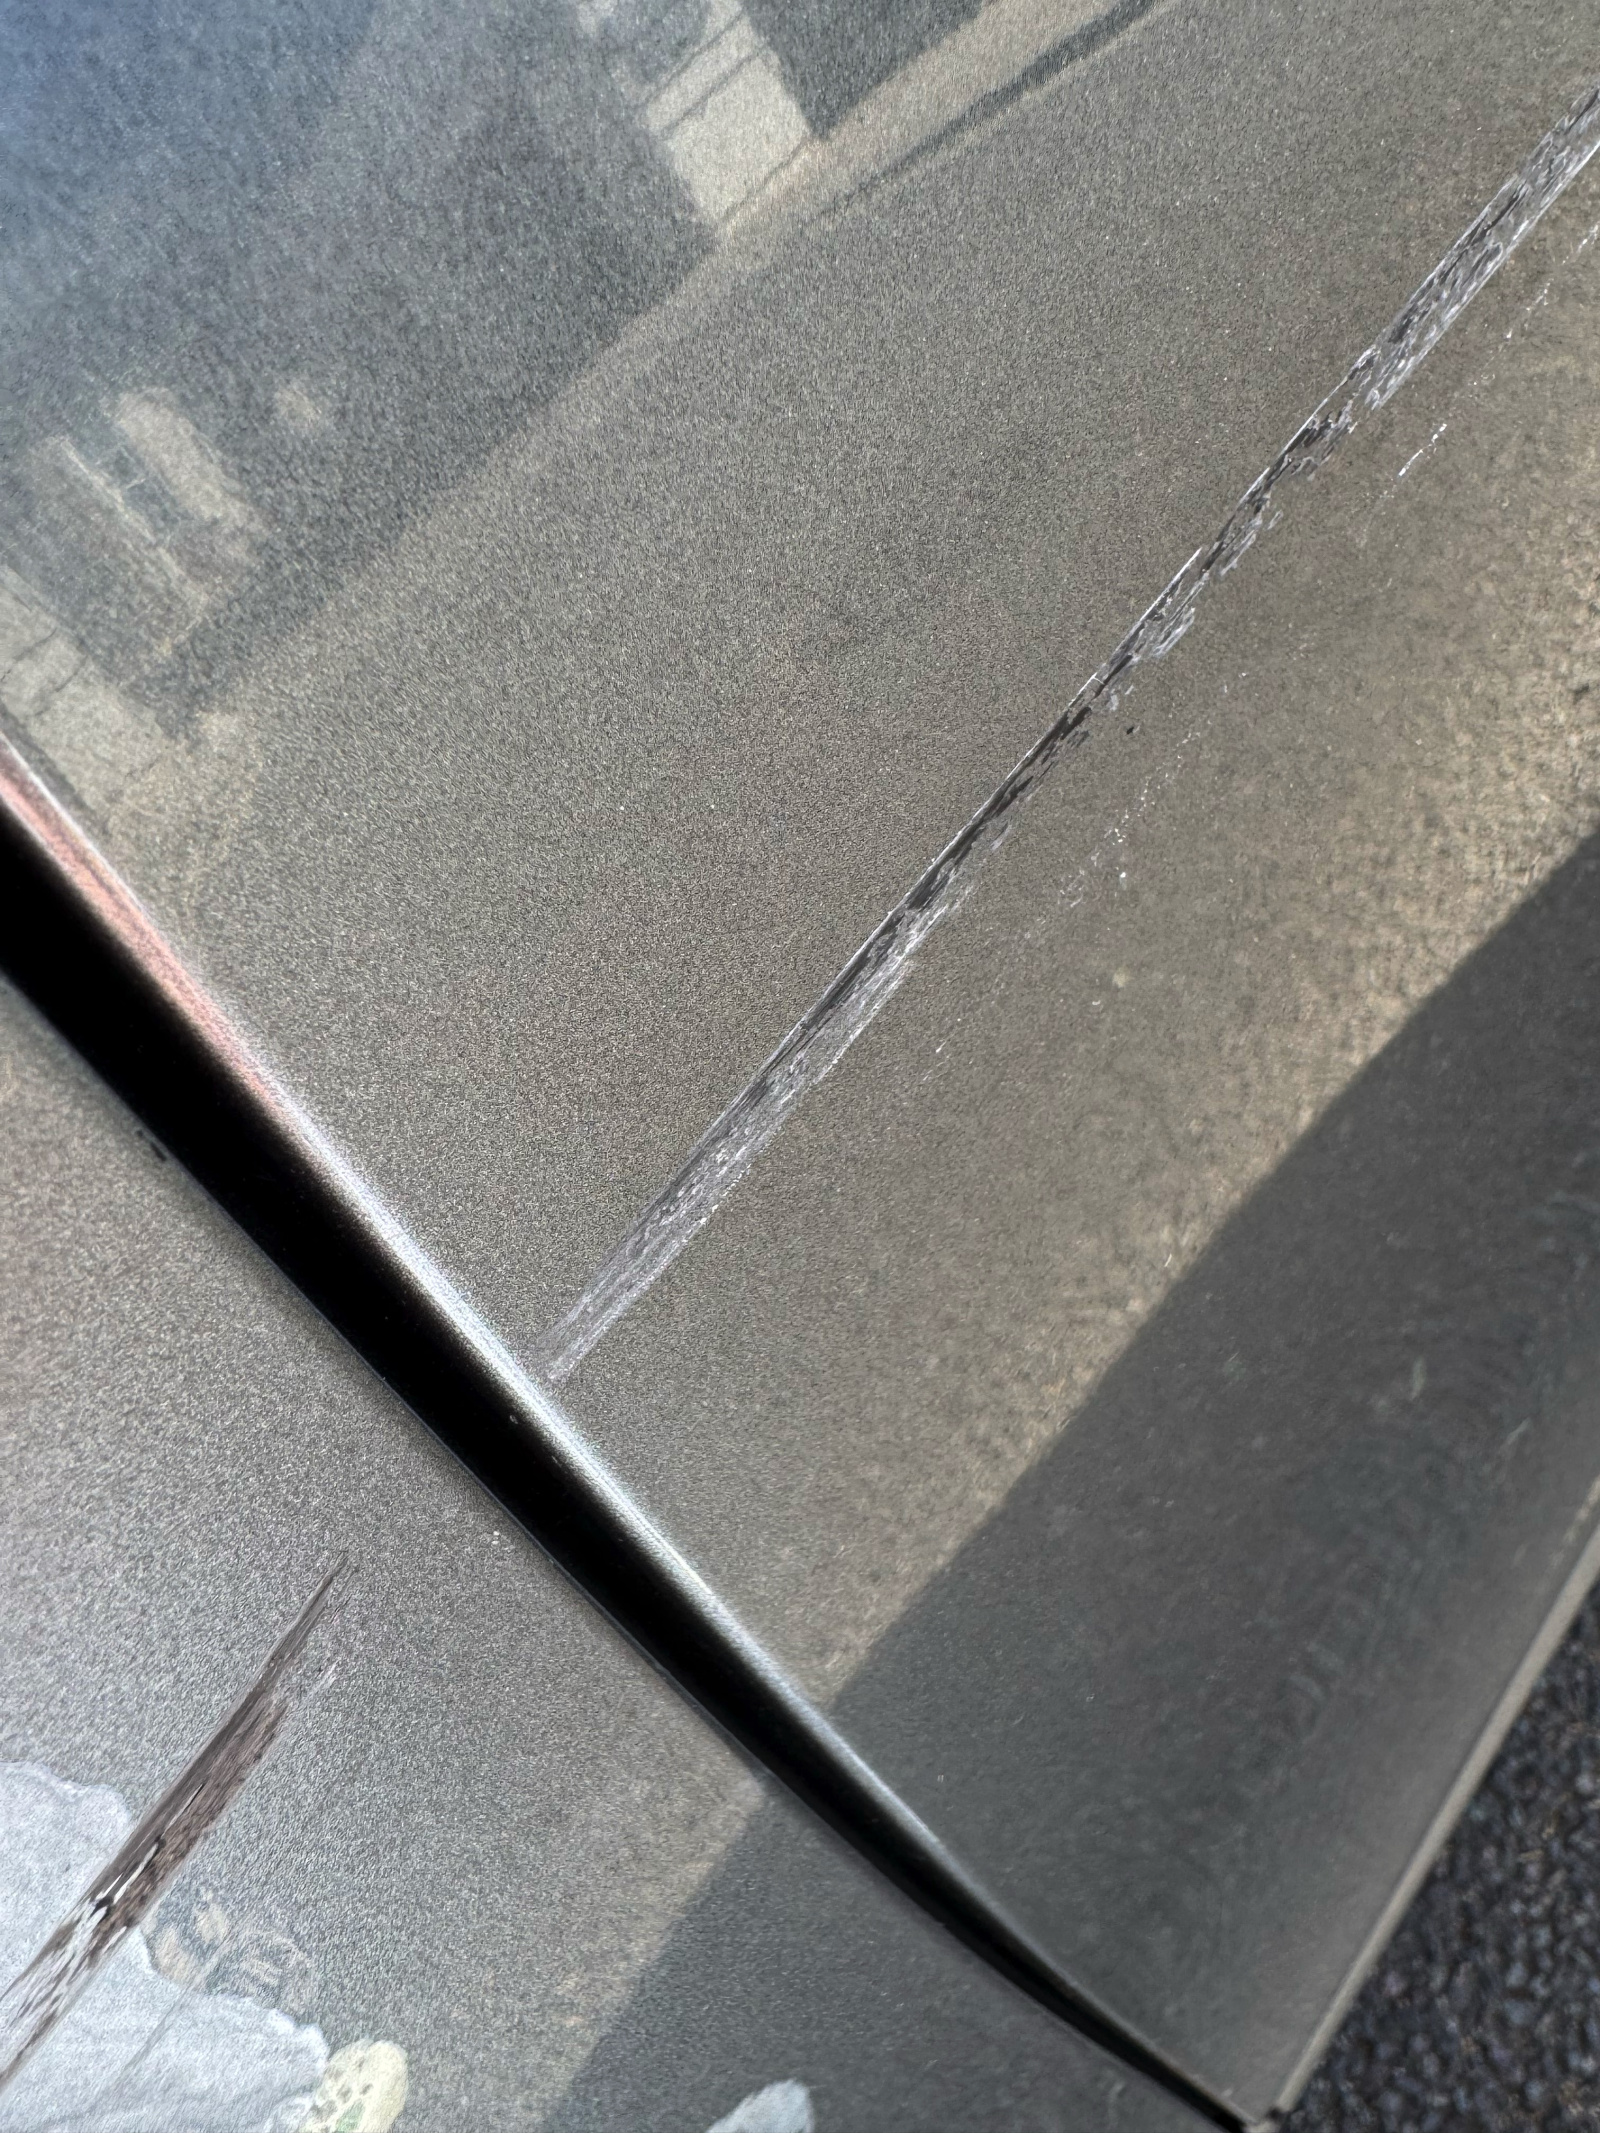
Yesterday a noticed a scratch in the paintwork down both passenger side doors.
Clearly someone scraped against the car when it was parked and drove off.
Very annoying.
I’m trying to decide whether to claim on the insurance. I have fully comprehensive, but here's why I'm hesitant:
In January, I slid on ice at a junction (going about 5mph) and slowly slid into the opposite pavement. There was a bend in the main underframe of the car and the insurance company wrote the car off.
They classed it as me at fault and I now have on my insurance record that I was responsible for writing off my vehicle. I complained that it was simply an icy road and it was not possible to control the car, so I was not at fault.
They said as there was no other vehicle involved it could only be classed as my fault.
Obviously when I got my new (used) car, insuring it cost a fortune because my record shows that last year I wrote off a vehicle and it was my fault.
Now that some little scrote has scraped either his scooter or whatever against my car, I don’t know whether to claim and have insurance pay, or whether I should just swallow the cost myself and keep my premiums low.
I can’t prove I didn’t cause this new damage to my car and I’m afraid I might end up with even higher premiums next year.
But on the other hand, I’ve paid for fully comprehensive insurance. So maybe I should claim?
Can anyone advise me?
Comments
-
I would pay for it myself and not get the insurance company involved …but that's just my opinion.
.."It's everybody's fault but mine...."1 -
Claim and will be another "fault" claim, as there is no one else to recover the costs from. On top of that you would have to pay the excess.
1 -
Much of that may well come out with a machine polish. Even if it doesn't, a repair bill is likely to be less than the loading on your next insurance quote, and those thereafter. Taking any excess into account, how to proceed should be a no-brainer.
Never believe anything until it's officially denied.
3 -
Will that polish / t-cut out with a bit of elbow grease?
0 -
Depends on the age of the car, but definitely pay for it myself if it was me.
OP, you are confusing 'at fault' with who has had to cough up. If your insurance has to pay for the write off or damage then it's an at fault claim no matter what or who caused the problem. At fault should be more like 'who's paying the bill'.
2 -
It would be well worth paying a visit to a local "smart repair" / "chips-away" type outfit - there are loads of them around. I've used our local one a couple of times and they've been brilliant, and much cheaper overall than going through insurance, paying excess and having your premiums increase. If you let them have a look, they'll be able to give you a quote, then you can make your mind up from there.
0 -
Went to a local bodyworks place. They took one look and said "this is not serious at all - can you leave it with us for an hour?".
My words on returning were "You are an effing magician - thank you so much".
£75 plus VAT.
So very glad I haven't even spoken to the insurance.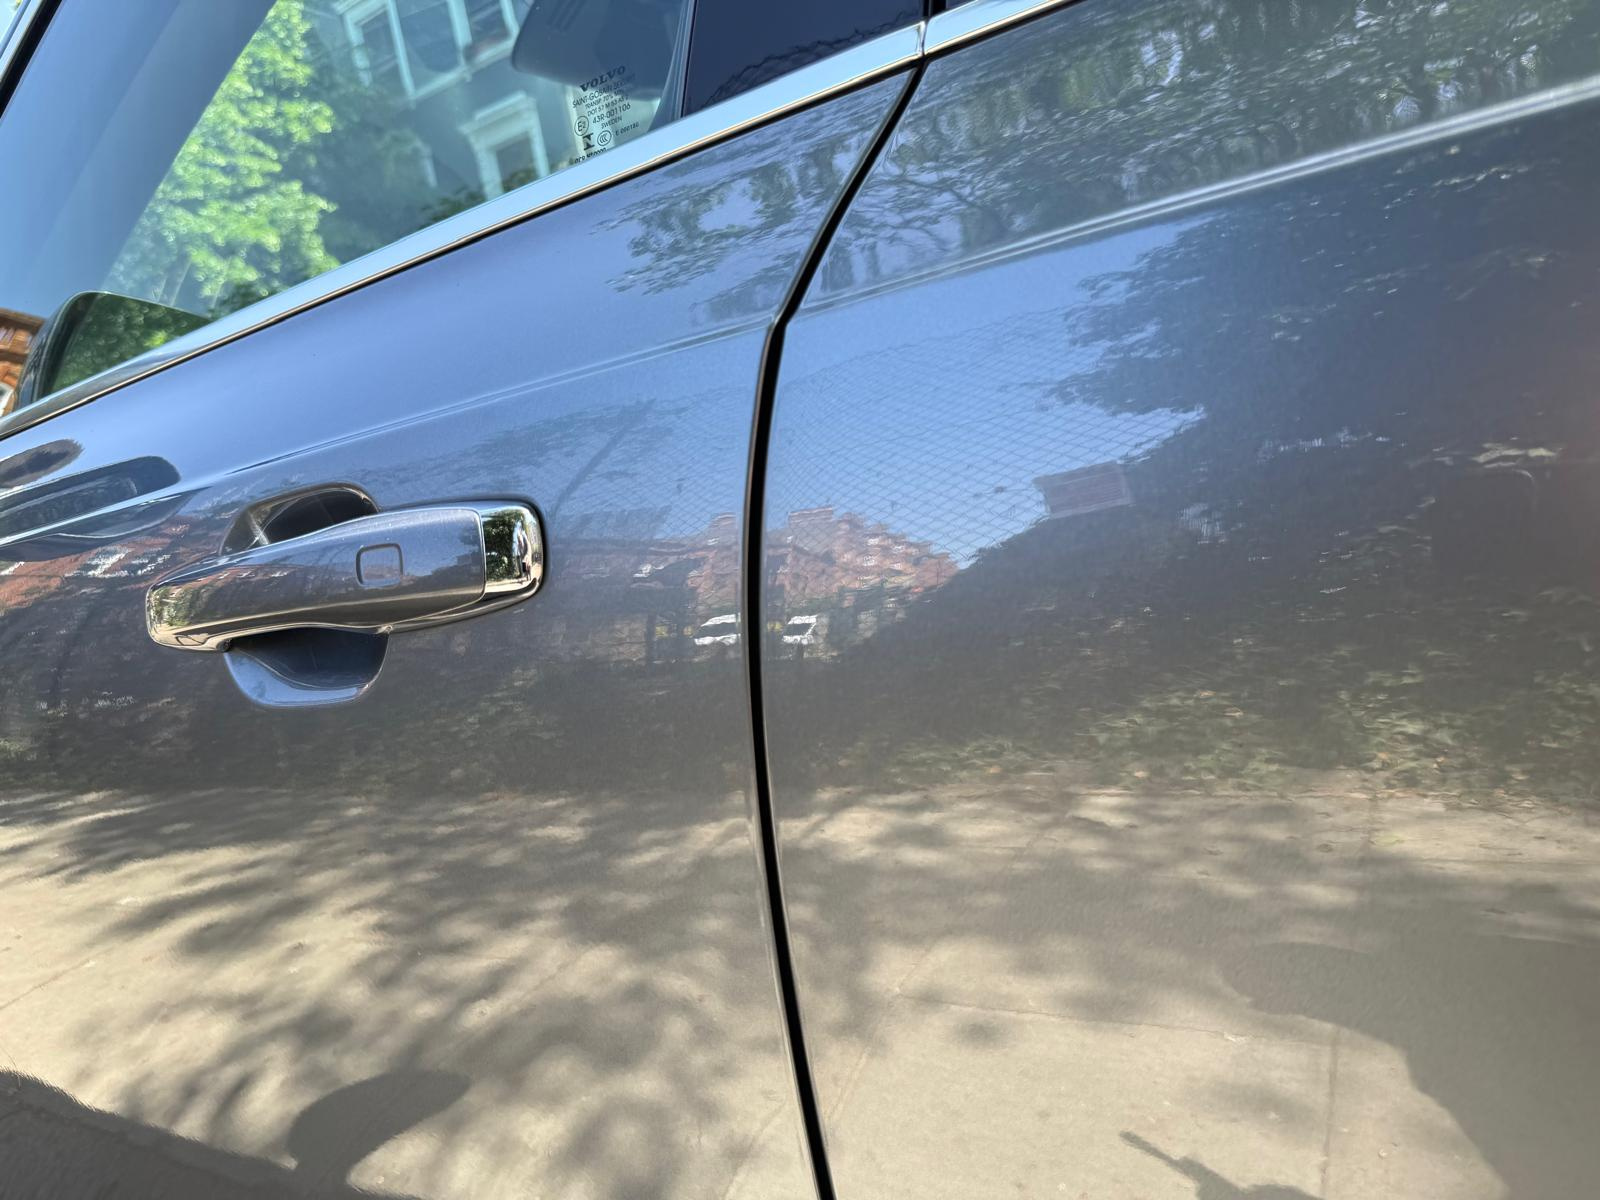 "Nobody told me being a grown-up would involve quite so much admin..."12
-
I’ve had a dinted bonnet and a scuffed alloy repaired by mobile repairers, both achieved undetectable repairs. Obviously there are limitations, but for minor damage they are incredibly good.
0 -
"At fault" doesn't mean that it was your fault, only that the insurance company couldn't get their money back off anyone.
"none fault" means that they got their money back from someone. They can only get their money back off the person who caused the damage, so in this context "non fault" actually means "someone else’s fault, and they paid for the damage".
Since you can't prove who did the damage, there is no-one for your insurance company to get their money from, so if you claim it will be "at fault" again.
Really insurers ought to use unambiguous terms rather than behaving like Lewis Carroll's Humpty Dumpty.
‘When I use a word,’ Humpty Dumpty said in rather a scornful tone, ‘it means just what I choose it to mean — neither more nor less.’ Through The Looking Glass by Lewis Carroll.
I want to go back to The Olden Days, when every single thing that I can think of was better.....
(except air quality and Medical Science )0
-
It is the traditional definition but some insurers do deviate from it, several insurers do differently for things like vandalism, hit and run etc
0







Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.6K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards