We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Cash buffer dilemma




afternoon all ,
#i have often read that on retirement you should have a cash buffer within your "portfolio" so can ride out any market crash when you may need to access cash instead for say, 2 years.
My query is as follows..
My wife has just retired her overall pot came to £400k (albeit high share prices at moment), it is a mix of SIPP, S+S ISA, and Cash (most not in ISAs). The cash is about £120k and our plan was to drip that into s+s isa the next couple year , but leave abuffer of about £60k. We are using the 4% rule, so taking about £15-£`16k pa and increase with inflation then reduce to 3% when SP kicks in.
My "pot" is a mix of DB (which will provide me with over half of my pension), and then DC pension and S+S ISA. I hope to retire in just under 2 year , I have NO cash in my portfolio and is slight concern that if markets crashed it could impact when i retire (and i really want to be gone in 2 year). My annual pension (all combined) will likely be £45-50k pa (the DB will provide £32k)
In this predicament would you seek to concentrate on building up a cash ISA and stop paying in monthly into S+S ISA ? or does that seem daft when my wife has so much cash in her own portfolio ?
any advice is appreciated
Mick
Comments
-
I can't say what would work best for you and your wife, but I've got a gilt ladder in my DC pot to cover the first few years of my retirement (planned to commence next year).
Gilts are as good as cash, IMHO.
Your wife could have £60k in a cash ISA, or 4x £15k gilts in a ladder in a SSISA or SIPP.
You could do something similar.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Ecoflow Stream, Best kettle :-)
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.0 -
how do i get a gilt ladder ? s+s isa is with vanguard
0 -
IMHO - not sure it really matters where the cash is as long as you can get hold of it when you need it. As for the amount, were I your position, I'd calculate my annual spend and multiply it by at least 5 if you hold just cash and equities. You really do not want to be drawing from your equites pot in a crash. However, as others more enlightened than me may point out, markets have taken far longer than 5 years to recover in the past. It really a case of finding a multiple which suits your risk, but bear in mind inflation may well eat away the cash value if you hold too much and you miss out on any potential equity growth for that cash amount.
I should point out that I also hold bonds, which lessens my reliance on equities. Diversification is the name of the game at this stage in life for me - almost retired. Indeed, my bond portfolio covers my basic spend, so although I also have cash reserves, I am only reliant on my equity portfolio for bunce - holidays, new car, roof falling in, civil war - that sort of thing. My cash reserve only therefore covers what I may drawdown (on average) from the equities bunce pot every year so I can afford a multiple of 10 - which hopefully will cover most eventualities.
1 -
With a DB pension you don't really need a sizable cash buffer. So I would probably just have the usual emergency/cash flow amount for daily living, that might be 6 months to a years cash that you top up every quarter. Anyway you have your spouse's cash buffer as well.
And so we beat on, boats against the current, borne back ceaselessly into the past.0 -
Maybe not at Vanguard. Plenty of platforms will let you buy gilts eg AJBell, II, HL and SWSD (ex IWeb).
0 -
thanks all
food for thought , have a good weekend
0 -
@Veloflyer I was interested to read your 5 year cash buffer suggestion, I have kinda settled on 3 years. It is of course about risk tollerance and any other retirement income provisions, DB, SP, working SO, rental etc. My finger in the air calculations are based upon me losing half my investment income in times of stress and it taking 4 years to recover. Covid dropped 50% but was recovered in ~2 years. GFC took around 4 years to come back. 1929 depression and US collapse might have been 10 years and only improved because of the war but I think that's old news.
If I had a 3 year cash pot and my investment income fell 50% I'd draw half the required income from the cash buffer in the first and 2nd years leaving 2 whole years in the pot and if, by then, slight recovery had started I'd take less than half a year of income each following year giving me >4 more years before I started eating my seed. State pension is a handy backstop but as early retirement beckons that's further away in my planning
1 -
The question isn't whether or not you have a cash (or anything else) buffer, but whether you can ride out a market crash without doing long term damage to your future wealth. Looks at first glance like you probably can.
In the long term the real enemy is inflation and that is why you need to remain invested largely in equities.
🐻 A little FIRE lights the cigar0 -
how do i get a gilt ladder ? s+s isa is with vanguard
As above, you'd need to do it with a differnt provider as Vanguard doesn't let you buy individual gilts.
There's a handy tool at https://lategenxer.streamlit.app/Gilt_Ladder that helps you put a gilt ladder together.
For example, let's imagine you wanted £15k pa in real terms (inflating by RPI each year) starting on the 1st of May 2028, with a 20% marginal income tax rate and 2% interest on cash balances.
The tool suggests you buy these quantities of these index-linked gilts:
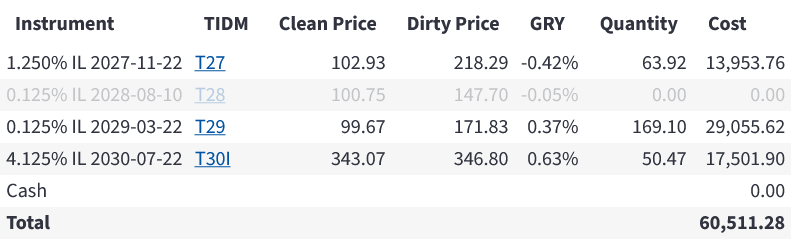
The cost to you would be £60511.28, and would ensure you have the cash available to take £15k pa (inflated by RPI) each 1st May for four years.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Ecoflow Stream, Best kettle :-)
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.4 -
In case you wonder how buying 3 gilts which mature in different months can give you 4 years of pay outs at the same time in each of 4 years the tool has a cashflow page (you need to click on a tab to get there) showing the receipts and the pay outs for the ladder. It is well worth playing around with it before you actually go and buy anything.
2








Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards