We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Bank wanting zero balance on reward credit card
Comments
-
That's what I'd do. Keep using the points but the card shows as £0 balance every day.
Check with the mortgage provider first if that's sufficient or if they want it to be completely unused.0 -
Odd as September last year I was given a TSB mortgage where I had 18000+ on three zero percent credit cards and just had to show available savings in excess of that amount after explaining i was stoozing the balances.
0 -
The world of mortgages and the process of buying and selling houses is very strange, in my opinion. I recently went through the process of a mortgage application and was asked about my credit cards. I explained that one was paid off by direct debit every month but that the other was a 0% card so I didn't usually clear the balance. . I was asked if I would clear the balance and I agreed because it wasn't a large amount but I can see the why the OP is not happy about it.
0 -
There is almost certainly something else in your credit file which is causing some alarms to go off with the lender, and they are as a result being a little overly cautious about the credit card.
Allowing it's only a small balance though, by far the easiest way of dealing with this is as has been suggested - just pay off the transactions as you make them. If you lender DOES then ask for proof of a zero balance, you can provide that.
🎉 MORTGAGE FREE (First time!) 30/09/2016 🎉 And now we go again…New mortgage taken 01/09/23 🏡
Balance as at 01/09/23 = £115,000.00 Balance as at 31/12/23 = £112,000.00
Balance as at 31/08/24 = £105,400.00 Balance as at 31/12/24 = £102,500.00
£100k barrier broken 1/4/25
Balance as at 31/08/25 = £ 95,450.00. Balance as at 31/12/25 = £ 91,100.00
SOA CALCULATOR (for DFW newbies): SOA Calculatorshe/her0 -
Hi all, thanks for the advice and kind supportive words. I know it sounds quite strict and I firmly believe it is. Just a little detail I forgot to include, I'm buying on a shared ownership scheme at 50% on my own, it's a 3 bed property (I work from home), in a not so cheap area of London but I had some help from parents and currently been dating long term, so likely to have partner move in, in a few months and we can buy the additional 50% at a later stage. So whilst the mortgage is small, the bank has the rent to consider too, I guess.
The good news is that the broker has told me that my affordability was fairly strong, so they have gone back to the lender and asked to escalate the case to a senior underwriter as they think it is just a case of computer says no at the moment.
0 -
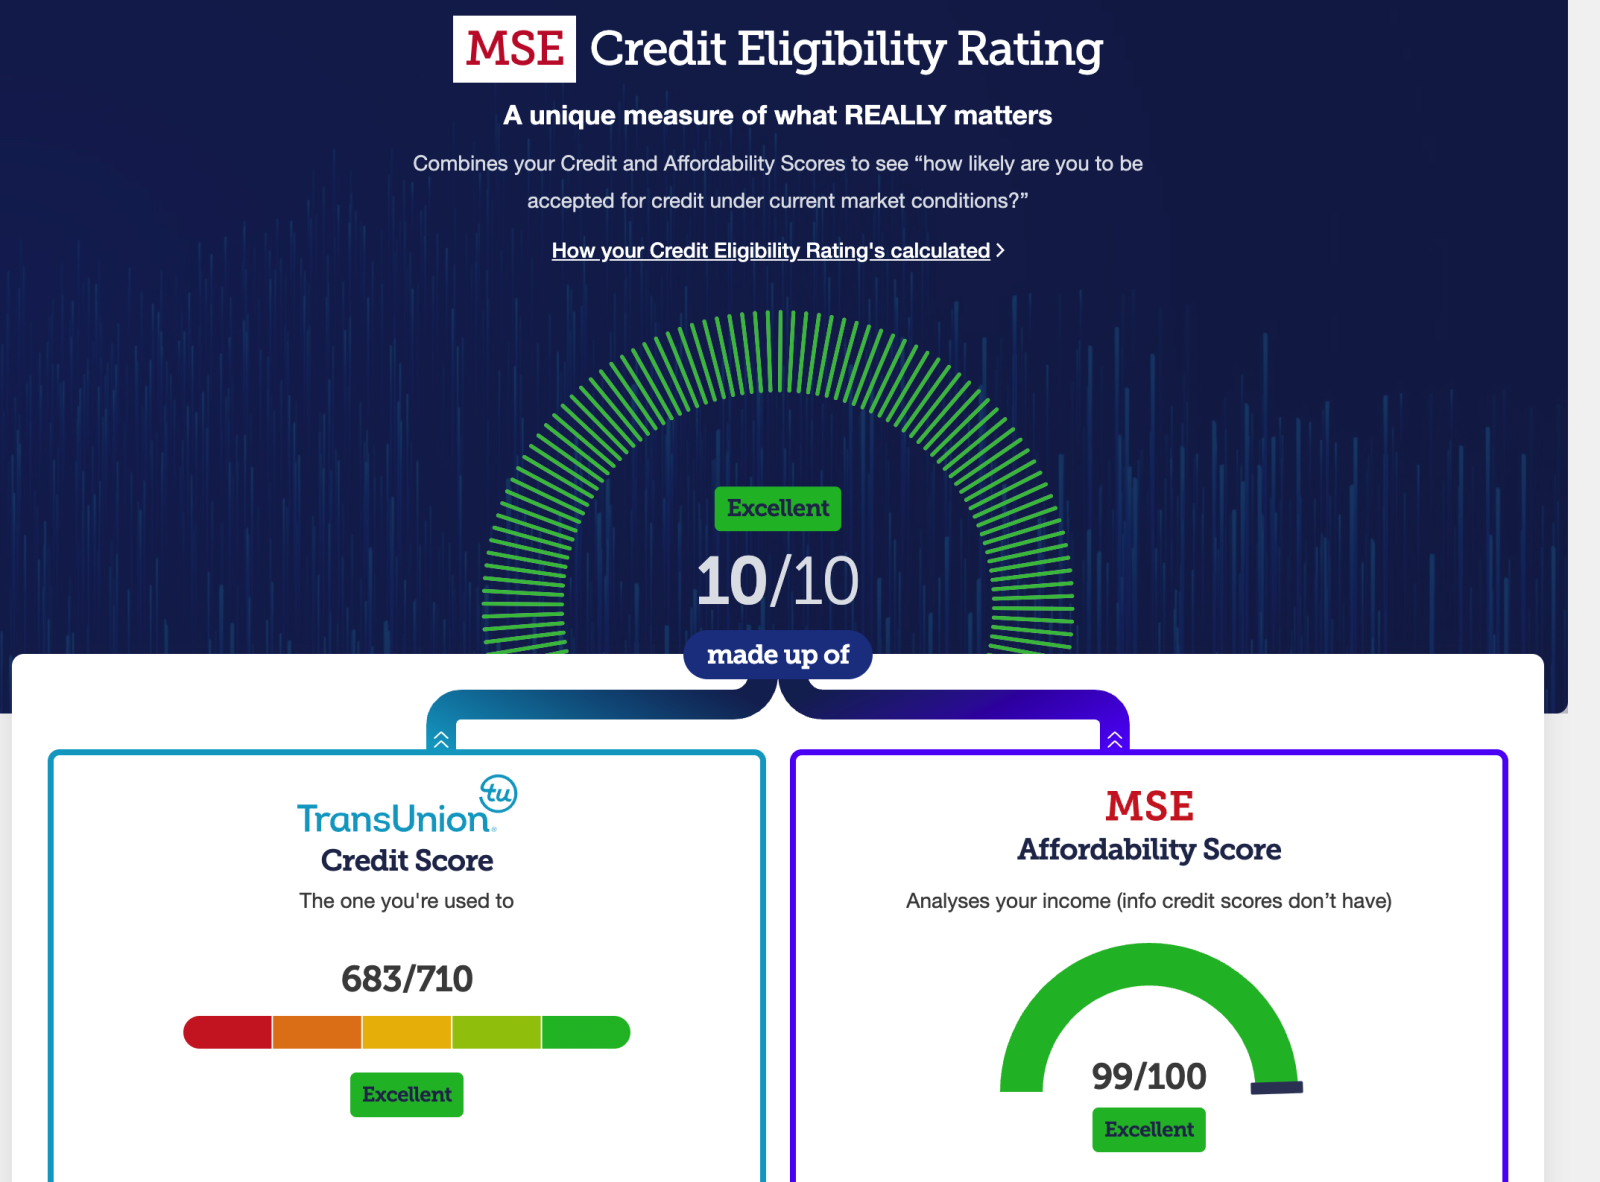
BTW, I appreciate all your advice saying to clear the cards and show the £0 balance. The simple explanation is that I did this in March and sent them the statements then but they came back asking for the April statements. I do not have any negative markers or anything, below is my credit eligibility rating on MSE Credit Club:
 0
-
You can ignore your credit score, it's just a made up number. Lenders have their own criteria and score your personal situation against that.
1 -
Which lender is this? Some are notoriously strict about any credit card balances during underwriting, even if you pay in full monthly. Have you explained to them that these are transactor accounts with a perfect payment history? You might need to time your application so statements generate with zero balances, or consider switching to a more flexible lender who understands reward card usage patterns.
0 -
Credit scores are weird. Mine is low because I don’t owe anyone money. Apparently, the algorithm wants to see responsible borrowing, with payments on time. No borrowing at all doesn’t provide the same comfort.
You’d think that I would not be bothered, as I’m unlikely to need a loan at my stage in life. But, a new phone contract, for example, involves the seller checking my credit score.
Good luck with the mortgage application!
No reliance should be placed on the above! Absolutely none, do you hear?0 -
But, a new phone contract, for example, involves the seller checking my credit score.
It's a minor but important (and common) mistake, the lender does not check your 'credit score(s)', they are numbers derived by the credit reference agencies to keep you (and only you, no-one else sees them) interested in bettering your number by taking more credit products, on which the agencies earn commission.
A lender will examine your credit report(s), a factual breakdown of your current debt, credit limits and agreements, together with other information about your income etc and make their own decision based on their own lending criteria.
2















Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.6K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards