We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
About to begin a DMP with £53k of debt.
Comments
-
Hi everyone,
I haven't posted a while since starting my thread but I haven't really had any issues to report. I am managing my own DMP and I have set up standing orders to all my creditors with an amount I can afford to pay. I have managed to do this without talking to them and doing my budget with them as I don't want to talk to anyone over the phone. I hate talking to anyone on the phone, let alone debt collectors! Anyway, I am paying every creditor an amount I can afford, and whilst its probably not enough in their eyes, they are getting money from em every month.
In the meantime, I have been helping my partner manage his own DMP too. So far, we have done the same and set up standing orders using the details they provide and have avoided talking to them. However, there is one that we are having issues with. He has an unsecured loan with TSB for £18000. He defaulted, it went to Wescot and he set up a standing order for £100 a month. They have been hounding us to get in touch and then sent this letter today (see below image). Is this just scaremongering? They are getting £100 from him (albeit, having not spoken to him) and this hasn't been acknowledged in all the communication we are getting from them. We check every month to ensure the payments have been made. Any advice would be appreciated.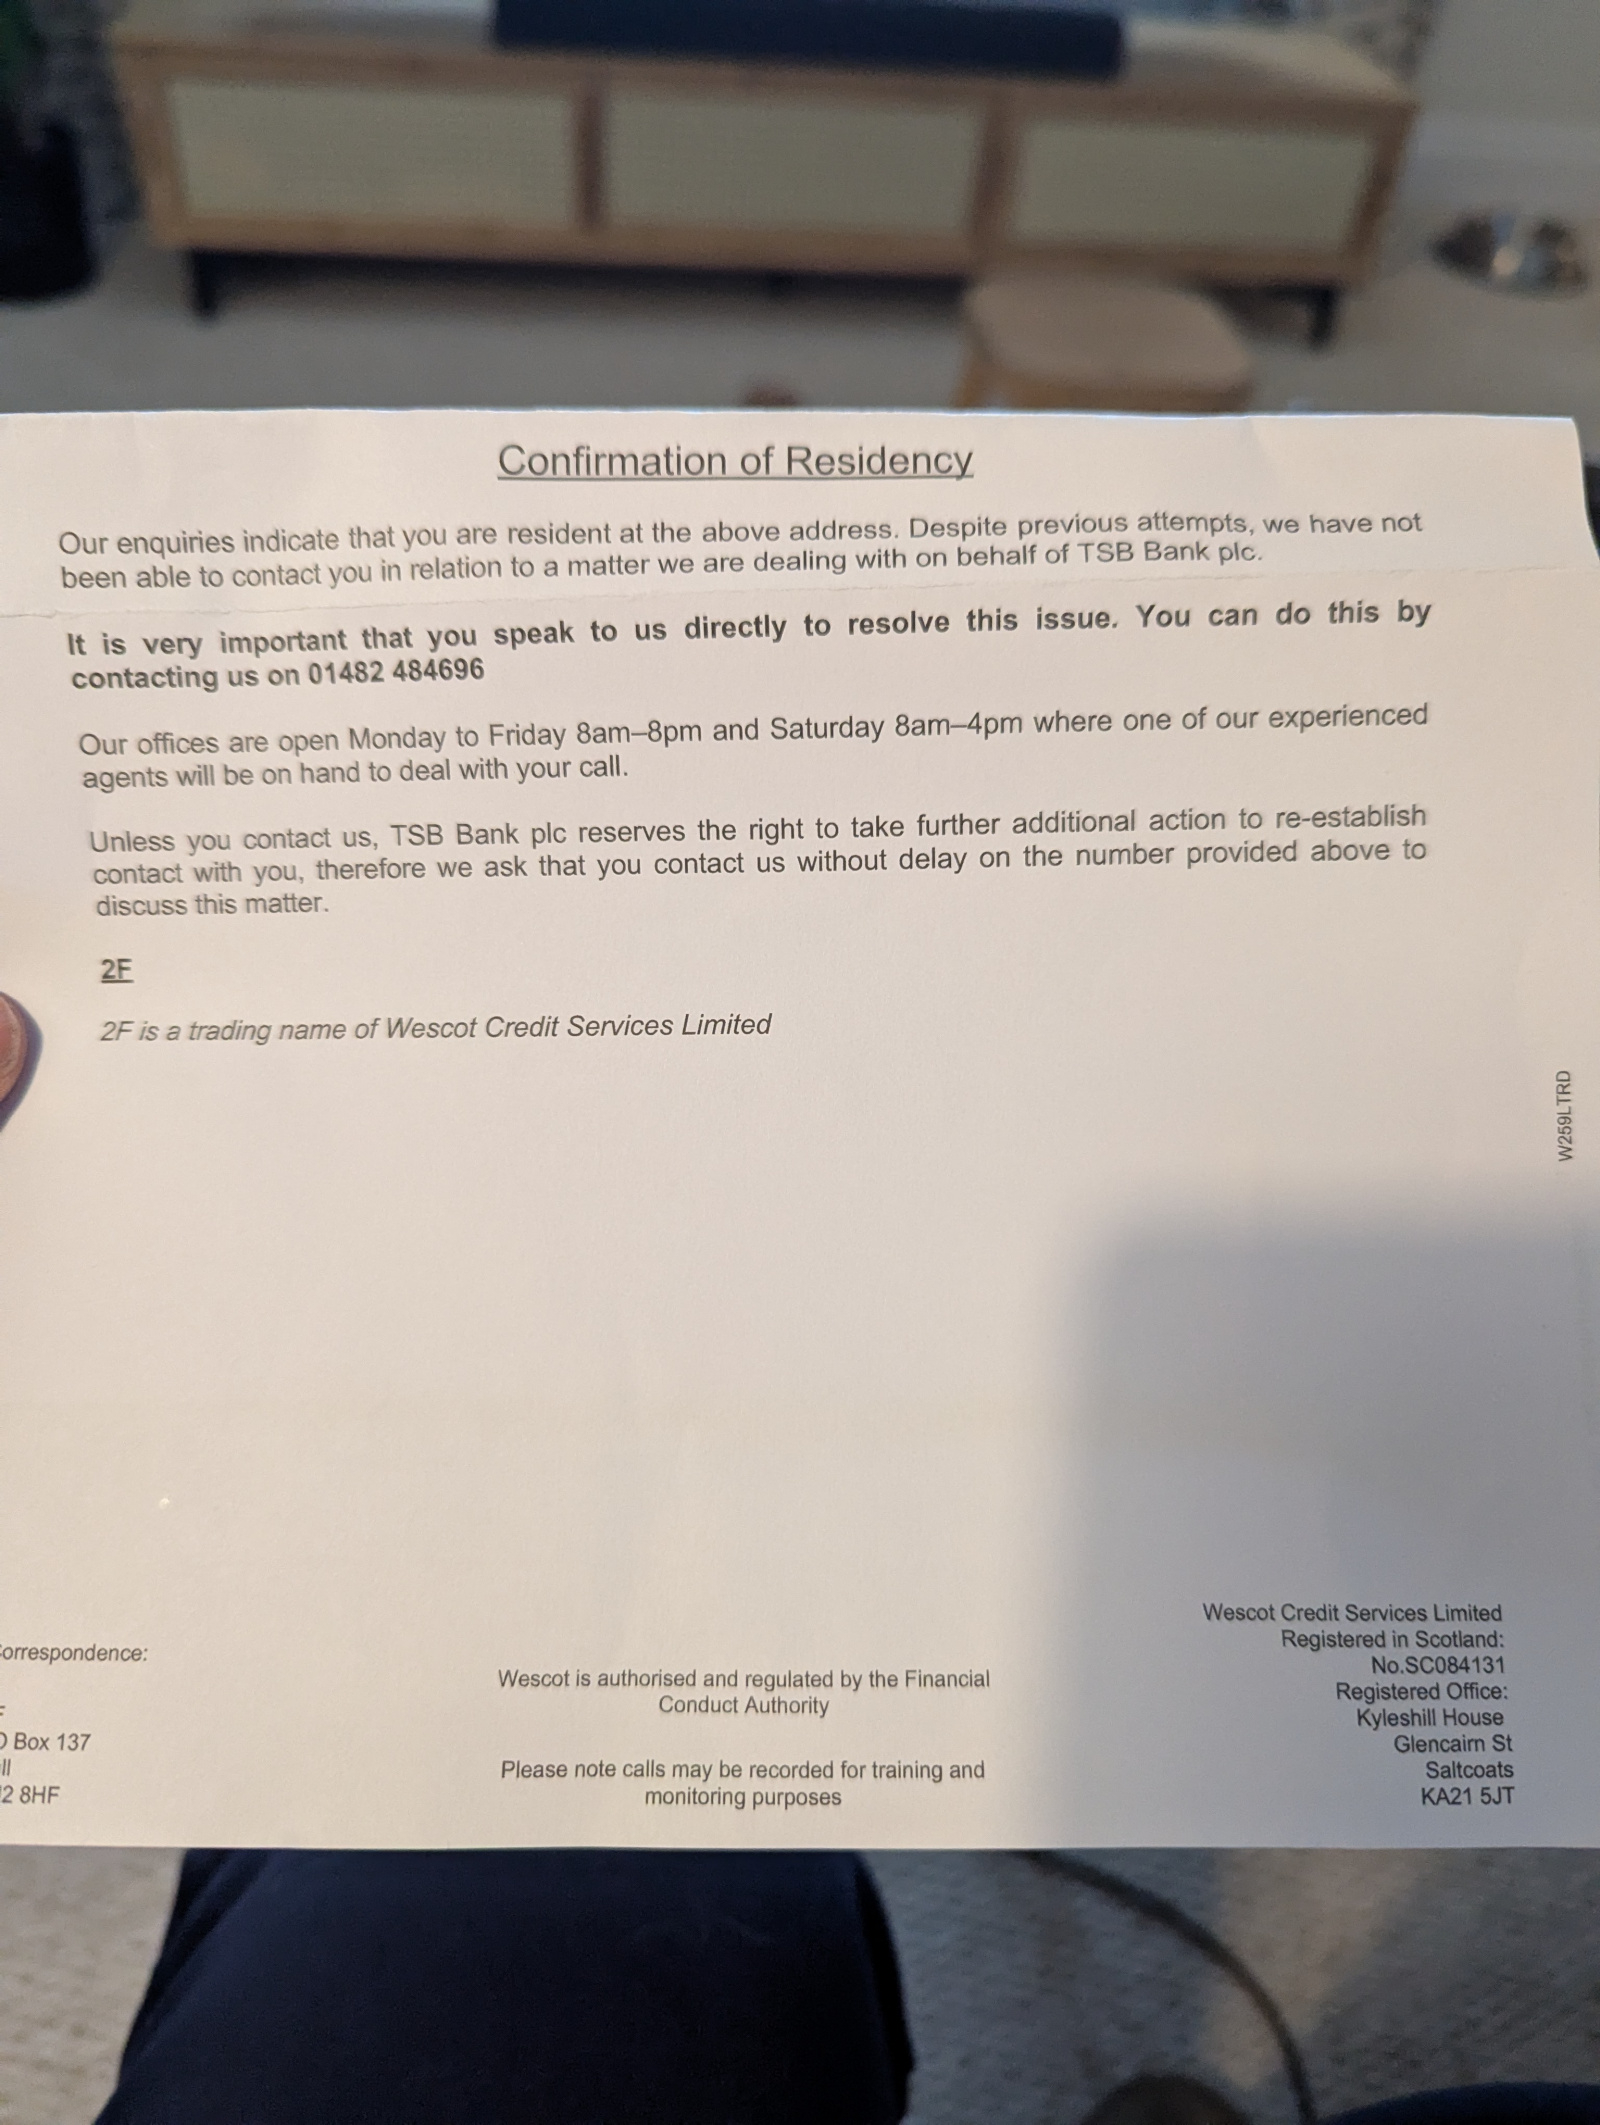 0
-
You can always tell all creditors that you are no willing to speak on the telephone and that any contact with you should in writing - you can even stipulate only via post if you wish! I would consider writing back to them simply saying that they should take your letter as confirmation that they are no longer welcome to contact you via the telephone and that they should remove any phone numbers they have for you from their records. Going forwards they should only contact you in writing/via hard copy in the post (whichever of those options suits) and that any further contacts via phone will be treated as harassment. Just bear in mind if you say they can only contact you via email, there are some things which they are required to send hard copy, so you won't see a complete stop to all hard copy correspondence.🎉 MORTGAGE FREE (First time!) 30/09/2016 🎉 And now we go again…New mortgage taken 01/09/23 🏡
Balance as at 01/09/23 = £115,000.00 Balance as at 31/12/23 = £112,000.00
Balance as at 31/08/24 = £105,400.00 Balance as at 31/12/24 = £102,500.00
£100k barrier broken 1/4/25
Balance as at 31/08/25 = £ 95,450.00. Balance as at 31/12/25 = £ 91,100.00
SOA CALCULATOR (for DFW newbies): SOA Calculatorshe/her1 -
Thanks very much. I have sent them an email as you suggested and to confirm residency. Lets see what they say!0
-
Hi everyone,
Nothing hugely exciting to report. I am still making very small payments to all the collection agencies and my husband is doing the same with his having received defaults from them all.
We have received several settlement offers but whilst some of them have been very 'generous', they are still way more than we can afford to pay so we have not followed through with them. We have not missed any payments and occasionally have periods where we get hassled to 'review our payment plan' to make sure its affordable (it is, so leave us alone!).
I am now considering making CCA requests and have read up on the advice on debt camel - is it too early in my DMP to request these?
I am also considering affordability complaints but only after I have had responses regarding the CCA's. I still have the underlying concern that some may take legal action as the payments we are making will mean the DMP's will take years to paid off.
Thanks in advance. This forum is incredible.
0 -
Asking for the CCA normally works best after the debt has been sold and has been with the purchaser for a while, however the government are planning to water down consumer protection when it comes to asking for it so I'd suggest doing it sooner rather than later.
CCJs aren't very common if you have engaged and are paying something. If you do get one then the court will just set payments at a level you can afford so it's know big deal really. Debt collectors know that so they don't have much incentive to go for one, but they'll try and make you think it's more likely then it is.
1 -
Yes, I forgot to say that I'd also read that I need to do it ASAP. I am not expecting too much but if any of them become unenforceable do I still continue paying? It's my understanding that not producing a CCA simply means that legal action cannot be taken on the debt?
0 -
Yes, if they can't produce the cca then they can't take legal action to enforce it so you can simply ignore it. They'll still want the money and will probably try various tricks to try and deceive you and into paying, it's common for them to try and brush off the fact it's enforceable and say it's valid and collectable or something like that. That's s technically true, but they say it to try and imply you are obliged to pay it but there is nothing they can do except ask you to pay it.
2









Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards