We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Octopus and my Credit Score
Comments
-
I understand now. Thank you, that might be the case that I don't fit their customer target. It was really for the joining bonus due to a birthday coming up.
I think Octopus are a criminal bunch. I got this from them
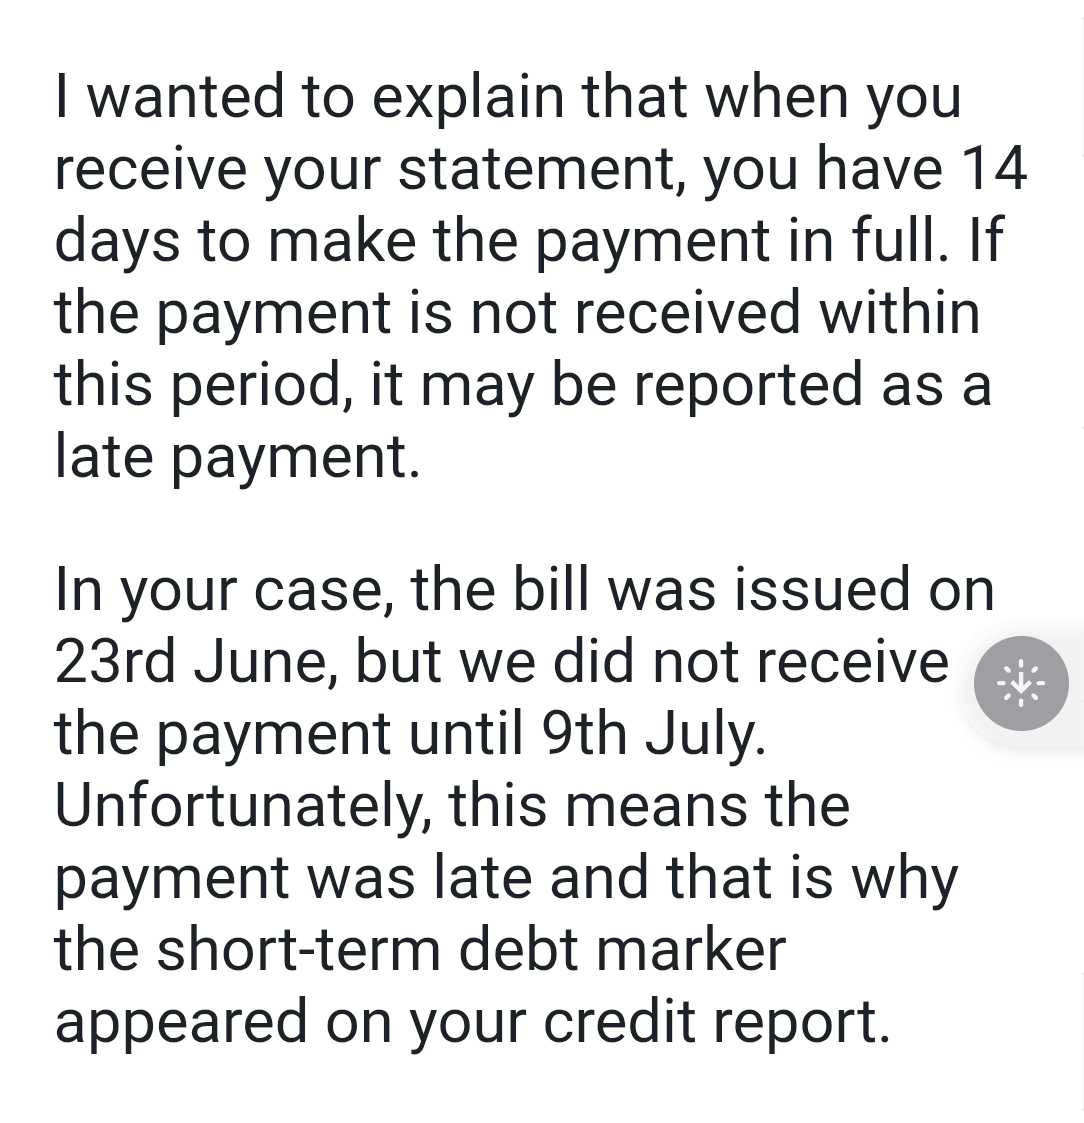
However, these are the terms that they have set
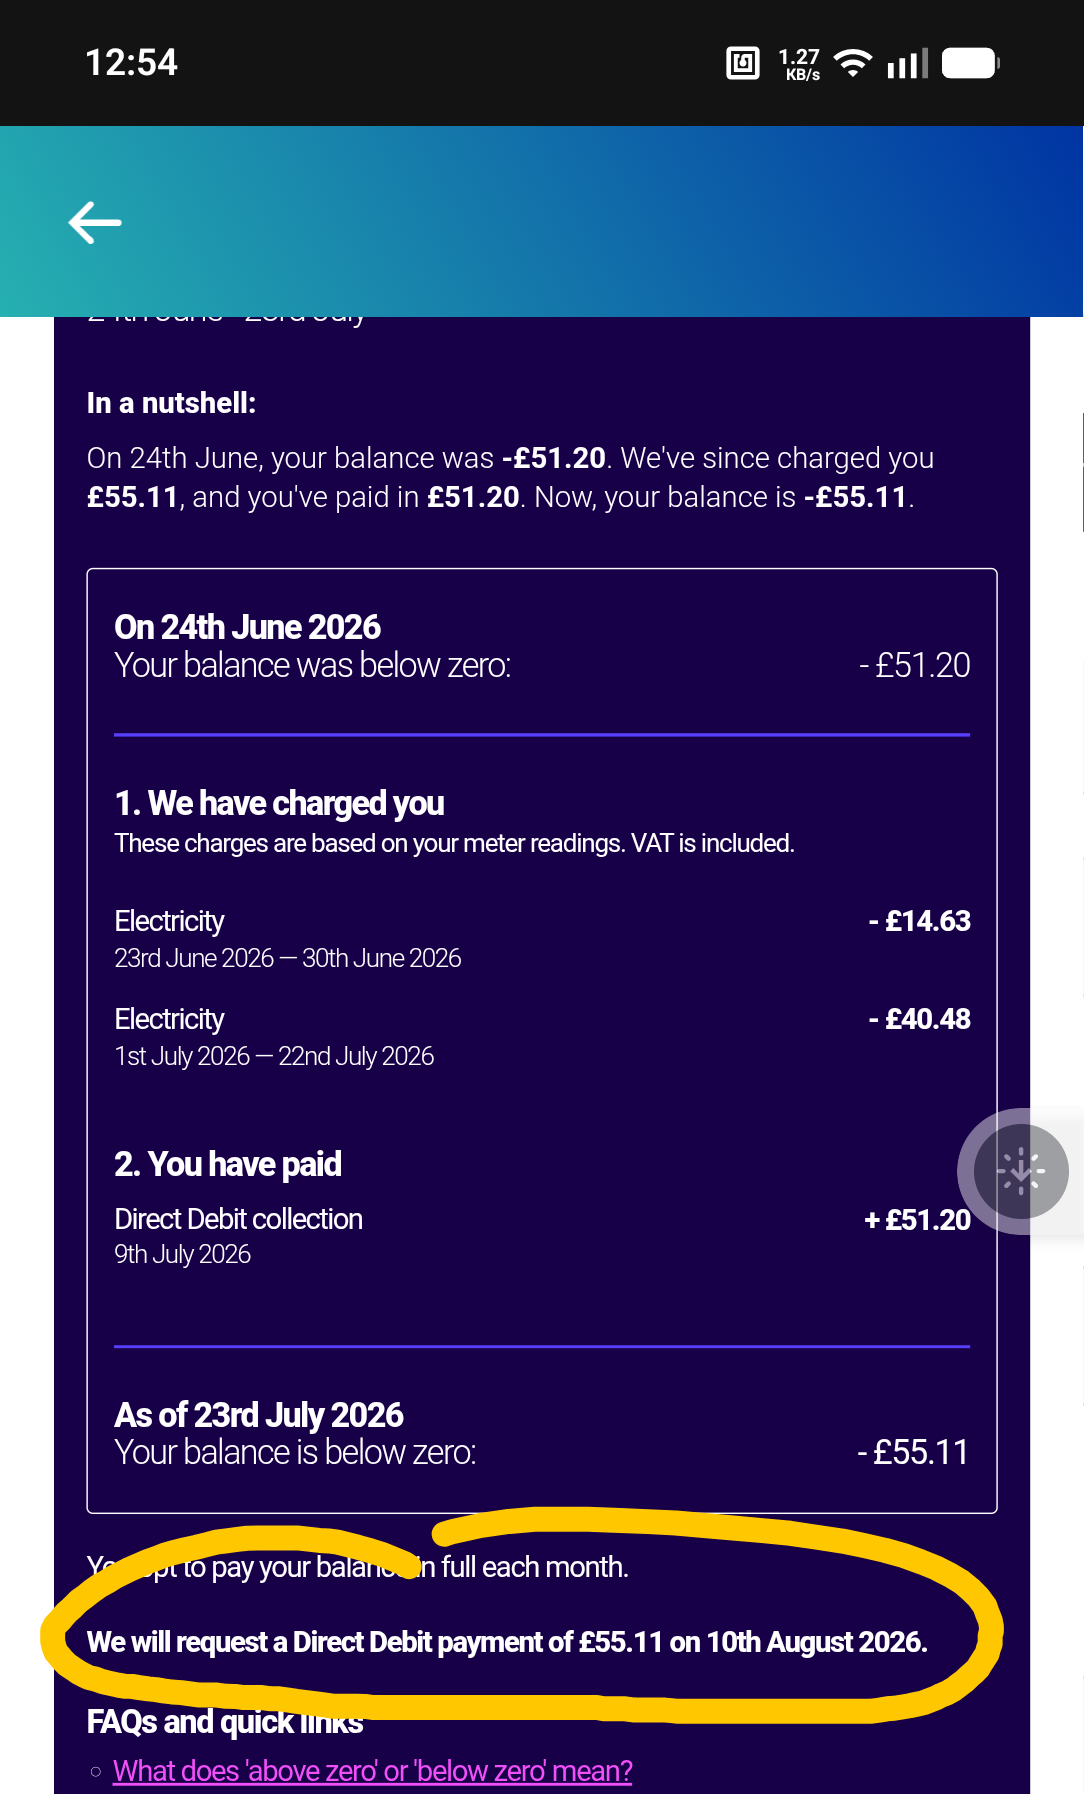 0
-
That looks like an AI response and it is wrong.
I would not suggest calling any supplier 'criminal' on here though.
Did you actually have a late marker on your credit report or was it just a balance recorded as would be normal.
1 -
All the utilities do this, it's not just Octopus. Your made-up score is pretty meaningless, others don't see it. It's largely intended so that you keep coming back to check it, they want to flog you things and bag a commission. Lenders won't care, they'll only be interested in factual things such as late or missed payments, bad debts, CCJs, fraud etc.
You'll find your score will dip a bit even if you move to a different energy provider. The clunky credit rating system will treat this as a new source of credit as if you'd taken out a genuine new loan. I'm expecting mine to dip because the Halifax are moving all customers from MasterCard to Visa, so they're issuing new cards a couple of months before deactivating the existing ones. The same palaver will probably happen all over again when they issue Lloyds cards to replace the Halifax ones because they're trashing the brand.
Barclays are notorious for poor customer service. They're very picky, so your rejection may not even be related to your credit rating, at least not in the way you are expecting: it may be too good ! Many credit card providers prefer customers who aren't perfect (e.g. they don't pay in full every month), but aren't dodgy or criminal (likely to do a runner or commit crime) They just like charging them astronomical interest but know it'll eventually get paid (or the interest paid will vastly have exceeded the original amount borrowed).
It's also possible that the little-known organisation Cifas is to blame: they can quietly set a flag against you that makes it almost impossible to open a new account. My crappy pension provider had a data breach and offered a free Cifas subscription so that any fraudster would face additional checks if trying to open an account in my name. That backfired because I tried to switch to Barclays via CASS, but for weeks the Barclays app has been stuck, foreversaying that they need a few more hours to check my application. Cifas is effectively into victim blaming. Barclays can't be bothered to chase them up, they say I have to do that, but it's almost impossible to contact Cifas, let alone get any sensible information from them.
Similarly, First Direct (part of the international Hong Kong and Shanghai Banking Corporation) de-banked the Chairman of the London Assembly Andrew Boff because he bought a coffee during an official visit to Ukraine. The first he knew was when his card didn't work the next day. The banks are just laws unto themselves.
1 -
Per email therefore it is unlikely to be Ai.
Now also got this:
I will raise this with our credit team to see if we can get the short-term debt markers removed from your credit report. Please bear with me while I wait to hear back from them
"Short-term debt marker" for a DD arranged by them is just unbelievable.
0 -
Per email therefore it is unlikely to be Ai.
To their great discredit, Octopus have been known to use AI in their customer service process.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Ecoflow Stream, Best kettle :-)
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.2 -
Yes, for a long time, before LLM models were really available to the public. It is my one main annoyance with Octopus as it doubled the effort I have to expend on the (admittedly rare) occasion I need to contact them.
1 -
"Short-term debt marker" for a DD arranged by them is just unbelievable.
When you choose a payment method that involves receiving the bill first, then paying, having a balance on your account is entirely normal and is expected.
It also has no negative impact on your credit history. If you are actually using your credit card you will see something similar there as well, or perhaps you have a mobile phone account, that will look the same as well.
Any account that bills you first then collects payment later will appear this way. It tracks your monthly balances and confirms your payments are on time.
This really is a pointless exercise that you are pursuing.
0 -
Are you sure these sorts of contracts always appear with a short-term debt marker? I've never had one. I rather think it's an error.
0 -
These accounts should show with a balance on the account, which is correct for this type of payment, it is the same for any similar account.
If you pay by DD with a regular monthly payment then you will not see the same balance being displayed, but as others have posted in this thread, on monthly variable direct debit, you get billed first and then pay later so the balance is correct.
Short-term debit isn't even a negative marker, it just records a balance, a missed payment would be a negative marker …
0 -
There is no such thing as a short term debt "marker" but any credit account will show a balance on reporting day. The only negative markers would be if the account was in arrears or payments missed and they would clearly be shown as such.
Never associate with idiots on their own level, because, being an intelligent man, you'll try to deal with them on their level - and on their level they'll beat you every time.
Being hated by idiots is the price you pay for not being one of them.
Jean Cocteau 1889-1963
3










Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards