We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Effect of Coronavirus
Comments
-
dunstonh said:
So, you are predicting a loss close to that seen in the great depression of the 1930s. Whilst anything is possible, you appear to be a lone voice.EdGasketTheSecond said:FTSE is still above 5000; watch for it to drop to nearer 3000 or less before buying.
Or perhaps you are going to follow that post up with another gold and silver promotion to try and ramp pricing.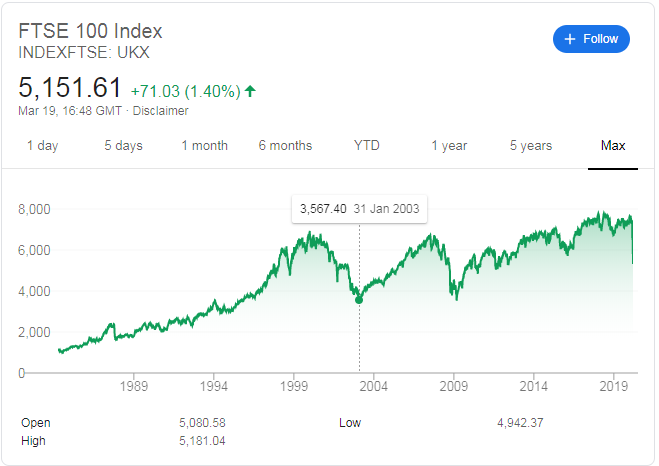
0 -
..and your gain on the FTSE100 with dividends reinvested since 31 Jan 2003 would have been aprox 160%
0 -
Agreed. All I was looking to point out was that based on previous market crashes, hitting 3000-something doesn't seem unbelievable. Infact, looking at those previous charts provided me with a bit of perspective.Alexland said:..and your gain on the FTSE100 with dividends reinvested since 31 Jan 2003 would have been aprox 160%0 -
Look further back in the graph though. If you sold out in 1990 waiting for markets to go as low as they did in the 1987 crash, you'd still be in cash today. The same goes for most of the previous crashes in history.Everyone who sold out in 2011 or 2015 waiting for the FTSE 100 to hit 3000-something again is still in cash, having lost themselves a lot of money.The 2009 bottom being roughly the same as the 2003 bottom is not the norm. If there was something special about the number 3,500 that made it the bottom of the market, it would never reach 3,500 because no-one would sell shares knowing that the bottom had been reached and they were certain to go up.2
-
My financial advisor rang yesterday asking if we wanted to sell some investments from my SIPP to make use of my personal allowance for this year (would only be around £5k to take me up to the limit). I actually said no I would rather not as I think that consolidates significant losses made over the last month or so. The minimal tax I would save by potentially having to exceed my tax allowance is a drop in the ocean compared to the losses I would make on selling. Luckily we don't need it and have plenty of liquid assets and DB pensions. Much too soon to say we are heading towards a Great Depression. All the evidence so far is there will be a bounce back when this is sorted.I’m a Forum Ambassador and I support the Forum Team on the Debt free Wannabe, Budgeting and Banking and Savings and Investment boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com. All views are my own and not the official line of MoneySavingExpert.
Save £12k in 2026 Challenge £12000/£10,000
365 day 1p Challenge 2026 £667.95/£559.45
Click on this link for a Statement of Accounts that can be posted on the DebtFree Wannabe board: https://lemonfool.co.uk/financecalculators/soa.php0 -
I think it would be foolish to rule out further significant losses. The markets seemed slow to react to the spread of the virus initially. Are they now being slow to react to the impact on the ground and the probable length of time it'll be before things get back to 'normal'? A lot has changed in the last two weeks that won't yet have been formally reported by businesses.
Just my opinion of course and I'm doing nothing with my own investments other than continuing with scheduled monthly contributions, but the FTSE dropping into the 3XXX's when it has already briefly been into the 4XXX's does not seem too outlandish a prediction from here.0 -
Your approach does not make a lot of sense - or at least perhaps you're not giving us the full story?enthusiasticsaver said:My financial advisor rang yesterday asking if we wanted to sell some investments from my SIPP to make use of my personal allowance for this year (would only be around £5k to take me up to the limit). I actually said no I would rather not as I think that consolidates significant losses made over the last month or so. The minimal tax I would save by potentially having to exceed my tax allowance is a drop in the ocean compared to the losses I would make on selling.
Say you have 75000 units of a particular investment fund bought for £1 each in your pension. That's £75k in your pension. But let's just look at a small part of it which your advisor thinks you could take out as income this year, say 7500 units or £7.5k invested.
The market falls by a third so each unit is worth only £0.667. Now those 7500 units are only worth £5000 in your pension instead of £7500.
You have an opportunity to cash in the 7500 units and remove all the resulting cash from your pension without paying any tax on it at all, because you have £5000 of spare income tax allowance remaining for the year which would otherwise go unused.
The smart person would say, OK I will cash in the 7500 units, not particularly caring that it makes a loss within my pension, I will take the resulting £5000 out of the pension entirely tax free, and then I will use the £5000 of tax free cash to buy 7500 units outside the pension, which only cost £0.667 each at the moment. The result of that would be that you have 7500 units of investment fund outside the pension, valued at £5000, although we know that amount of fund units was once worth £7500 and will hopefully return to that sort of valuation over time. So you still get the recovery in the end (like you would get in the pension) but you have now extracted a chunk of value from the pension and avoided income tax on the drawings while you do so.
The person who is not thinking clearly will say "no I would rather not do that, because it 'consolidates my losses made in the last month or so'. I would rather wait until the value of the fund shares recover to £7500. Then when I take that money out of the pension I will no longer be able to take it out tax free, because my 2019/20 personal allowance no longer exists, but nevermind I suppose I will just pay 20% tax on all of it (£1500 on £7500) rather than getting away with extracting all of the value of the shares at 0% from my pension by using my spare £5000 of 2019/20 personal allowance."
I can imagine the financial advisor at the other end of the phone putting his head in his hands and wondering why he can't get his clients to understand. If you have money in a pension which is eventually going to need to come out of a pension and be taxable when it does, a drop in the markets is GREAT because it compresses the value of what you have in the tax wrapper, so that you can get more of it out within your existing allowances. When the market recovers you can have it bounce back outside the pension, i.e. after it has already squeezed through the gap in the 'income tax wall' which usually prevents you getting money tax free out of your pension.
Obviously, people's personal circumstances differ but it is usually counterproductive to avoid taking advantage of your personal allowances, especially if they are more valuable than normal (i.e. you can use them to get more shares out of your pension). It can be quite damaging to your wealth to ignore these opportunities and pay more in tax later. Especially if the reason you are saying "actually no I would rather not" is some egotistical reason, like 'I don't want to make losses'. It is usually better to make the losses, avoid the tax and then recover the losses on the other side of your income tax charge.
9 -
I'm thinking 4500 is a good time to jump in as 3xxx seems too unlikely - especially with govts throwing money at every angle to keep economy and jobs intact.. tough to call at the momentruperts said:Just my opinion of course and I'm doing nothing with my own investments other than continuing with scheduled monthly contributions, but the FTSE dropping into the 3XXX's when it has already briefly been into the 4XXX's does not seem too outlandish a prediction from here.
0












This discussion has been closed.
Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.5K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.1K Work, Benefits & Business
- 605.6K Mortgages, Homes & Bills
- 179K Life & Family
- 263.4K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards