Ready, steady… save!
You don’t need a chart to join in. Here are 2 ways to record your savings:
1. Cross it off
Pop a chart into your first post. Saved an amount? Cross it out! Read more »
£0.01 £0.02 £0.03
2. Write it down
Skip the chart and add updates to your first post. Read more »
“Another +£3 saved today. Go me!”
Use +£ before each new saving so it counts towards your total.
We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Warning to Cahoot savers !
Comments
-
Same here, for many years now. The only time I've ever given a specific figure was to explain the situation where a certain institution (cough - Vanquis) were sticking in 'interest paid' figures in their tax statements that I could not access (for multi year fixed rate savers).
1 -
HMRC have contacted me to advise my underpaid tax won't be collected until next tax year - is this usual? I'm sure they've updated my tax code mid-year in the past to claim underpaid tax?
I haven't checked whether their calculation is correct yet, though…
I consider myself to be a male feminist. Is that allowed?0 -
My understanding is that the norm (not every single time without fail though) is for the underpaid tax from year 1 to be collected in year 3 (if it qualifies for collection via PAYE), but they'd normally update PAYE coding for year 2 as well, on the assumption that year 2 liability will be the same as year 1.
1 -
Not wishing to send this thread in the direction of 'earned' or 'accessible' as it has cropped up a number of times, but I have recently had a 3 year bond mature where the interest compounded (the only option).
I am on SA and have declared interest "earned/received" each year as this is what their statement and "certificate of interest" showed each year. I clarified with the institution on their reporting of figures to HMRC and they were clear - they report yearly the amount paid, and not the full amount in the final year when it becomes "available to use".
This is good for me as all in this tax year would have cost me quite a few quid.
0 -
Thanks Masonic. You got that spot on and you articulated in a fe words instead of the 50,00 words I use
0 -
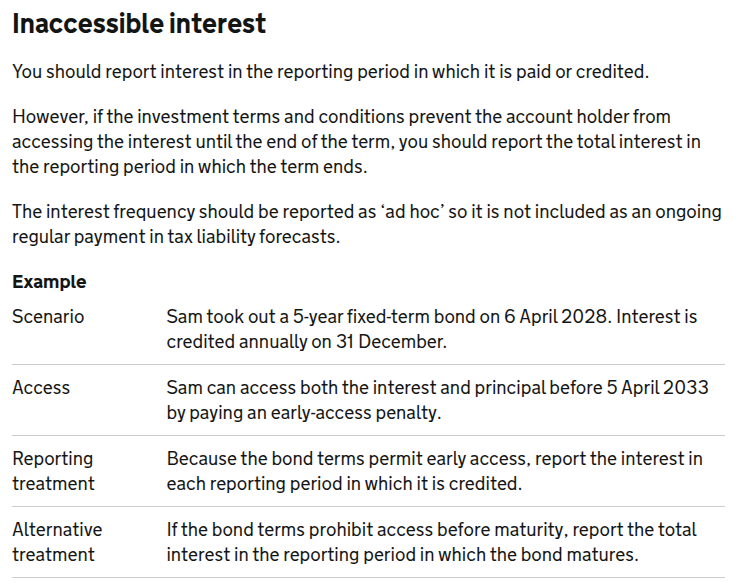
I'm always interested in such information and 'guidance' but given the use of that word and repeated use of 'should' as opposed to 'must' I wonder whether this is legislated?
0 -
It is a policy paper from HMRC titled "Interest income schema guidance". The legislation on when the tax liability falls is a settled issue and has been for quite some time. The reporting was out of step with this and will continue to be until/unless this is implemented.
1 -
Banks reporting interest under different names, has been happening since the £1000 personal allowance was introduced in 2016. First Direct and M&S were reported under HSBC. Kent Reliance as One Savings. Marcus as Goldman Sachs. Halifax and Bank of Scotland as Lloyd's. Now Tesco is Barclays. Cahoot as Santander.
I found all this out when trying to sort my parents interest out in 2019 with a complaint which took 6 months to resolve, because unless the information you give HMRC exactly matches Bank name, sort code and account number that they have, then it will get duplicated as the system doesn't match it otherwise. The reason it was duplicated was because we had provided HMRC the interest figures for 2018-2019 in advance because we knew they owed tax and when the banks had finally supplied the figures, it totally mucked up their tax accounts as everything had been duplicated. Reason being because the names didn't match, there was no sort code quoted or no account number or different account numbers i.e. only the last initials for Santander and Ford Money accounts instead of the full number.
So now every year I get a BBSI sent for my parents, husband and myself in April and I check it off with what we have and then call HMRC and provide closure dates for all the accounts that have been closed in the previous tax year and so they won't get carried over as estimates to the following year or existing tax year because I usually contact HMRC in June. When they ask for the figures for the existing tax year, I just explain that I was told that I didn't need to supply these because things get duplicated and so I just give them the figures that I know because the account has already been closed in the tax year or an estimate for accounts that are still open and have been for the previous tax year, so I know it won't get duplicated but overwritten with the actual. All regular savers I just give them the closure dates and so they aren't carried over.
I have been doing this for the last 6 years and generally I have had no problems, but occasionally the member of staff hasn't processed it correctly, so they have applied the closure dates but haven't remove the account from the existing tax year.
1













Categories
- All Categories
- 356K Banking & Borrowing
- 255K Reduce Debt & Boost Income
- 456.3K Spending & Discounts
- 248.5K Work, Benefits & Business
- 606.2K Mortgages, Homes & Bills
- 179.1K Life & Family
- 264K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards