Ready, steady… save!
You don’t need a chart to join in. Here are 2 ways to record your savings:
1. Cross it off
Pop a chart into your first post. Saved an amount? Cross it out! Read more »
£0.01 £0.02 £0.03
2. Write it down
Skip the chart and add updates to your first post. Read more »
“Another +£3 saved today. Go me!”
Use +£ before each new saving so it counts towards your total.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Investment or Savings


I wonder if someone could explain the basics here. The general outlook is that investments out perform savings, however, when I take a very quick view it does not seem clear. Taking the FTSE 100 as an example, over 10-years its growth is around 4.5% PA (6775 to 10600). Given that saving rates of 5% are possible (with no risk), I do not see how investments are preferred.
The numbers I use are a generic example, to explore the basic premise…. what do I miss?
Comments
-
You also get dividends on top of that capital growth. The FTSE 100 yields approx 3%, making a total return of around 7.5% in your example.
Between 2017 and 2022 - half of your 10 year period - interest rates were down at around 1-2%. The average rate for comparison is probably in the region of 3.5%. So roughly 4% extra from investing (before tax).
A global investment would have done rather better than a FTSE 100 tracker.
5 -
Taking the FTSE 100 as an example, over 10-years its growth is around 4.5% PA (6775 to 10600).
That ignores dividends.
Given that saving rates of 5% are possible (with no risk)
For at least half of the last ten years, savings rates were 2% or less.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Ecoflow Stream, Best kettle :-)
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.1 -
Thanks for the comments.
Clearly there was a significant difference when interest rates were low.
But as of today you can get 5.25% fixed for 5-years…… basically the gap and therefore the decision is not "as clear" as previous years. ( I am no analyst but the global outlook does seem to hold more risk than 5 or 10 years ago).
I guess it all comes down to an individuals outlook on risk.
0 -
But as of today you can get 5.25% fixed for 5-years
Five years is quite a short time for an investment. If you're going to need to spend the money within five years, you're probably better off with a savings account (or, if tax is a concern, something relatively safe like a gilt).
Although, hindsight is wonderful; VHVG for example is up 78% over the past five years. You wouldn't have managed that with a savings account.
I am no analyst but the global outlook does seem to hold more risk than 5 or 10 years ago.
There is always trouble on the horizon. Sometimes it bites, sometimes it doesn't. And ten years is a relatively long time.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Ecoflow Stream, Best kettle :-)
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.3 -
The general outlook is that investments out perform savings, however, when I take a very quick view it does not seem clear.
context is important. Over the long term, they always have outperformed savings. However, over the short term, that is not always the case. In rare cases, even the medium term has a very small number of occasions where investments haven't
Taking the FTSE 100 as an example,
Not a great example:
1 - The FTSE100 is a dividend index. The value of the FTSE100 is the share price but doesn't include the dividends that have been paid out. You have only looked at the share price.
2 - Its UK only. The UK makes up 4% of the world economy. Global equities is the more typical benchmark.
But as of today you can get 5.25% fixed for 5-years…… basically the gap and therefore the decision is not "as clear" as previous years. ( I am no analyst but the global outlook does seem to hold more risk than 5 or 10 years ago).
risk is always present. One risk goes away and another replaces it. Nothing is going on at the moment that is any different to periods that have gone before. The reasons and issues vary (although some are surprisingly repetitive over generations).
Equities have more than doubled in the last 5 years. How is your cash doing?
Here is a comparison between a global tracker fund and SONIA. SONIA is a good benchmark for cash and the global tracker is a good benchmark for equities.
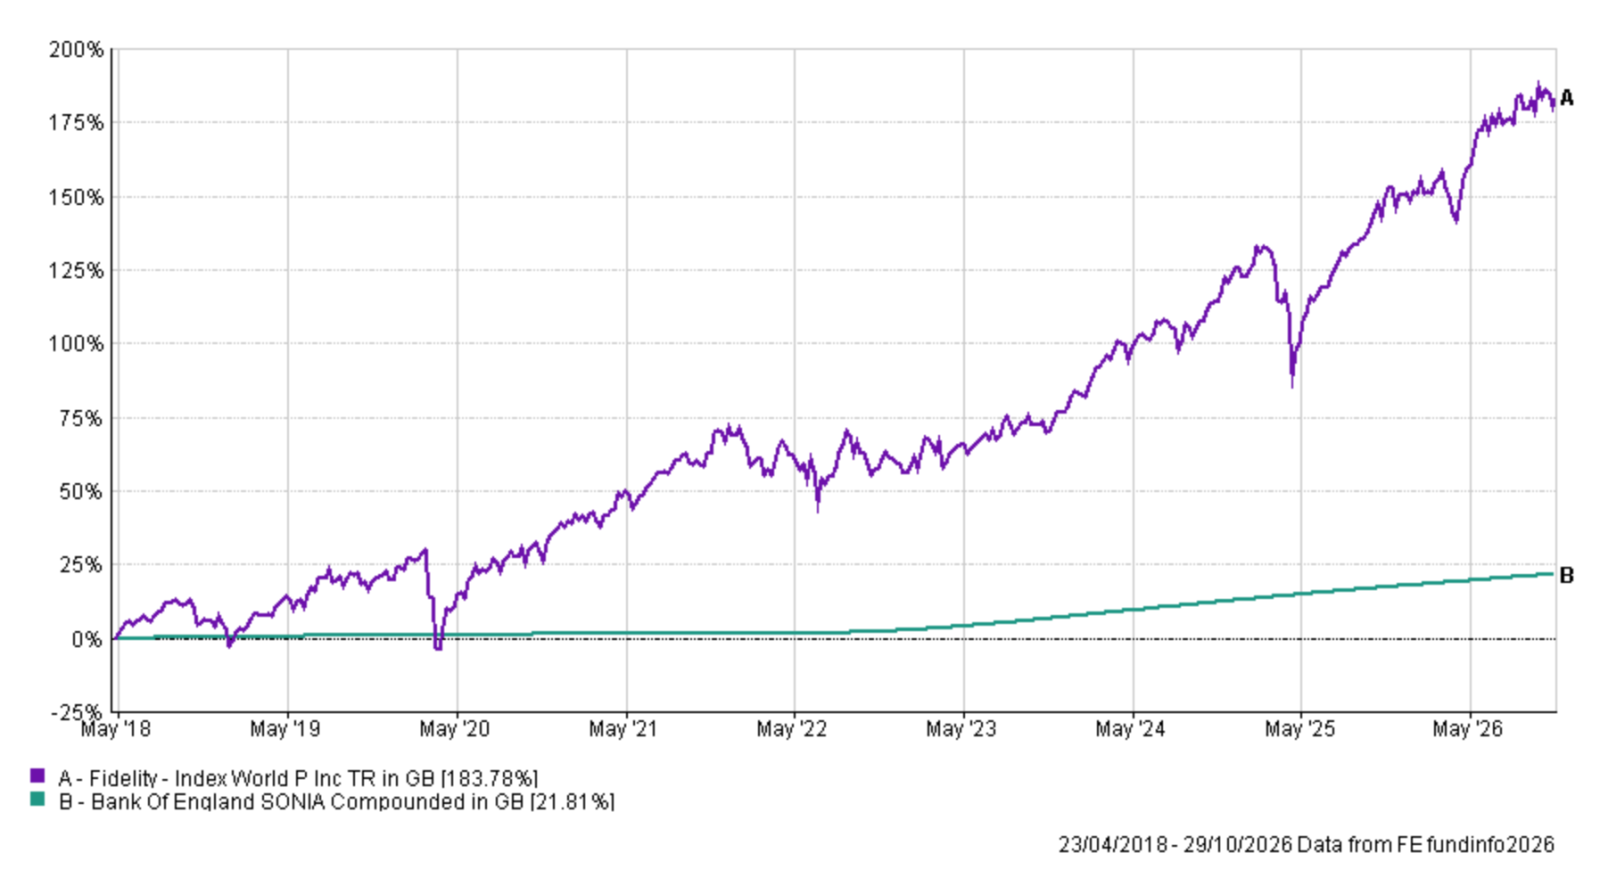
This time period worked out well as it starts in May 2018 and quarter 4 2018 saw the stock markets crash. So, there is your first loss period in the short term. Then in 2020 you had the third largest negative period in over 25 years - Covid. Still in the short term but enough to put equities negative to cash for a short period. 2025 had trumps tariffs and 2026 had the start of the Iran war but it highlights the benefit of investments over the medium term (still not long term but long term makes that gap even bigger).
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.5 -
It's not just down to the individual's risk tolerance - it's the objectives and timescales for the money that should primarily drive the decision, so, as above, the answer for five years probably won't be the same as for 10-15…
1 -
Over long time periods, the returns from investing have far exceeded the returns from cash savings.
Whilst today's current savings rates seem attractive, they can change. It wasn't too long ago that savings rates were hovering around 1% for over a decade.
The real killer is that over long time periods, cash savings haven't even beat inflation which means that the purchasing power of your money has reduced.
This was all explained really well in the recent Martin Lewis show:
https://www.youtube.com/watch?v=INppoe97Uj4
0 -
dont think SONIA (3.73%)represents savings rates theres plenty between 6 & 8%
0 -
Sonia very much represents long term savings rates. There will always be a few better but far more worse. However, even if you add a percentage or two you are still nowhere near investments.
BTW, top instant access savings rate is 5.00%, top fixed is 5.17 for 1 year or 5.28% for 2 years, 5.4% for 5 years according to MSE.
Booster style accounts may do 6-8% but they are not worth comparing here as the amounts are restricted and very small and not really the sort of thing someone uses instead of investments.
However, if you are referring to mainstream savings accounts with 6-8% available then please name them as I haven't been able to find any and MSE is not showing any,
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.4 -
theres plenty between 6 & 8%
As dunstonh says above, if you know of a savings account that someone can put £50k into tomorrow and earn 8%pa gross, please share the details here for the benefit of MSE.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Ecoflow Stream, Best kettle :-)
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.0






Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.4K Work, Benefits & Business
- 606K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards