Ready, steady… save!
You don’t need a chart to join in. Here are 2 ways to record your savings:
1. Cross it off
Pop a chart into your first post. Saved an amount? Cross it out! Read more »
£0.01 £0.02 £0.03
2. Write it down
Skip the chart and add updates to your first post. Read more »
“Another +£3 saved today. Go me!”
Use +£ before each new saving so it counts towards your total.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Massive increase in car insurance




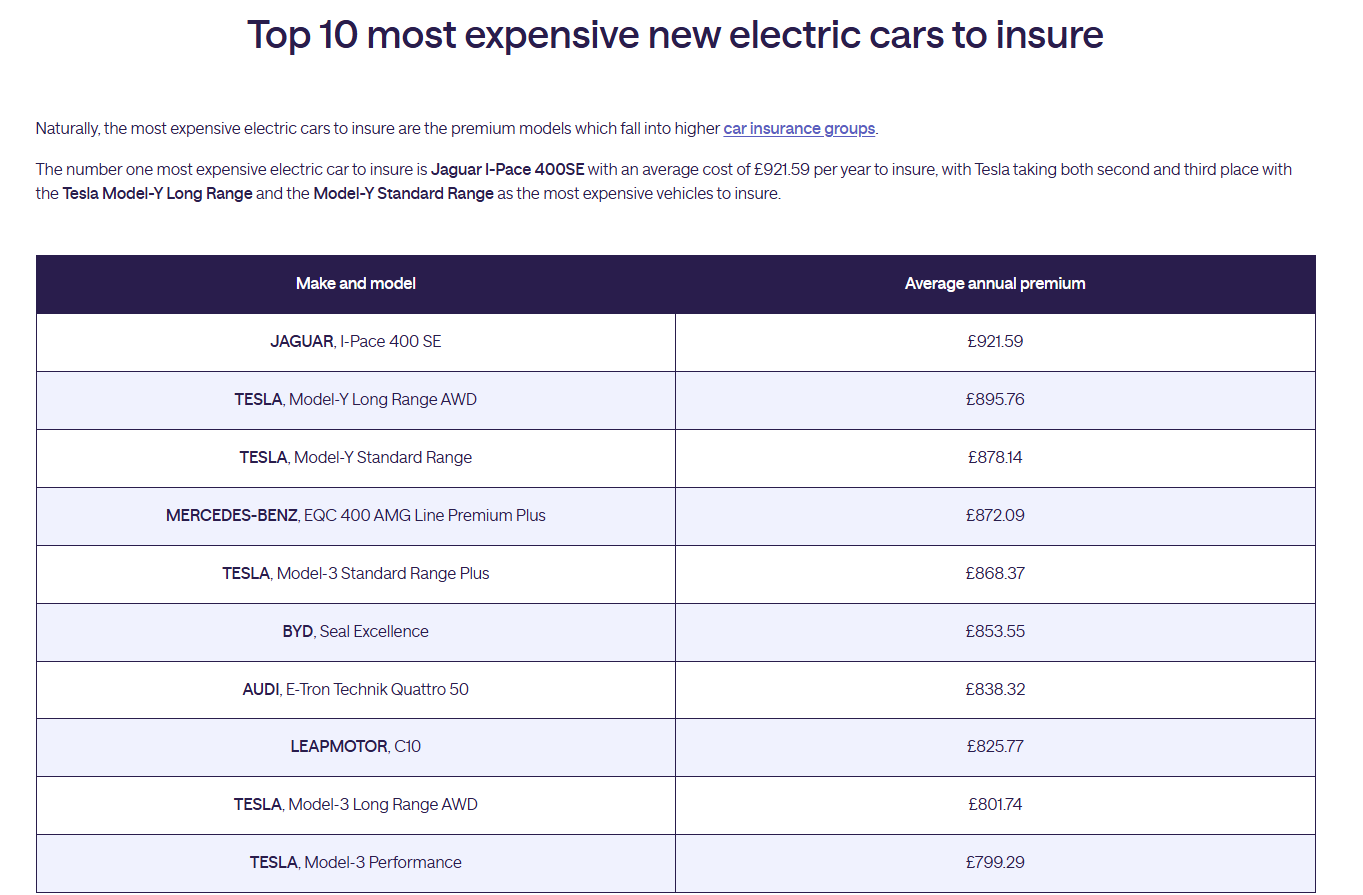
A couple of years back, my son treated himself to a one-year-old Tesla Model 3 Performance straight from Tesla. Since then, he's had absolute rotten luck with other people crashing into him:
Incident 1: Rear-ended at a red light by an uninsured driver on his mobile in his mum's BMW (£5k claim including hire car).
Incident 2: Sitting stationary at a roundabout when a delivery driver—again on his phone—ploughed into the queue behind him, shoving the cars into the Tesla (£4k claim).
Incident 3 (4 years ago): Someone hit their SUV on a roundabout and tried to blame my son's partner, but dashcam footage proved 100% third-party fault.
Both he and his partner have 15+ years protected NCB and clean licences. The car stays on the drive, they both work from home, and they do about 10k miles a year.
Even though every single incident was 100% non-fault, his renewal just landed at £1,975—nearly double last year's £1,050. Offering to raise the excess to £1k didn't knock a penny off. Comparison sites are throwing up quotes anywhere from £1,850 up to a ridiculous £2,700. I told him to give Direct Line or Aviva a go, as I vaguely remember an EV vlogger saying they were decent on electric car rates.
Anyone else with a Tesla or fast EV seen their insurance double like this over non-fault stuff? Any tricks to get it back down to a sensible price with a proper insurer?
Having posted the above, though he is not happy at the increase as most people would not, for whatever reason he loves his car and will keep it even if the ins premoiums went up by a lot lot more - But, I thought a bit of direction some some here is a similar boat may be able to help to bring the premiums down.
Comments
-
Whether fault or non-fault someone involved in 3 incidents in a relatively short period of tine is, statistically, a higher risk of being involved in future incidents.
The 'average Joe' is likely to have zero incidents in that same timescale. In short it's not the actual car increasing the premium it's the increased probability of the driver being involved in an incident. If you have tried all the comparison sites, added a named driver etc then not much else you can do.
2 -
Sorry not got EV or performance car (I'd love one but can't charge anywhere or afford one) so unable to add from that perspective, but to add, they're not just covering the risk of your son driving a 'performance car', but also spares, labour costs, fitting specialists. There are systems on cars, EV especially which require specialist healthchecks, for instance a damaged / cracked bumper isn't just pop off the old, replace a few clips, and fit new or repaint old, there's parking sensors, cameras, distance sensors etc etc to check / replace. Specialist garages aren't cheap, nor are spares always available.
I'd imagine as more people take up EVs higher premiums will be commonplace short term.
However as ITFR99 says 3 incidents whether fault or not in 4 years will be perceived, rightly or wrongly as higher risk.
Is the partner on the insurance? If they're home based there's very little to adapt quote wise, can the 10k miles be reduced? Is street parking possible, weirdly garages and driveways may increase the cost.
0 -
Technically the first claim probably was a fault claim if the other driver was uninsured. Because your son’s insurance company will presumably have had to pay out themselves with no one else to claim against?
All shall be well, and all shall be well, and all manner of things shall be well.
Pedant alert - it's could have not could of.0 -
There are too many variables to be able to make a comparison. My electric BMW i4 is £400 a year with Aviva. I expect some people pay less, some considerably more.
1 -
regardless of whether the 3 incidents were his fault or not, having that many collisions in a short period of time is going to suggest to insurers that he is a high risk driver.
1 -
I've just renewed my insurance on my EV. It's nothing special, but like many EVs and other cars these days, it has the performance of a 1990s GTi.
My existing insurance went up by about 20% to over £500 so I went through the process of requoting - 3 x comparison engines and 2 x direct quotes. The comparison engines were good - the cheaper quotes were within £50 of each other. What was striking was that the two direct quotes were huge - one was twice the cheapest, and one was even more than that.
I don't have any recent claims or convictions, though.
One thing that I have found in the past is that claiming on the other party's policy because they were 100% at fault seems to be more persuasive to the insurance companies, than claiming on your own policy but not being at fault.
0 -
Thank you all for taking the time to chime in—I really appreciate the help.
Just to be 100% clear: none of these incidents were their fault. During that roundabout accident four-odd years ago, the driver cut across a mini-roundabout at high speed, lost control, and clipped them. She then got out, as did her mates ranted and raved/swore, and blamed my daughter-in-law—all while she had our grandkids in the back of the car. Luckily, the SUV had a dashcam, and as soon as the insurance company saw the footage, they put 100% of the fault on the other driver. So across all three incidents, the third parties were entirely to blame (including the uninsured one who was on his mobile phone at the time).
It really looks like Teslas are just brutally expensive to repair for what they are.
I texted our son last night and suggested he try Direct Line, Aviva, and check cashback sites like Quidco. He said he'd look into it when he gets a free moment, especially since he still has about two and a half weeks before the policy expires. He did mention to me the other day that he loves the Tesla Performance and plans to keep it regardless, even if the premium pushes a lot higher.
Anyone with a Tesla/performace has any incident, not their fault and ins renewal experiences to share?
At the end of the day, insurance is a business and they need to make money—we get that—even if it feels thoroughly unfair. It seems that if you're involved in more than one incident within five years, even as a completely blameless victim, you still get heavily penalised with massive premium hikes.
0 -
Fault in insurance terms does not mean who actually caused the incident. A fault claim is one where your insurance company pays for the claim. If a third party crashed into your car and drove off and you had no idea who actually did it the insurance claim would a fault claim as your insurance company would pay out as they would not be able to get the money from the third party's insurance company.
0 -
The term "Fault" in the insurance industry is nothing to do with blame or cause. It hinges on whether your son's insurer were able to reclaim their costs.
In the case with the uninsured driver, they probably could not, hence it would have been classed as a "fault".claim.
2











Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.9K Banking & Borrowing
- 255K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.4K Work, Benefits & Business
- 606.1K Mortgages, Homes & Bills
- 179.1K Life & Family
- 263.9K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards