Ready, steady… save!
You don’t need a chart to join in. Here are 2 ways to record your savings:
1. Cross it off
Pop a chart into your first post. Saved an amount? Cross it out! Read more »
£0.01 £0.02 £0.03
2. Write it down
Skip the chart and add updates to your first post. Read more »
“Another +£3 saved today. Go me!”
Use +£ before each new saving so it counts towards your total.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Bank over-reliance on Credit Agencies
Comments
-
That's as maybe. But there was a term we used in IT work that could easily be applied to Credit agency information used by banks to assess "risk". GIGO
"Garbage in - garbage out" 😅
1 -
Which is why there is a (statutory) right to see the data that the agencies hold on you. If there's any "garbage" there then you can get it corrected.
They don't do any processing or assessing of this data, their role is simply one of collation and presentation.
The "credit score" guff that they feed to punters is a whole other bucket of numbers that they don't even bother taking the Garbage In for, but not relevant here.
2 -
But thats why the CRAs allow the banks to make their own decisions on what's relevant or should be taken into consideration. They dont definitively state that Dan Smith and Daniel Smyth at 1 low road, Warwick are the same person or not, the bank can decide either by setting their own rules or by requiring a minimum confidence factor.
The concept of CRAs is to join up history from different organisations and they would be a little weak if they could be circumvented by simply using the diminutive form of your name or using an alternate spelling of surname
Plus banks are the largest providers of data to CRAs so if you think the data is junk they have only their own industry to blame
0 -
It must bother you or you wouldn't have posted about it. You didn't fit their lending criteria, just move on.
Whilst not relevant for this topic, I've been recently amused by a topic about Creation Finance and people with 999 credit scores being apoplectic in getting turned down for credit for the new iPhone Duo with some, probably less educated people, doing 3 or 4 applications one after the other because their 'score' is 999.
These people are our future I don't know why you would commit to 3 or 4 hard searches on your credit record in the space of 10 minutes because they don't understand why they've been turned down…
0 -
It seems perverse that someone with no recorded credit history may have a lower rating than someone who has defaulted!
Also, parasitic credit agencies have spawned other resources like MSE Credit Club designed to help massage credit ratings for the anxious or neurotic!
For me, financial institutions should be required to reveal why they rejected an application, the information that determined the decision and where it originated. If it is shown that a credit agency provided inaccurate information that materially affected the decision then the applicant should be compensated.
This is what the Zopa-Bot returned when I questioned it:
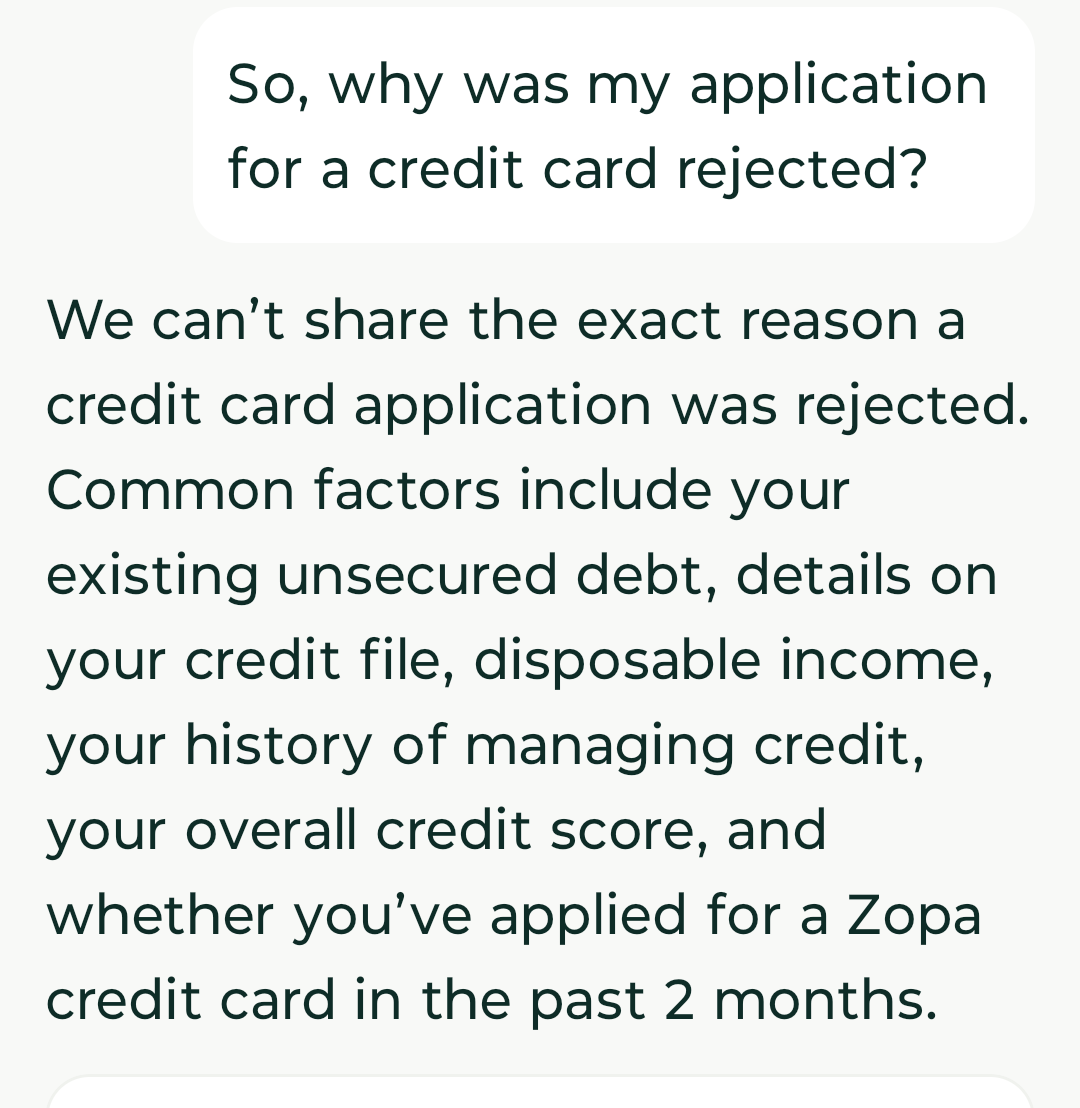
I think the gvmt needs to resolve this lack of transparency.
1 -
It seems perverse that someone with no recorded credit history may have a lower rating than someone who has defaulted!
Also, parasitic credit agencies have spawned other resources like MSE Credit Club designed to help massage credit ratings for the anxious or neurotic!
But to be fair, this forum (and to a lesser extent the main editorial side of MSE) strive to emphasise to the neurotic and anxious (and anyone else) that CRA credit ratings/scores are irrelevant! On the other hand, it's recommended to check the underlying data held by the CRAs, in order to identify and correct any errors.
For me, financial institutions should be required to reveal why they rejected an application, the information that determined the decision and where it originated. If it is shown that a credit agency provided inaccurate information that materially affected the decision then the applicant should be compensated.
[…]
I think the gvmt needs to resolve this lack of transparency.
Neither the FCA nor the ICO have any issue with the current process - obviously the more information that's disclosed about rejections, the more likely it is that this will encourage falsification of application data, so financial institutions are able to justify keeping their internal proprietary algorithms confidential.
Edit: and just to pick up on the idea that applicants should be compensated if a decision was affected by inaccurate data, the issue is demonstrating (a) where the inaccuracy arose (the CRAs will naturally explain that their data is provided by others) and (b) whether there's actually any sort of culpability or liability involved, i.e. if there was demonstrable negligence, etc - the vast quantities of data collated by the CRAs is never going to be 100% accurate all the time but both they and the submitting institutions are always going to have auditable processes to keep errors down to a bare minimum.
0 -
There is transparancy. You can obtain a copy of your report and if it contains errors you can have it corrected. And may have a legitimate complaint against whichever institution submitted incorrect data.
The more likely explanation is that Zopa have lending criteria which you do not meet. If they didn't use the credit reference agency and decided to revert to manual underwriting, then you'd have to send in your pay slips, bank statements etc for someone to review. Then you'd still get rejected if you don't meet the criteria.
The days of the bank manager thinking someone's a "decent chap" and granting credit are long gone. And that's fair - it makes it easier to shop around and means customers won't be rejected because someone takes a dislike to them.
1 -
It may be that Zopa has lots of highly credit worthy customers who want to borrow money from them, and has little money available to lend. In recent years, I have been offered starting credit card limits ranging over more than a factor of ten by different issuers, with little change to the relevant numbers.
As others have said, putting all your business with one bank is asking for trouble.
0 -
Banks dont like the unknown, they are naturally cautious creatures. Basel III etc also come into play. Banks work by taking deposits from customers (a liability on the balancesheet) and lending that money to others (an asset on the balancesheet). It however would be highly risky if a customer deposited £10k and the bank immediately lend £10k to a random person that comes in the door as how would the bank repay the depositer if the debtor defaults on the loan? So instead a lender must add some of their own money to the depositers as capital to protect the depositer. How much has to be added dictates the risk and someone who you have no information on is going to be a risky person so will require the bank to put more of its own money.
Who you decide to lend to is considered highly commercially sensitive, same as insurers pricing models and how much Tesco's pricing works. Its never going to be made public, any more than how the 99p pasta sauce jar is split between distribution, wholesale, profit, staffing cost etc. They tell you the price, you decide if you want to buy or not, and if you want to buy from A or from BRegulators, police and the Ombudsman have the right to ask for the information to make sure nothing illegal or breaching regs is occurring but it wont be passed on to consumers.
0 -
You don't need to get a card with the bank you bank with, you can look across all the cards available. One of the good ones just now is the Lloyds Ultra with 1% back on purchases for 12 months, or you can get a long term 0% purchase card and save the payments, and so on. You can be looking at optimising the benefits, not the products from other places you have accounts, and there's nothing much about the Zopa card benefits that seems of interest as far as I can tell.
And you can also do a bit of both, switch to Lloyds Club and get a switching bonus (£200), then use their ultra card.
There may be something about the way you're filling in the validity form that's flagging something like a minimum income threshold. There's usually a field for income from savings and investments and you need to make sure that's filled in accurately. I would be using one of the whole market eligibility checkers, there's one on MSE and the same thing on moneysupermarket, and then choosing from what's available.
0













Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.9K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.4K Work, Benefits & Business
- 606.1K Mortgages, Homes & Bills
- 179K Life & Family
- 263.9K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards