We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
SIPP Providers who allow 'in specie' transfer from maturing SAYE to a SIPP
Comments
-
Let's face it, it's a pretty egregious tax dodge, (the flexi part) - entirely legal but also entirely in the zone of things that probably will get closed off before too long!
0 -
Hi all.
@DRS1 it was indeed me. I'll link the original thread below if I can find it.
@gopalgriffith I am in a very similar situation. But from everything I have read, I believe that a SIPP transfer is counted as a disposal for GGT purposes, however an in-specie transfer to an ISA is not.
This is certainly Hargreaves Lansdown's opinion…...
When you do this through HL, your shares will first be transferred to an HL Fund and Share Account before being moved to your HL Stocks and Shares ISA or HL SIPP. Transferring the shares to an HL ISA within the 90-day period outlined above will not count as a disposal, so you wouldn’t have to pay CGT. However, as the shares are first transferred to an HL Fund and Share Account rather than directly from the SAYE scheme, transferring the shares to your HL SIPP would count as a disposal, so you may have to pay CGT.
However, you may be able to utilise the Flexible ISA route which I am planning "hoping" on doing (below), and then make a payment from your bank account into your SIPP which should gain the 20% via relief at source, and claim back any higher rate relief via your tax return.
To give a update to my current plans:
I was in a 5 year SAYE scheme which was due to mature in December 2027, but by taking advantage of a fortunate redundancy opportunity in June this year I am now officially a "good leaver" and so can excercise my options now.
However, I am currently in the process of paying the additional 6 months of contributions which I am permitted to do as a good leaver so I will be excercising my options in December. (I am not passng up the opportunity to make additional payments as the option price is £7.20 and the current current share price is £33.75).
As my scheme value will be £24K in december, I can't "in-specie" transfer this in one go, so the current thinking is that by using a flexible ISA, it is possible to "in-specie" £20K worth of shares to the ISA. Sell (dispose) of the shares within the ISA, thereby avoiding CGT, and then move the cash out of the ISA to your regular bank account.
However, as the ISA is flexible, this will then give you another 20K ISA allowance, which should allow you to you move in another £20K of shares, and then rinse and repeat until all the funds have been emptied out of the SAYE scheme.
The main hurdles are:
- Your SAYE provider needs to be willing to transfer multiple £20K chunks into your S&S ISA.
- Your S&S ISA must be flexible
- If you have made any contributions to any other ISAs in that tax year, this will reduce the amount you can move each time, meaning more repetitions will be needed.
- Your S&S ISA provider must be willing to accept in-specie transfers from a SAYE earn scheme which they are permitted (but not obliged) to do by providing them with a Letter of Appropriation from the SAYE Scheme administrator.
- All funds must be transferred through this route within the 90 day period permitted for SAYE in-specie transfers.
"IF" the above is possible (and internet opinions and interpretations of the rules are certainly divided in the community) then happy days!
… Watch this space in the next few months. 😉
• The rich buy assets.
• The poor only have expenses.
• The middle class buy liabilities they think are assets.1 -
A couple of years ago when I first hypothesised this, a search showed a couple of SAYE schemes actively advising / encouraging this approach on their websites. One of these being Tesco, who's legal people (I would imagine) should be pretty on the ball.
I also found a still live reference on the EQI website which mentions this, though the article is a few years old:
Quote: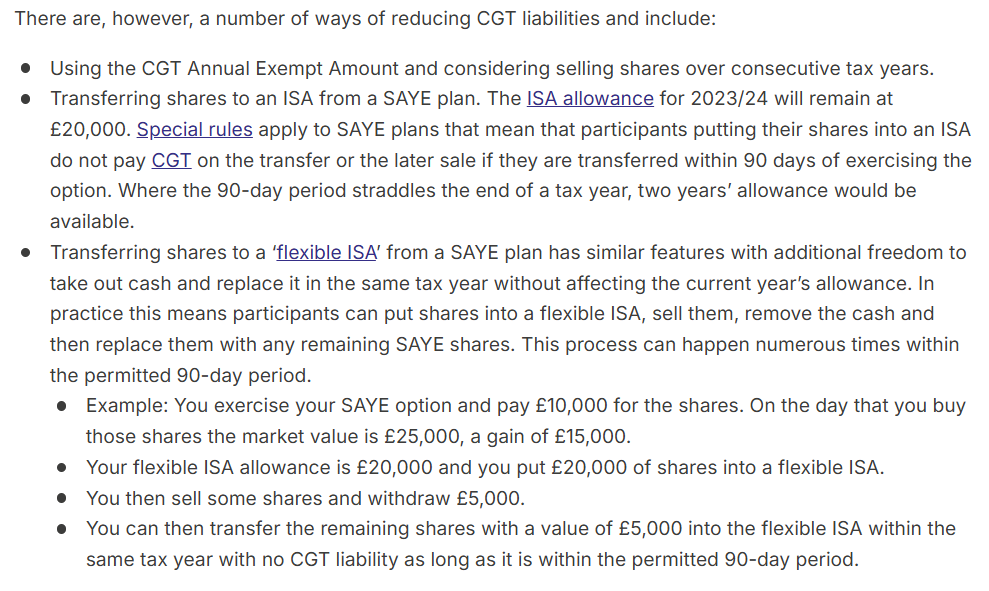 • The rich buy assets.
• The poor only have expenses.
• The middle class buy liabilities they think are assets.2 -
I suspect whoever dreamt up the flexible ISA did not think about its interaction with the Revenue approved all employee share schemes.
And there are relatively few flexible S&S ISAs. OP - Charles Stanley do one I believe, in case you are looking for an alternative to Equiniti.
1 -
Having flagged the flexi isa 'dodge' for multiple SAYE share transfers, unsurprisingly Equiniti have their own flexible ISA available to do just that -
Will be interesting to see if @vacheron pushes ahead with this idea assuming his SAYE provider are prepared to entertain the possibility.
1 -
Somewhat positively my SAYE provider is indeed Equinity.
I say "somewhat" because I think using their FISA would be by far the most straightforward route, even if their fees are substantially higher than others, however their reputation for being competent and efficient is somewhat questionable.
Based on the above, my main concern is having to run through this process potentially up to 7 times within the 90 day window in order to move everything through in time. (Though I guess that could be reduced to 6 passes as the last 20K can remain in the ISA and be removed later at leisure).
I will of course let everyone know how I got on…. good or bad! 😉
• The rich buy assets.
• The poor only have expenses.
• The middle class buy liabilities they think are assets.2 -
I say "somewhat" because I think using their FISA would be by far the
most straightforward route, even if their fees are substantially higher
than othersAlthough you could presumably then transfer on from the S&S ISA to another platform in due course.
1 -
Agreed.I was referring more to their trading fees for selling the shares inside the ISA etc. (which I'll have to do half a dozen times or so) but in the grand scale of things it isn't really the greatest concern.
• The rich buy assets.
• The poor only have expenses.
• The middle class buy liabilities they think are assets.1 -
Please do keep us (me) posted. It is certainly interesting that this may be possible. I think there are a few other providers that offer flexible ISAs (but whether they also allow in-specie transfers is another matter).
One possible advantage of using Equiniti, is that they have webpages suggesting this quirk is indeed possible. Given that HMRC have largely washed their hands and said they are not experts and that one should "check with your provider" - by using Equiniti you can reasonably rely on information on their website and proceed accordingly.
0 -
Tbh if the flexible ISA route works, it doesn't make much sense to do the in-specie SIPP transfer (especially given the fact that there seem to be very few (if any) providers who do this direct).
Of course, if one wanted the tax relief (and I may, as I am a higher rate tax payer who is not a million miles from retirement age), I could just take the cash released through the flexi isa route and pay that into a SIPP in my own time, receiving the tax relief then…
Definitely feels like this was not the intention - but if it is possible and not manifestly prohibited, then it is worth a shot.
0







Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards