We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Deed of Variation


I have an inheritance arising from my parents’ estate, which is to be divided equally between my brother and me. My inheritance comprises a 50% share of our parents’ property and 50% of the residual estate (i.e. savings).
I would like to vary my entitlement to the residual estate so that my share passes directly to my two children, with the intention of mitigating any potential future Inheritance Tax (IHT) liability on my own estate. My 50% share of the property would remain vested in me, so that I would retain the benefit of the Residence Nil Rate Band (RNRB), subject to the relevant conditions being met.
Following some online research, I have prepared the below Deed of Variation, which I intend to keep with, and as supporting evidence for, my Will. My intention is that it will provide my executors with a clear record of the arrangement and assist them in determining the value of my estate and any IHT implications in the future.
Does this approach seem reasonable and appropriate? I would be grateful for any comments, suggestions or advice on the wording itself, or on whether there is anything else I should consider.
DEED OF VARIATION
DATED: 1 October 2026
PARTIES
(1) Fred Bloggs of [Address] ("the Current Beneficiary")
(2) Joseph Bloggs of [Address] ("New Beneficiary 1")
(3) Emily Bloggs of [Address] ("New Beneficiary 2")
Together referred to as "the Parties".
BACKGROUND
A. Arkwright Bloggs ("the Deceased") died on 1 January 2026 leaving a Will dated 1 January 1990 ("the Will").
B. Under the terms of the Will, the Current Beneficiary became entitled to a 50% share of the Deceased's property and a 50% share of the residue of the estate.
C. The Current Beneficiary's share of the estate residue, excluding the property interest, amounted to £200,000.
D. The Current Beneficiary wishes to vary part of that entitlement in accordance with the provisions of this Deed.
OPERATIVE PROVISIONS
1. Definitions
In this Deed:
"Will" means the Will of the Deceased dated 1 January 1990.
"Gift of Money" means the sum of £100,000 forming part of the Current Beneficiary's entitlement under the Will.
2. Confirmation of Entitlement
2.1 Under the terms of the Will, the Current Beneficiary became entitled to a share of the residue of the Deceased's estate.
2.2 No previous Deed of Variation affects the Gift of Money which is the subject of this Deed.
3. Variation
3.1 By this Deed, the Current Beneficiary irrevocably varies and redirects the Gift of Money so that the Will shall take effect as if the Gift of Money had been left by the Deceased as follows:
(a) £50,000 to New Beneficiary 1 absolutely; and
(b) £50,000 to New Beneficiary 2 absolutely.
3.2 The New Beneficiaries shall be treated for all purposes as having become entitled to their respective shares of the Gift of Money from the date of the Deceased's death.
4. No Consideration
This Deed is made voluntarily and no consideration in money or money's worth has been given or will be given by any person in connection with the variation effected by this Deed.
5. Tax Election
The Parties intend that the provisions of:
- section 142(1) of the Inheritance Tax Act 1984; and
- section 62(6) of the Taxation of Chargeable Gains Act 1992,
shall apply to the variation effected by this Deed.
EXECUTION
IN WITNESS WHEREOF the Parties have executed this Deed on the date first written above.
SIGNED AS A DEED by
Name: Fred Bloggs
Signature: ___________________________
Date: _______________________________
In the presence of:
Witness Name: _______________________
Witness Signature: ___________________
Witness Address: _____________________
Witness Occupation: _________________
Comments
-
Do you mean you will not be acting on the deed at this time? Or are you keeping it there with your will for information only? I'm not sure what the value of this is as at the time of your death your finances will be looked at and anything you've already "given away" via the deed will not be visible to your executors.
Is you estate so valuable that IHT is a possibility? Few people relatively have so much to be assessed. Are you married? This could change the IHT that might be payable.
If you are unlikely to be in IHT territory and you "give away" a substantial amount deprivation of assets might be an issue if you should need the money to support you at some future date.
I’m a Forum Ambassador and I support the Forum Team on Debt Free Wannabe, Old Style Money Saving and Pensions boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com. All views are my own and not the official line of MoneySavingExpert.
Click on this link for a Statement of Accounts that can be posted on the DebtFree Wannabe board: https://lemonfool.co.uk/financecalculators/soa.php
Check your state pension on: Check your State Pension forecast - GOV.UK
"Never retract, never explain, never apologise; get things done and let them howl.” Nellie McClung
⭐️🏅😇🏅🏅🏅🏅🏅🏅0 -
The document looks OK to me but I am no expert.
With regard to the house are you planning to live in it? If you are how does your brother benefit from that part of his inheritance?
0 -
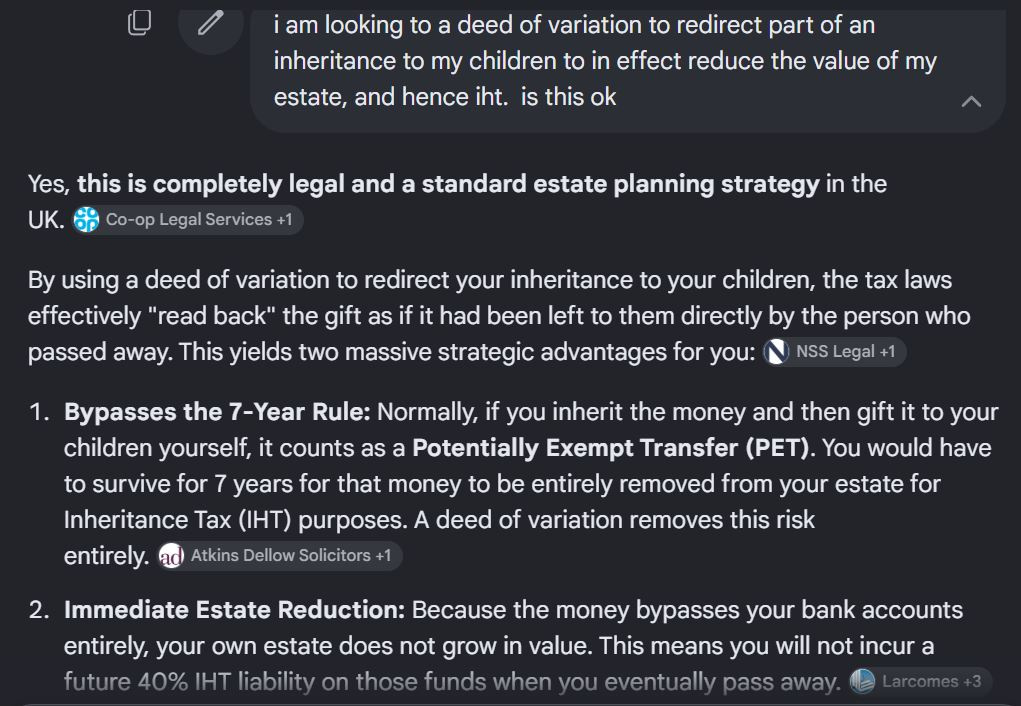
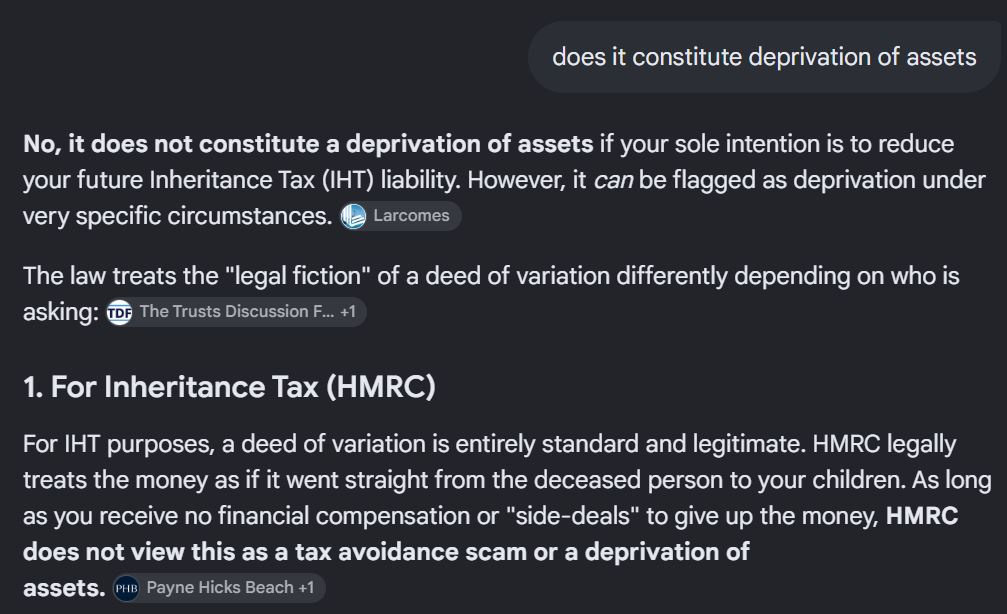
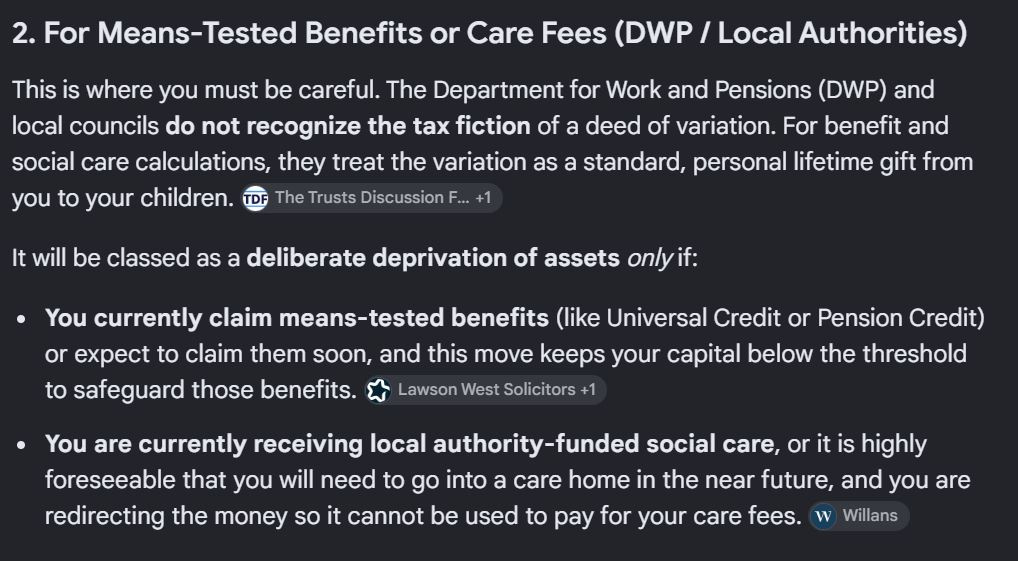
This is what AI tells me.
The house will be sold, so my brother is not affected in anyway by this deed
0 -
In your opening post you said
My 50% share of the property would remain vested in me, so that I would retain the benefit of the Residence Nil Rate Band (RNRB)
Sorry I rather misinterpreted that as retaining the RBRB for your estate rather than your parent’s estate which was the reason for my question.
If your were inclined to pass more of the estate to your children it would not impact the RNRB because the whole estate would still be passed to direct descendants.0 -
ah, that's interesting I didn't realise that, from gov.uk:-
Who is a direct descendent
For residence nil rate band purposes the direct descendant is:
- a child, grandchild or other lineal descendant
- a spouse or civil partner of a lineal descendant (including their widow, widower or surviving civil partner)
This also includes:
- a child who is, or was at any time, their step-child
- their adopted child
- a child fostered at any time by them
- a child where they’re appointed as a guardian or special guardian when the child is under 18
0 -
I am not going to comment on your deed of variation. Here is HMRC's checklist if you have not already seen it.
Other people have commented on the RNRB so I won't do that.
Actually, why not, let's give it a go:
- If I was doing it, I would ignore the "deed" bit of a deed of variation and just do a simple letter. But that is because I'm lazy and it just needs to be in writting. I think doing it by Whatsapp may be a bit too gauche for me.
- I'm also lazy about writing out two sets of words (that may or may not mean the same thing as it confuses me). So I'd probably not mix-and-match 50% of the residuary and £200,000 because it will be confusing if there are some unexpected utility bills / interest received and I as I'm work shy, I don't like confusion. If I must have both, I'd probably add an "estimated" to the £200,000 but I know nothing about the estate.
- It says the kids are parties to the deed, but they are not. And you haven't got a signature space for them either. As a letter, I would just sign it "Love and kisses, Fred Bloggs" but my name is not Fred, so may be now. If you want to go the deed route, SIGNED and DELIVERED AS A DEED by Fred Bloggs in the presence of … is probably more typical.
- I'm also left wondering if there is a typo (£200,000 is mentioned but only 2x £50,000 is being given away),
- Clause 3.1 has some great words but it is inaccurate. This is a true fiction for CGT and IHT but not for any other purpose (like income tax, estate administration or every other legal purpose).
- The CGT election is unnecessary for cash, but lawyers charge per token so why not.
If I was to talk to a solicitor about it, I am sure they would want a deed on posh paper because it looks more impressive.
Oh, and in relation to:
which I intend to keep with, and as supporting evidence for, my Will.
By all means keep it a copy with your will, but it should go the executors of the will of the deceased. It would also makes sense to keep a copy of the completed HMRC checklist (and anything else you fancy).
0 -
The OPs executors need to be aware of the DoV should they die within 7 years of their parent’s death. The current executors only really need to know if it impacts IHT on the parent’s estate.
2 -
The current executors only really need to know if it impacts IHT on the parent’s estate.
Or if the estate has not yet been distributed.
0 -
I had a DOV drawn up by a solicitor when dealing with my mother's estate so that some of my inheritance went to my children.
From looking at that I would say
Under Background leave out item C. Not necessary.
2. Confirmation of Entitlement - don't think this section is necessary.
Under the Variation bit I think you should say that the £50ks are free of inheritance tax (even if the estate is not liable).
Also all parties to the deed should sign and have their signatures witnessed, not just one.
0 -
One thing that hasn't come up: as long as the deed carries the s142 IHTA statement (your draft looks to, going by the HMRC checklist), the £200k is treated as passing straight from your parents to your children. It isn't a gift from you at all for IHT, so there's no seven year clock on it and nothing your own executors ever need to list. The one thing that breaks it is consideration - if the kids give you anything back for it, the reading back fails.
Practically, only the person giving something up has to sign, so that's you, not the children. It has to be signed within two years of the death. Because it doesn't increase the IHT on your parents' estate it doesn't need to go to HMRC at all, it just sits with the estate papers. If the cash hasn't been paid out yet the executors can pay your children directly off the deed, which keeps the trail clean. If it's already come to you the deed still works, but move the money promptly and keep a note of the transfer. Cash means there's no CGT election to worry about either.
1








Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.5K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.1K Work, Benefits & Business
- 605.6K Mortgages, Homes & Bills
- 179K Life & Family
- 263.4K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards