We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
CCJ from nowhere



To start with I want to say I've read the newbie guide, but it doesn't explain if I have any next steps in my particular predicament.
I just yesterday received a notice of debt recovery - unpaid county court judgement from DCBL.
This is the first notice I have heard about any CCJ to my name, and I have had some issues before with being slow to pay parking tickets and ended up getting letters from bailiffs. I didn't know what it was referring to so I was very anxious and called them up to ask them about it immediately. They refused to provide any kind of detail on what the judgement was and suggested I do a credit check to confirm it, which I subsequently did and confirmed was active.
The letter wasn't actually delivered to my house even, and to my neighbours (though the listed address is correct), and so my neighbour, who I have never met before, brought it out to me.
The listed court judgement date is 25/11/2025, and I received the letter on 07/09/2026. The letter says that "if I pay in full within 1 month of receiving the judgement I can have it removed. So I thought "no bother", and paid it immediately. I then went away, and about an hour later re-read the letter and it made me start doubting the wording, as the wording of "within 1 month of receiving the judgement" stood out.
The incident in question I believe was a work visit to a hotel in England which is 600 miles from my house (I live in scotland). The car it would have happened to, I had struggled to get a new log book due to not being able to find the VIN number and the car wasn't driveable to get help with. DVLA Suggested the best thing I do is scrap it (which suited me as I wanted a new vehicle anyway). I did that, but it's meant that these letters seem to have been sent to my old address.
I ended up finding the newbie guide after already pa, and it says that it's common for dcbl to send the letters to the wrong address and magically find it when its too late.
I was hoping for some clarification on how to proceed. Can I still fill out an n244 request and have it set aside? I assume it's too late for troublemakers letter as I have already "admitted" guilt, but I very much feel tricked by the wording on the letter. If they had known that the judgement was NINE MONTHS AGO, how is it legal to include ambiguous text claiming if I pay in 30 days it will be removed.
Comments
-
To Clarify a few things in my post:
At the time of the alleged incident, I lived in England.
I moved, I want to say, a year later? And updated my driving license etc to my new house in Scotland.
This is the very first time I have ever heard or received anything about this.1 -
Sorry mate. You paid it and now it will show CCJ - Satisfied on your report for the next 6 years. You've lost your chance to erase it.
It's an insane system. Once you pay it should be wiped. But that's not the case I'm afraid.I would look at each and every credit agency in a month's time and see if it a) marked as satisfied and b) if the record is missing from any of them.
If, by some chance the CCJ isn't on there, make a note and only apply for credit if you need to where a lender only checks that credit agency.
2 -
So it's perfectly valid for DCBL to send out misleading letters? That is actually insane.
0 -
Paying it doesn't necessarily prevent you applying for the judgment to be set aside.
First thing I would do is contact the court, not DCBL, and get the claim number, claimant, Particulars of Claim and, importantly, the address at which the claim was served. You need to know exactly what happened before spending £321 on an N244 application.
If the claim was served at an old address there may be grounds for a set-aside. Whether it is automatic or discretionary depends on whether service was actually valid and the circumstances. If the claimant had reason to believe you no longer lived at the address used, the Civil Procedure Rules require them to take reasonable steps to establish your current address.
If you are going to apply, do it promptly now that you know about the judgment. For a discretionary set-aside the court expressly considers promptness and whether you have a real prospect of successfully defending the original claim.
Also, updating your driving licence does not update the V5C. They are separate DVLA records, which may explain how the parking company originally obtained the old address.
Finally, if the DCBL letter really says payment “within one month of receiving the judgment” will get it removed, that is very poor wording. The rule is payment in full within one month of the DATE OF JUDGMENT. Paying it nine months later will normally only result in the CCJ being marked satisfied, not removed.
So: obtain the court papers first, establish where the claim was served and why, then decide whether an N244 application is justified.
1 -
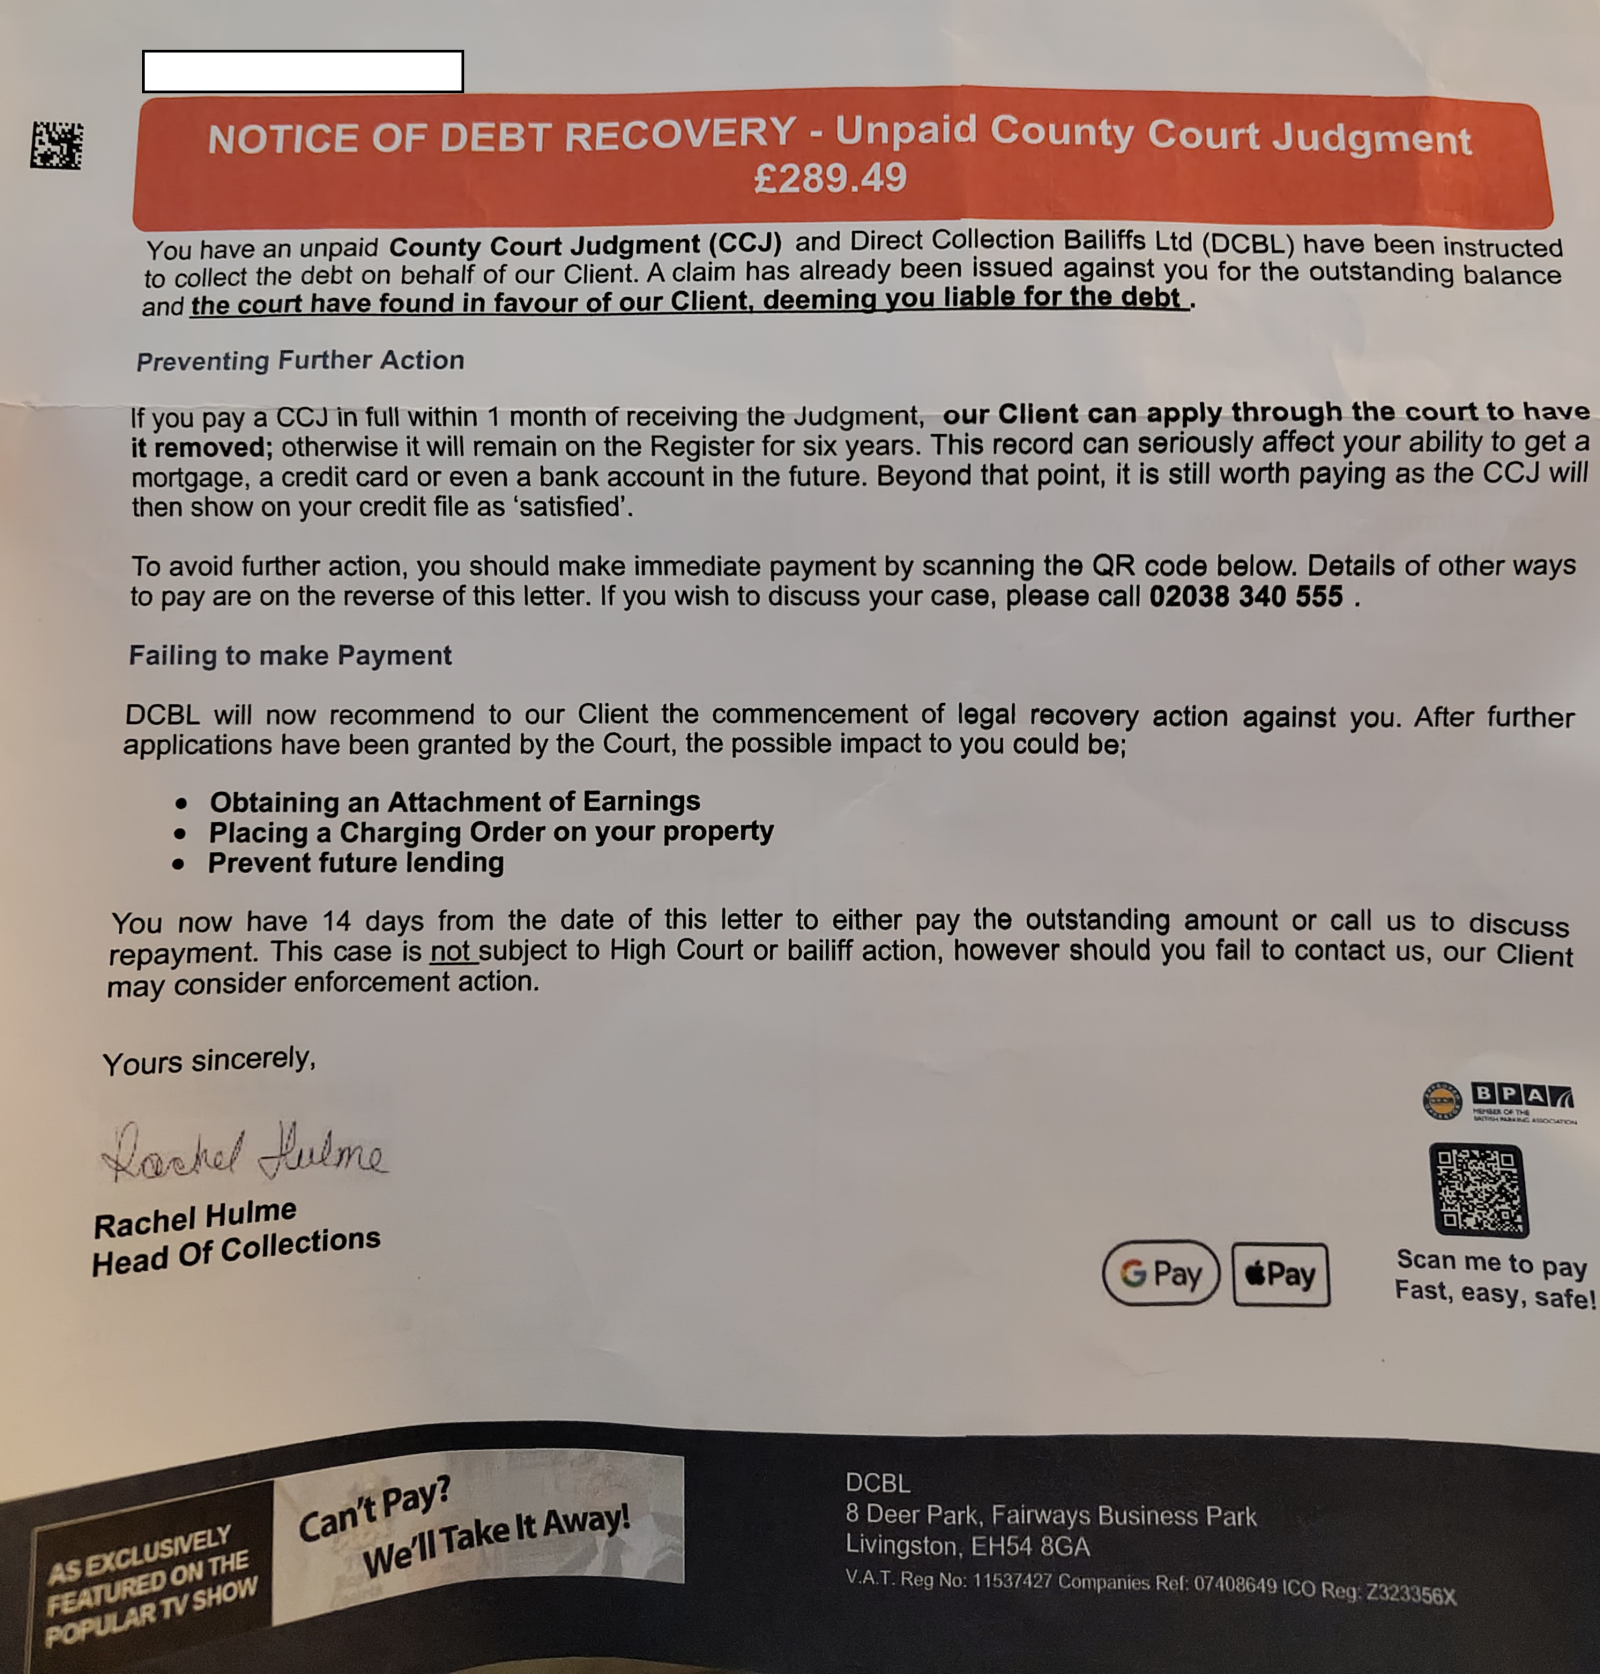
This is the letter received, It seems very misleading. How Do I even find out what court it is?The "call us about your case" sentence is a lie because they refused to provide any information. In additiona, the court is probably 450 miles away from me. To get it to set aside, does that mean I would need to attend court in person?
0 -
If its a default Judgment, contact the CNBC in Northampton, not an actual court per se
If you pay for a set aside, you wont be travelling to Northampton
1 -
Ok, I've got that information now. What's my next steps? Can you guys help me with the actual form? Is there a template I can use here, or am I just winging it?
Claimant: PARKINGEYE LTD
Claimant solicitor: DCB LEGAL LTD (7451)
Judgment amount: 289.49
Particulars of claim:
1. THE DEFENDANT (D) IS INDEBTED TO THE CLAIMANT (C) FOR A PARKING CHARGE (PC) ISSUED TO VEHICLE (REDACTED) - AT (REDACTED)
2. THE DATE OF CONTRAVENTION IS 12/12/2024 AND THE D WAS ISSUED WITH A PC BY THE CLAIMANT
3. THE DEFENDANT IS PURSUED AS THE DRIVER OF THE VEHICLE FOR BREACH OF THE TERMS ON THE SIGNS (THE CONTRACT). REASON: VEHICLE REMAINED ON PRIVATE
PROPERTY IN BREACH OF THE PROMINENTLY DISPLAYED TERMS AND CONDITIONS.4. IN THE ALTERNATIVE THE DEFENDANT IS PURSUED AS THE KEEPER PURSUANT TO POFA 2012, SCHEDULE 4. AND THE CLAIMANT CLAIMS
1. £170.00 BEING THE TOTAL OF THE PC AND DAMAGES.
2. INTEREST AT A RATE OF 8.00% PER ANNUM PURSUANT TO S.69 OF THE COUNTY COURTS ACT 1984 FROM THE DATE HEREOF AT A DAILY RATE OF £0.03 UNTIL JUDGMENT OR SOONER PAYMENT.
3. COSTS AND COURT FEES
I mean I think I could have clearly challenged it, as it was dark when I arrived, and I saw no signs, nor notice to there being parking restrictions. Nor did the hotel tell me. But alas, that's all by the by now. I just want to not have a CCJ.
0 -
What was the date of issue of the claim form and to which address was it sent? Don't show your actual address but something like "my old address", "my current address". What was the date of the judgment? Was it a default judgment for failing to respond to the N1SDT claim form? Why did you not respond, didn't receive it or some other reason? You will need a very good reason for applying for a set-aside as judges don't like credit cleansing. If you get the set-aside granted, you have a good defence as the POC were weak and you could use Chan & Akande.
1 -
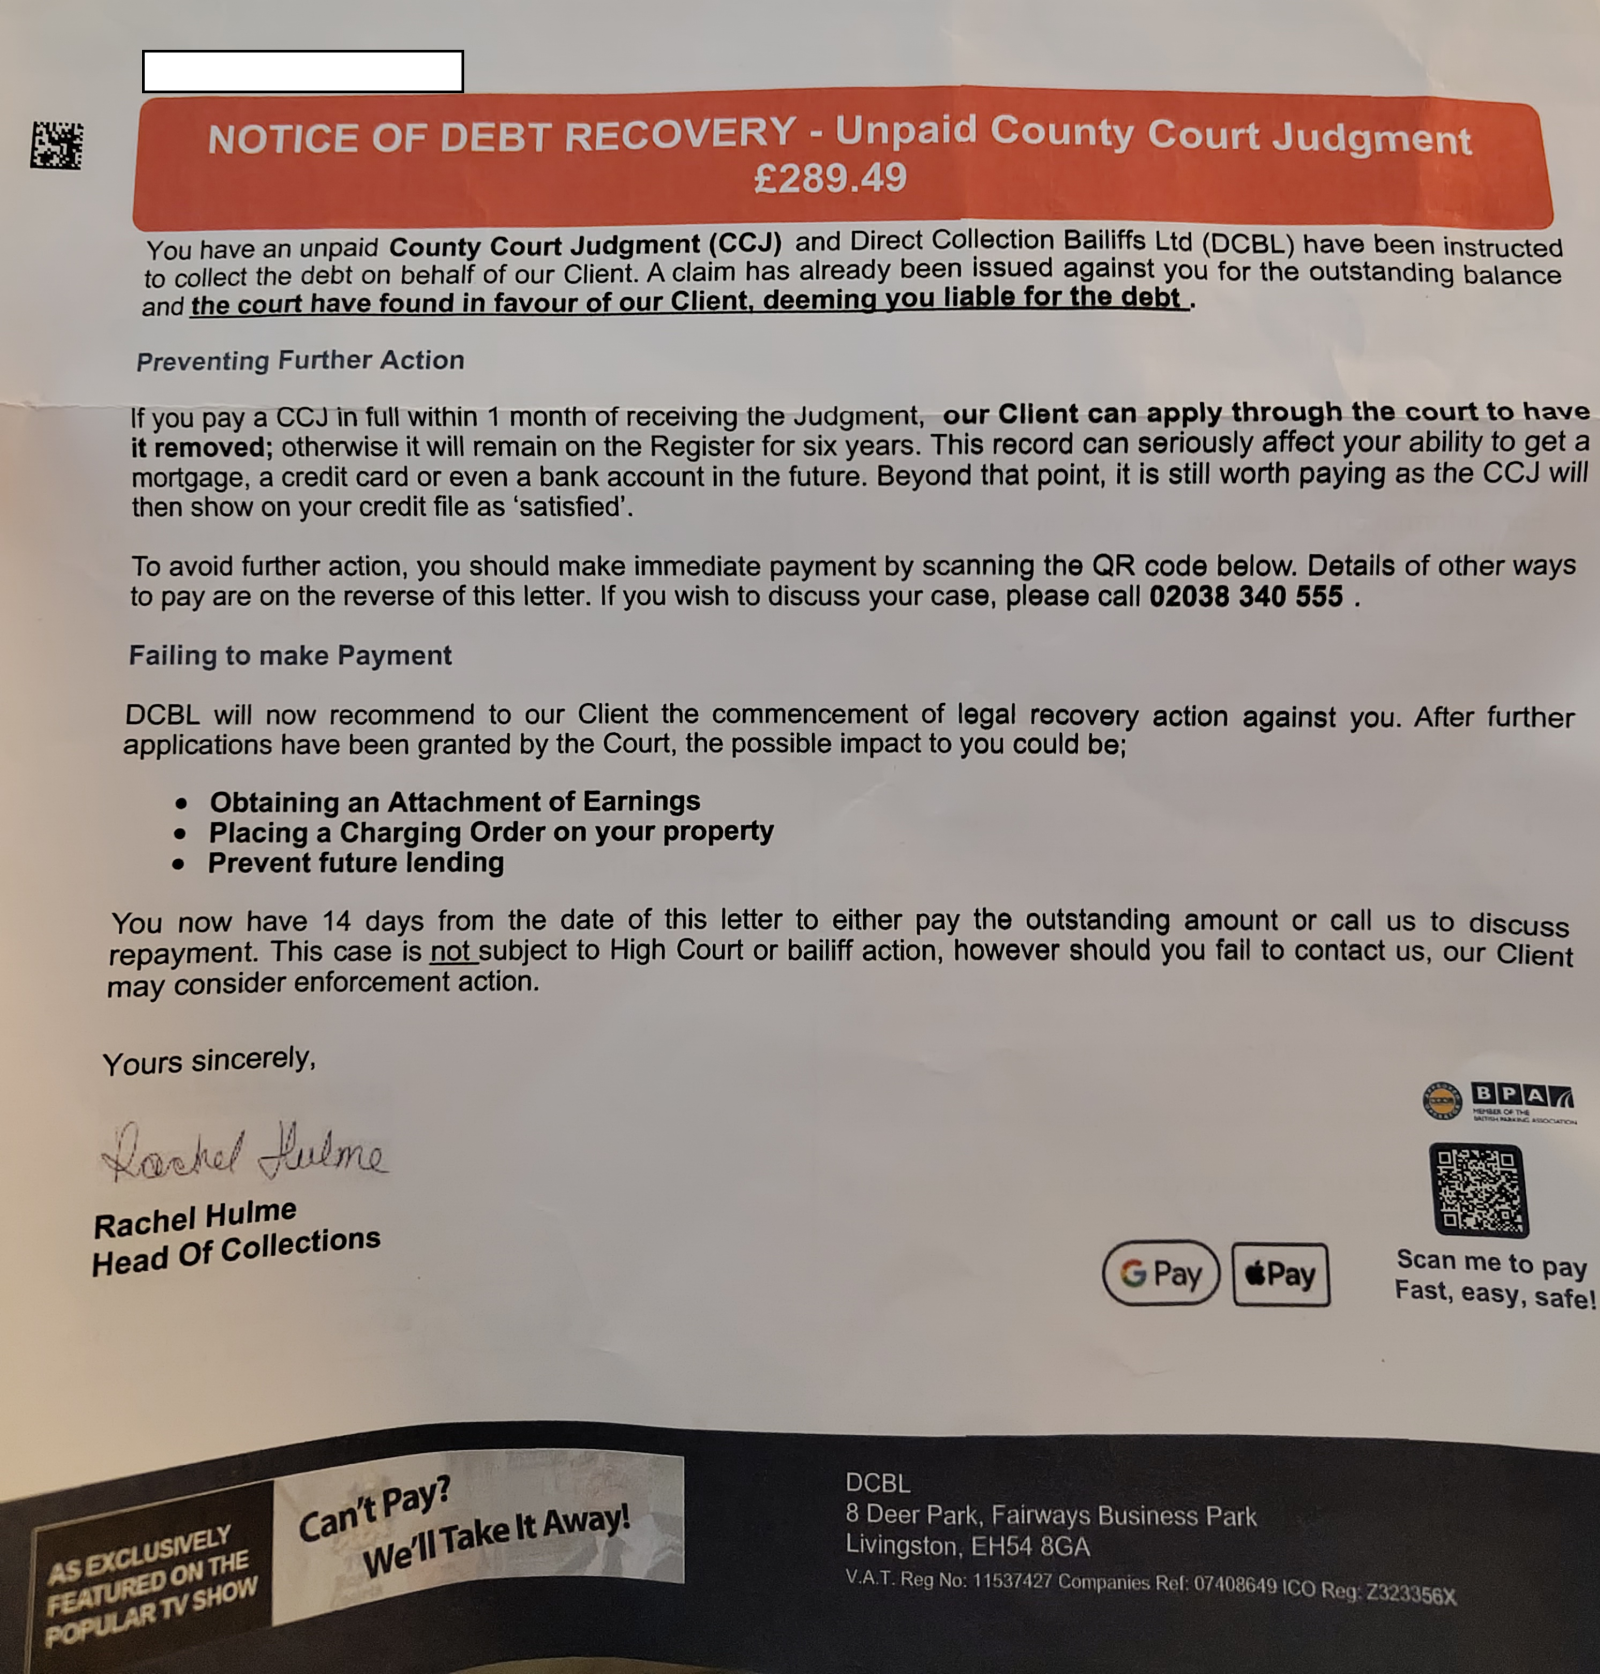
"how is it legal to include ambiguous text claiming if I pay in 30 days it will be removed."@Imaverysaddonkey it's not legal if the wording is likely to mislead consumers.
PRIVATE 'PCN'? DON'T PAY BUT DON'T IGNORE IT (except N.Ireland).
CLICK at the top or bottom of any page where it says:
Home»Motoring»Parking Tickets Fines & Parking - read the NEWBIES THREAD0 -
i've sent you a pm @Imaverysaddonkey
PRIVATE 'PCN'? DON'T PAY BUT DON'T IGNORE IT (except N.Ireland).
CLICK at the top or bottom of any page where it says:
Home»Motoring»Parking Tickets Fines & Parking - read the NEWBIES THREAD0






Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards