We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Help with limited savings

Hi, I have used up my ISA allowance and the amount I put into my pension for this tax year but have 40k to invest. I am a 40% tax payer and know if I open a savings account I will be lieable to heavy tax after £500. Martin Lewis discusses Premium Bonds but they sound perhaps not the way.
My questions are: Do Premium bonds gain interest even if you don't 'win' and if so would it be better to put 40k in premium bonds or a savings account if I nam a higher tax rate payer?
Also, as it is 40k, and I cant affored to lock it away for long (maybe a year or two at very most), would it just be better to put it in a fixed savings account and pay the tax on all over £500?
I find it all quite stressful so c ant cope with anything to intricate either. Theother slight worry is I am 67 and if I died woyuuld my chiulkdren be entitled to the premium bond money and the savings money or is one the better option ?
Thank you for ytour help.
Comments
-
With £40k to invest, you have something like an 80% chance of winning between 2.6-5.6% per year, so this will likely be more than you'd get from taxable savings after tax. The more you have, the less likely you'll face an extreme outcome like zero, so that counts in your favour. It is possible to win nothing, so there is not underlying "interest rate" if you are unlucky.
As to inheritance, it's not materially different whether the money is in premium bonds vs a savings account. In practice, NS&I may drag their heels more, but there is no difference in entitlement.
0 -
No premium bonds only pay out on winnings so there is no interest on Premium Bonds.
The premium bonds, savings money and ISA would all form part of your estate and pass under your will (assuming you have one). Your pension will also form part of your estate from next year but will generally be distributed outside of you will according to any expression of wishes you have given the pension company.
So any choice is really down to you. If you want a guaranteed return off the 40k I'd suggest you look at best savings, if you're happy to take a calculated chance then premium bonds.
0 -
You don't get interest in Premium Bonds. You might just get what they call wins, and these are tax free. The current average is 4.35%, but importantly, this is not guaranteed. A lot of holders get less than this rate, and a few are getting substantially more. It's pot luck, with relatively low win chances. Lots of HR tax payers are trying their luck, in pursuit of a big win.
If you die (67 seems young!!), Premium Bonds will be part of your estate, just like savings.Short duration gilts might be another option for you if tax avoidance is your key driver. The coupon (interest) is taxable income but capital gains are tax free. You would have to learn about gilts - not too difficult to do in principle but only you can tell whether you want to do this.
Your simplest and most predictable option is to swallow the tax, which won't be a huge sum in the current tax year for any savings you start now.Then put another £20k into an ISA on April 6 2027, and keep the rest in easy access accounts. You could also dabble with regular savers if you have the time and inclination, as they pay substantially better interest than a normal easy access account.1 -
Another option is low coupon gilts. The (small) coupons are taxed as interest but the big plus is that capital gains on these are tax free. You buy them below par (£100/£1) and at maturity receive £100/£1 per bond and so most of your gain is tax free.
You buy them via a stockbroker e.g., Scottish Widows Share Dealing (formerly iWeb) at £5 per trade and no ongoing account fees and no charge at maturity. If you want to you can sell them before maturity when the London Stock Exchange is open. If you do you might get less back than you paid but due to, 'pull to par' and given you're looking at short dated maturities you probably won't need to worry too much.
I've set the tax rate in the following website to 40%. The net returns don't look amazing - 3.8% to 4.2% - but compared to a savings account e.g., 4.5% - 40% = 2.7% they're not bad.
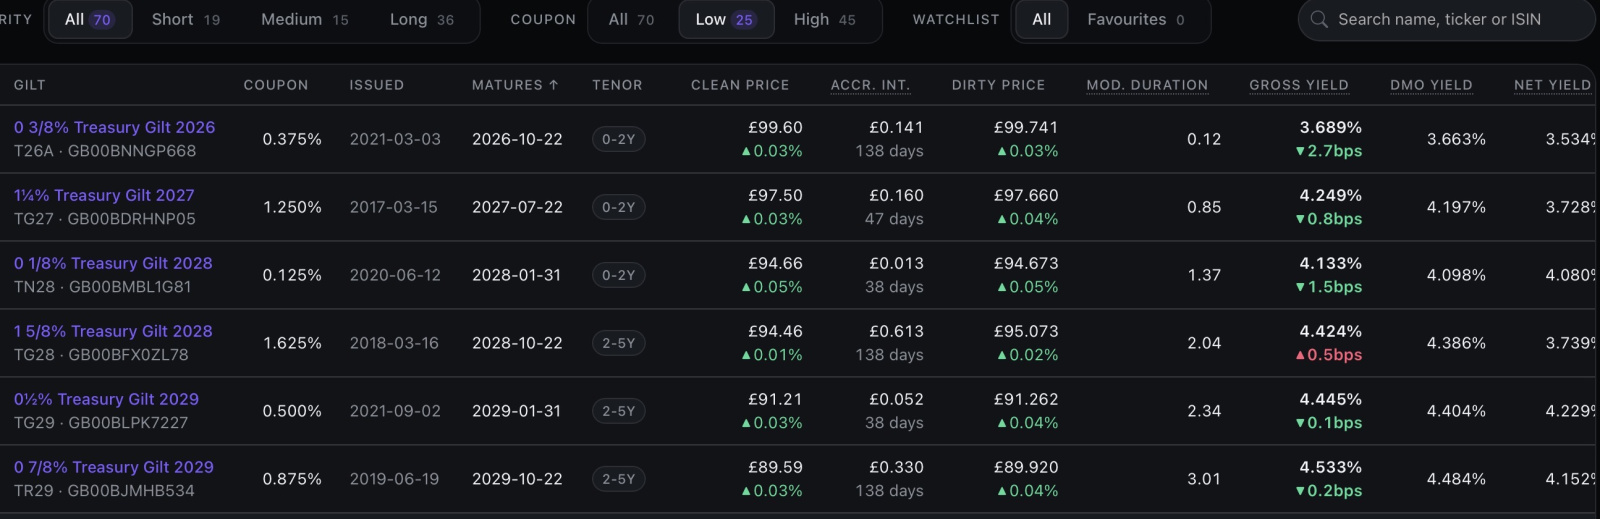
https://giltsyield.com/bond/?settlement_delay=T%2B1&tax_rate=400 -
If you find this kind of thing stressful, go for the simplest solution. You could:
- Go for premium bonds. Tax free, so that's beneficial for you. You could win absolutely nothing, but with £40,000 you're more likely to get a decent return. If you don't like the unpredictability then it might put you off premium bonds, but they sound like a good option for you.
- Choose the highest rate savings account. Yes, you'll pay tax on it, but it's better than paying 0% tax on £0 interest.
You'll be able to put the whole lot into ISAs within a couple of years which'll be completely tax free, so don't fret too much about the tax situation for now.
5 -
It might be worthwhile reading through the MSE articles for the options mentioned…
Premium Bonds:
Low coupon short term gilts:
For sure, it's a good idea to keep on subscribing the maximum to an ISA at the start of every new tax year. Then possibly Premium Bonds can be a reasonable choice for a higher rate tax payer that is already receiving some other savings interest to use up the £500 personal savings allowance, and prefers to keep things simple.
It was mentioned that the OP prefers not to cope with anything intricate, so the tax reporting requirements for gilts might not be their preference. In this respect Premium Bonds are really simple, because like ISAs there is no tax reporting required at all.
1 -
If you're 67 then money in a pension isn't locked away but if you're a 40% taxpayer then presumably you're working? Could you increase pension payments from work to bring your income back into lower rate band?
Remember the saying: if it looks too good to be true it almost certainly is.0










Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards