We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Things Got Worse - Struggling with priority debts and scared to lose my house




Hi everyone,
I posted here before about my credit card debts and got a lot of help. My situation has changed so much that I thought it would be better to start a new thread as the old thread was getting too long..
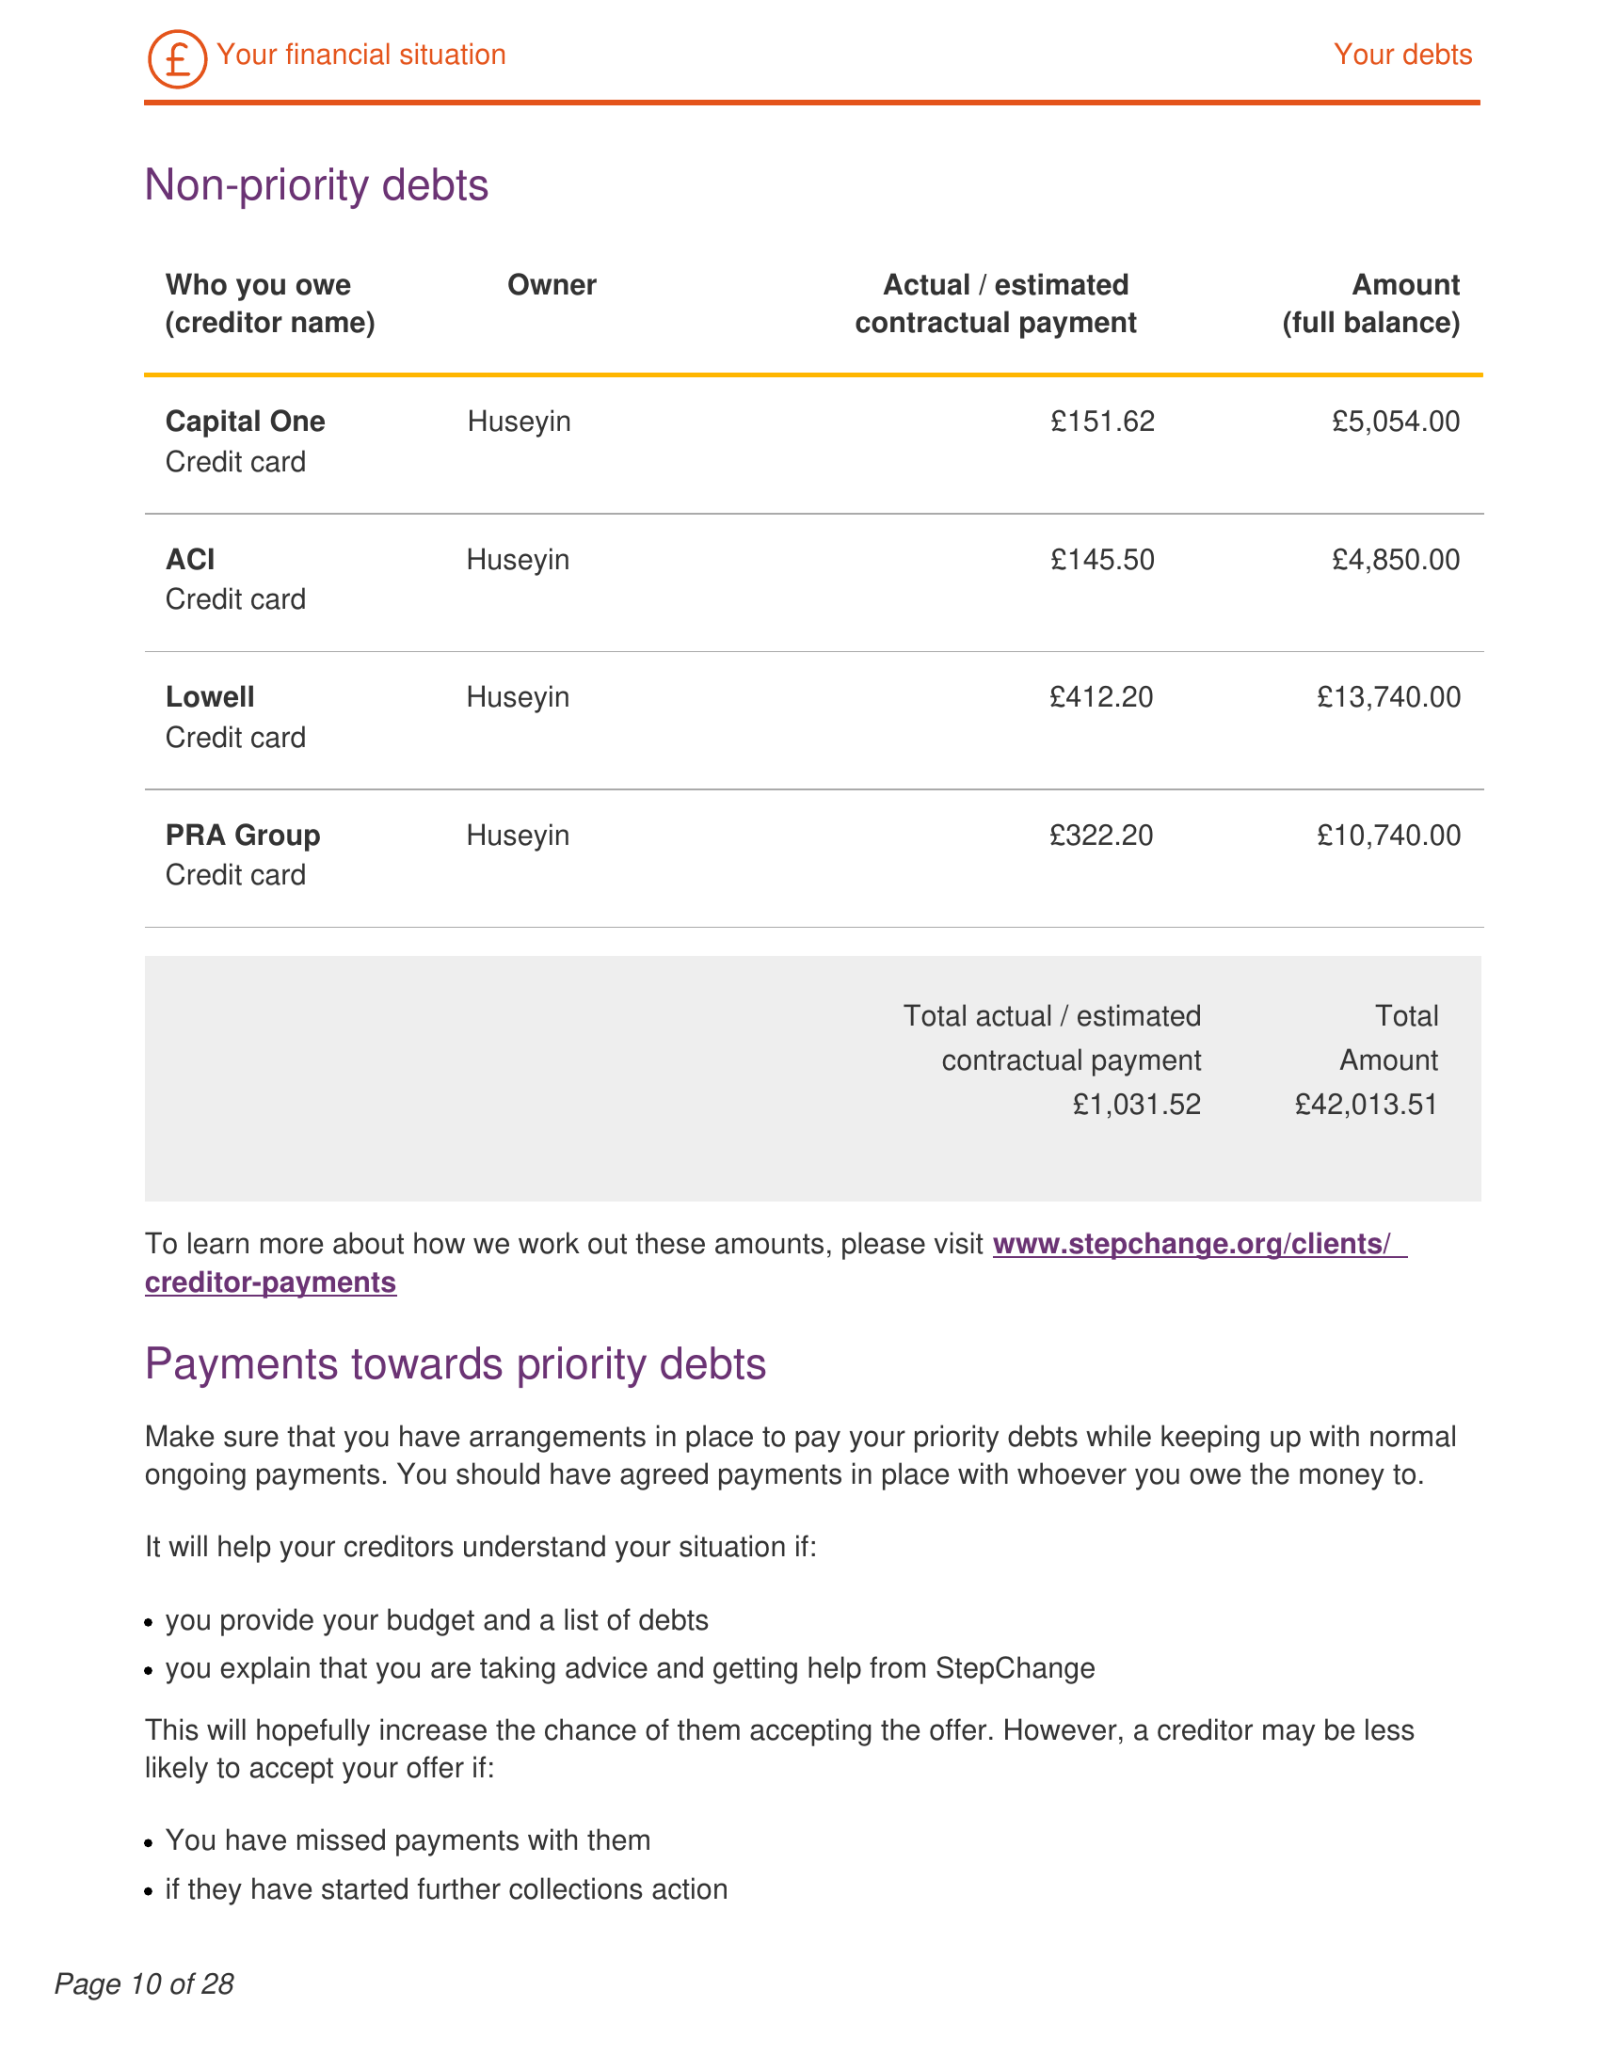
The strange thing is that the old credit card debts are now the least of my worries. Following the advice I got on here, I have now stopped the DMP payments to them. They have all defaulted and I am planning to offer token payments while I concentrate on the priority debts.
Looking back, I realise I was being stupid trying to keep everyone happy, especially the non-priority creditors. I’ve basically been shuffling money around from one place to another trying to keep everyone happy, until eventually there was nowhere left to shuffle it from and the !!!!!! hit the fan.
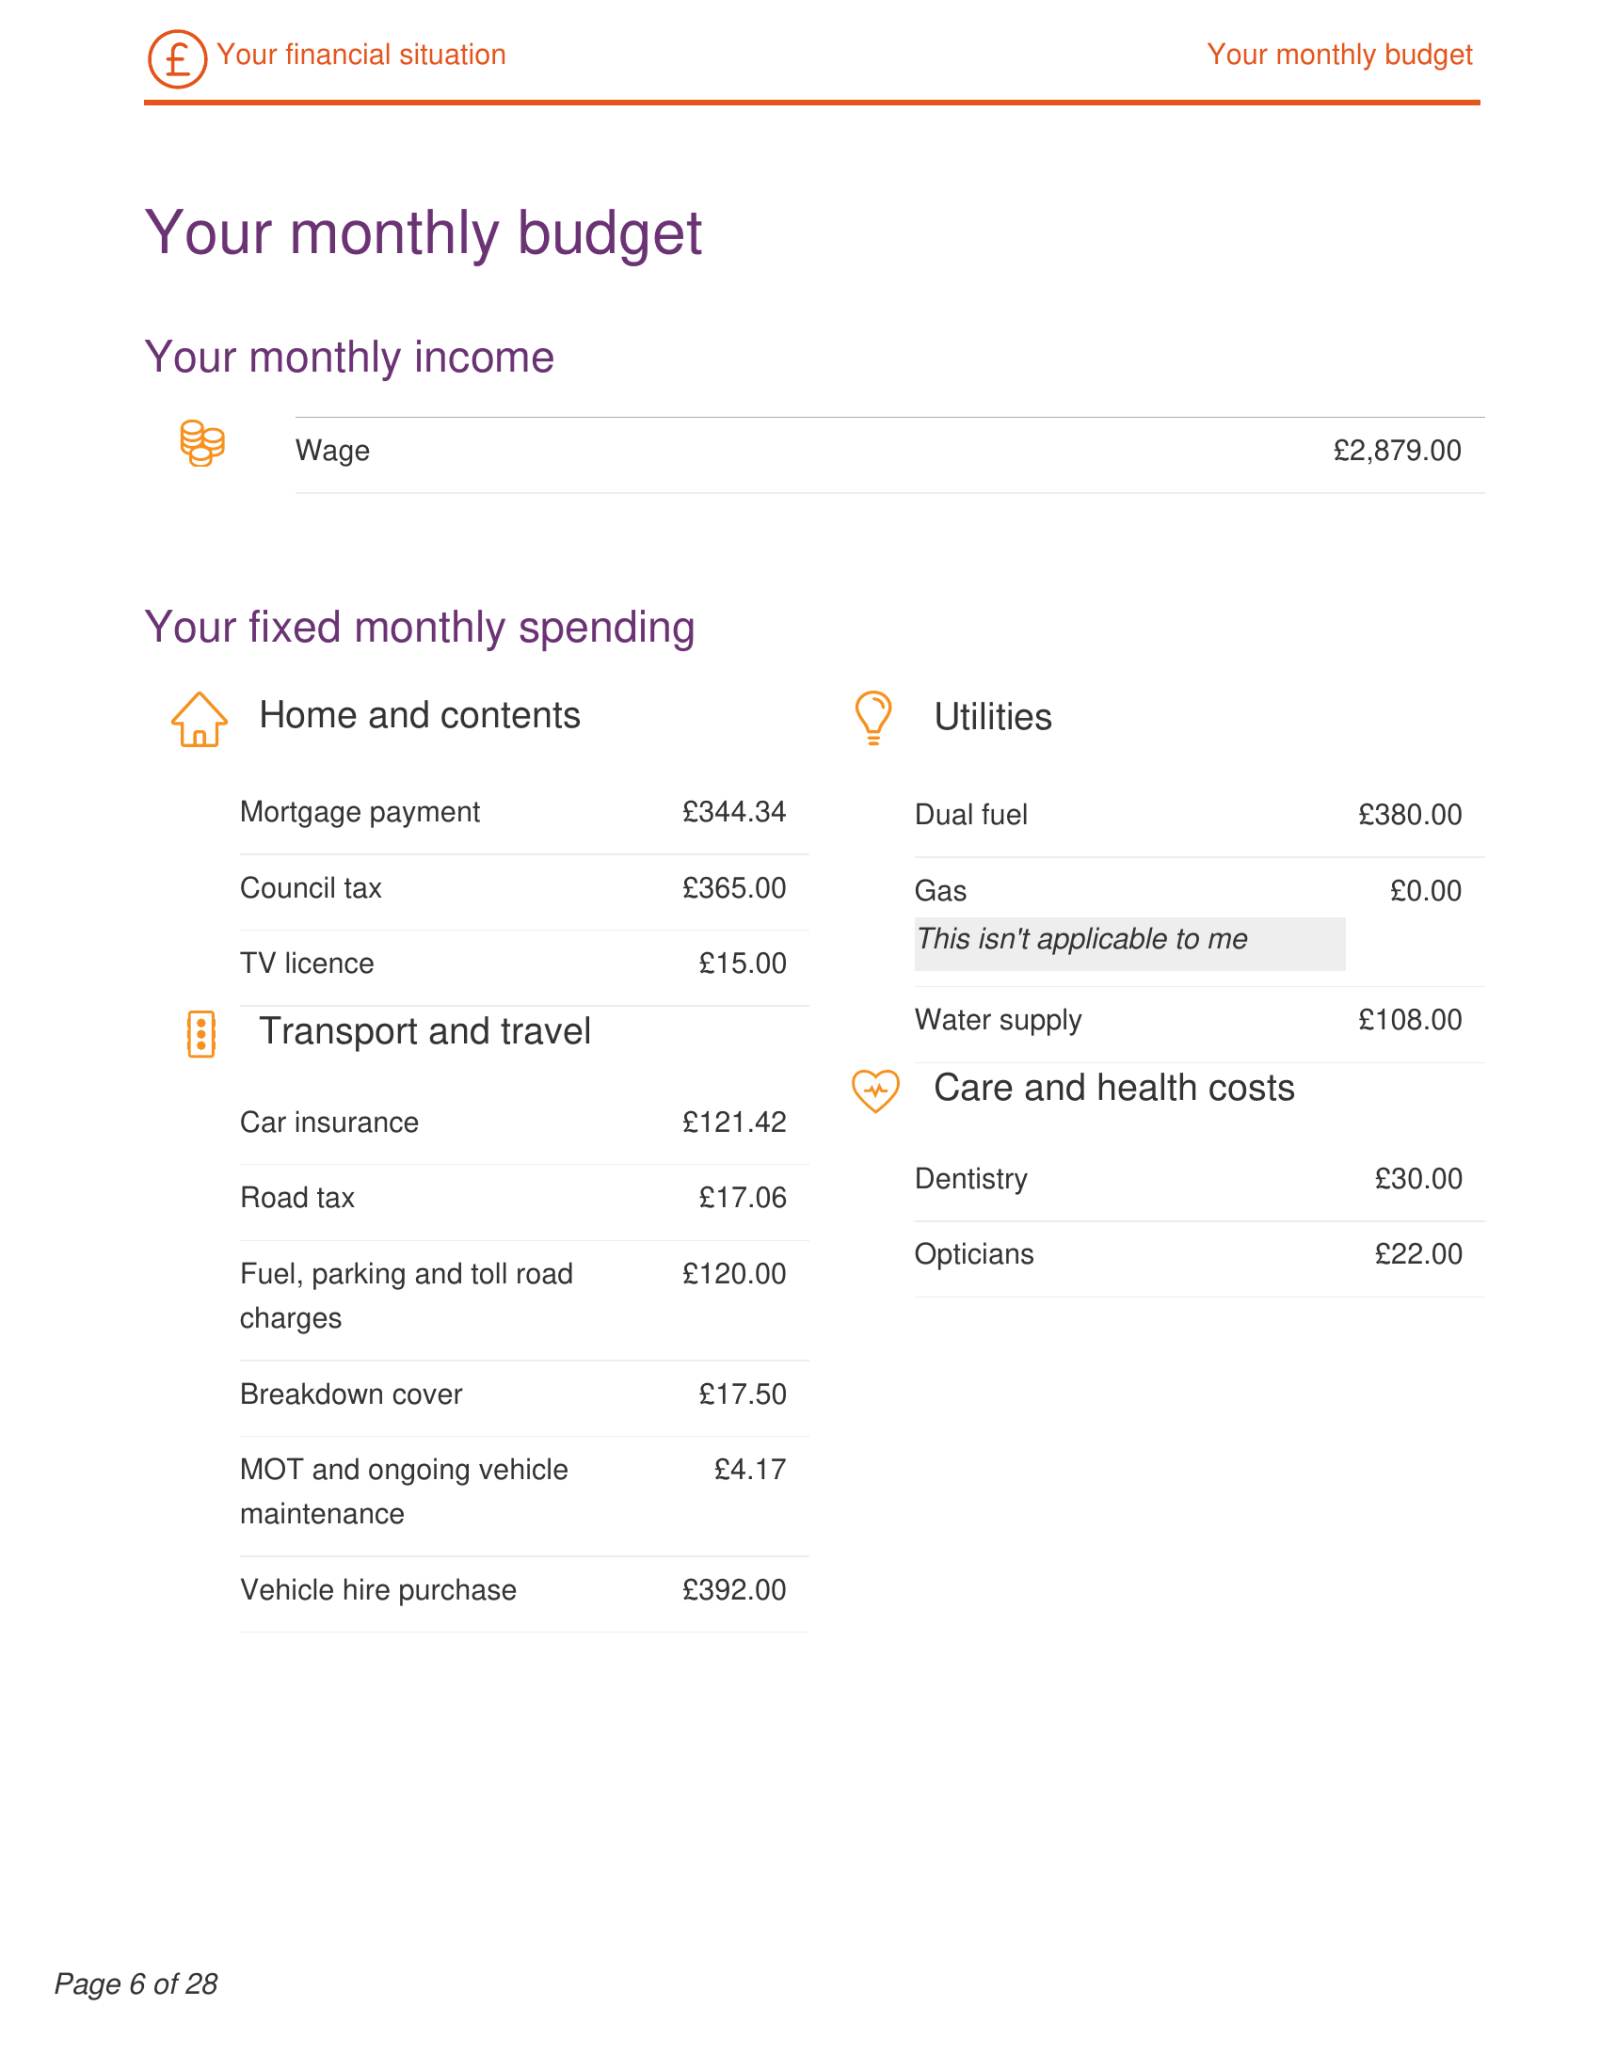
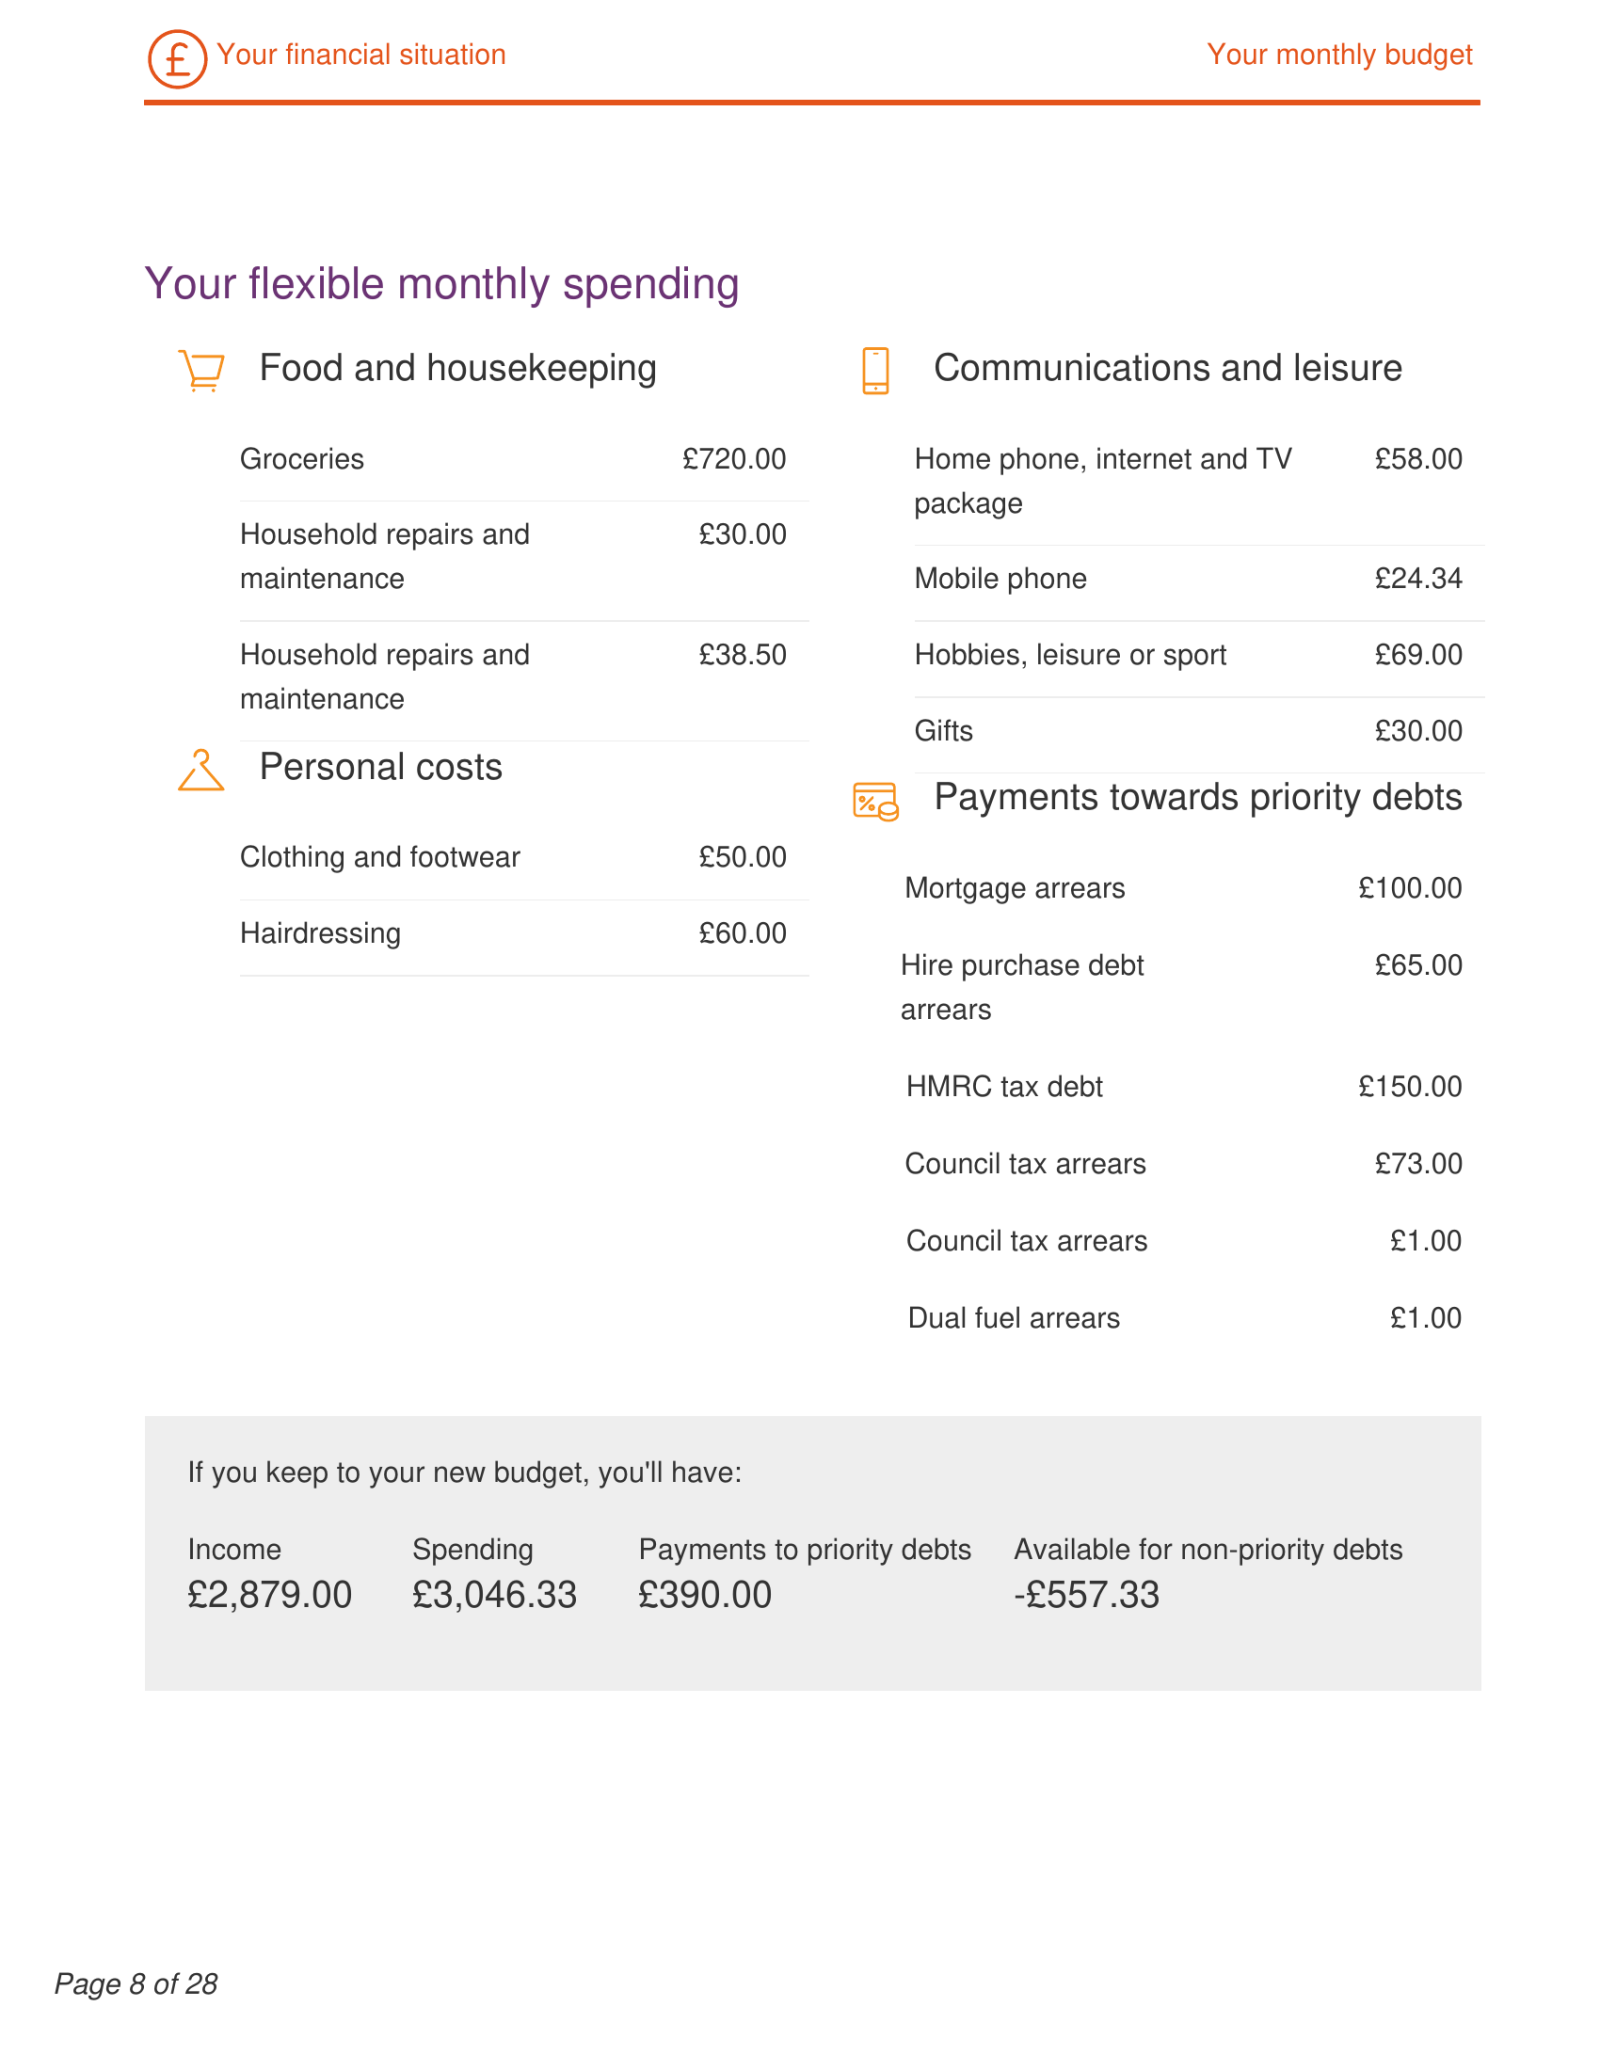
I have just completed a new StepChange income and expenditure. I have used an average household income of £2,879 per month, and the final budget shows a deficit of about £557 per month.
That explains what has been happening in real life. I haven’t actually been paying everything. I have kept the mortgage, car finance, HMRC and some other payments going, but OVO Energy and council tax have fallen behind.
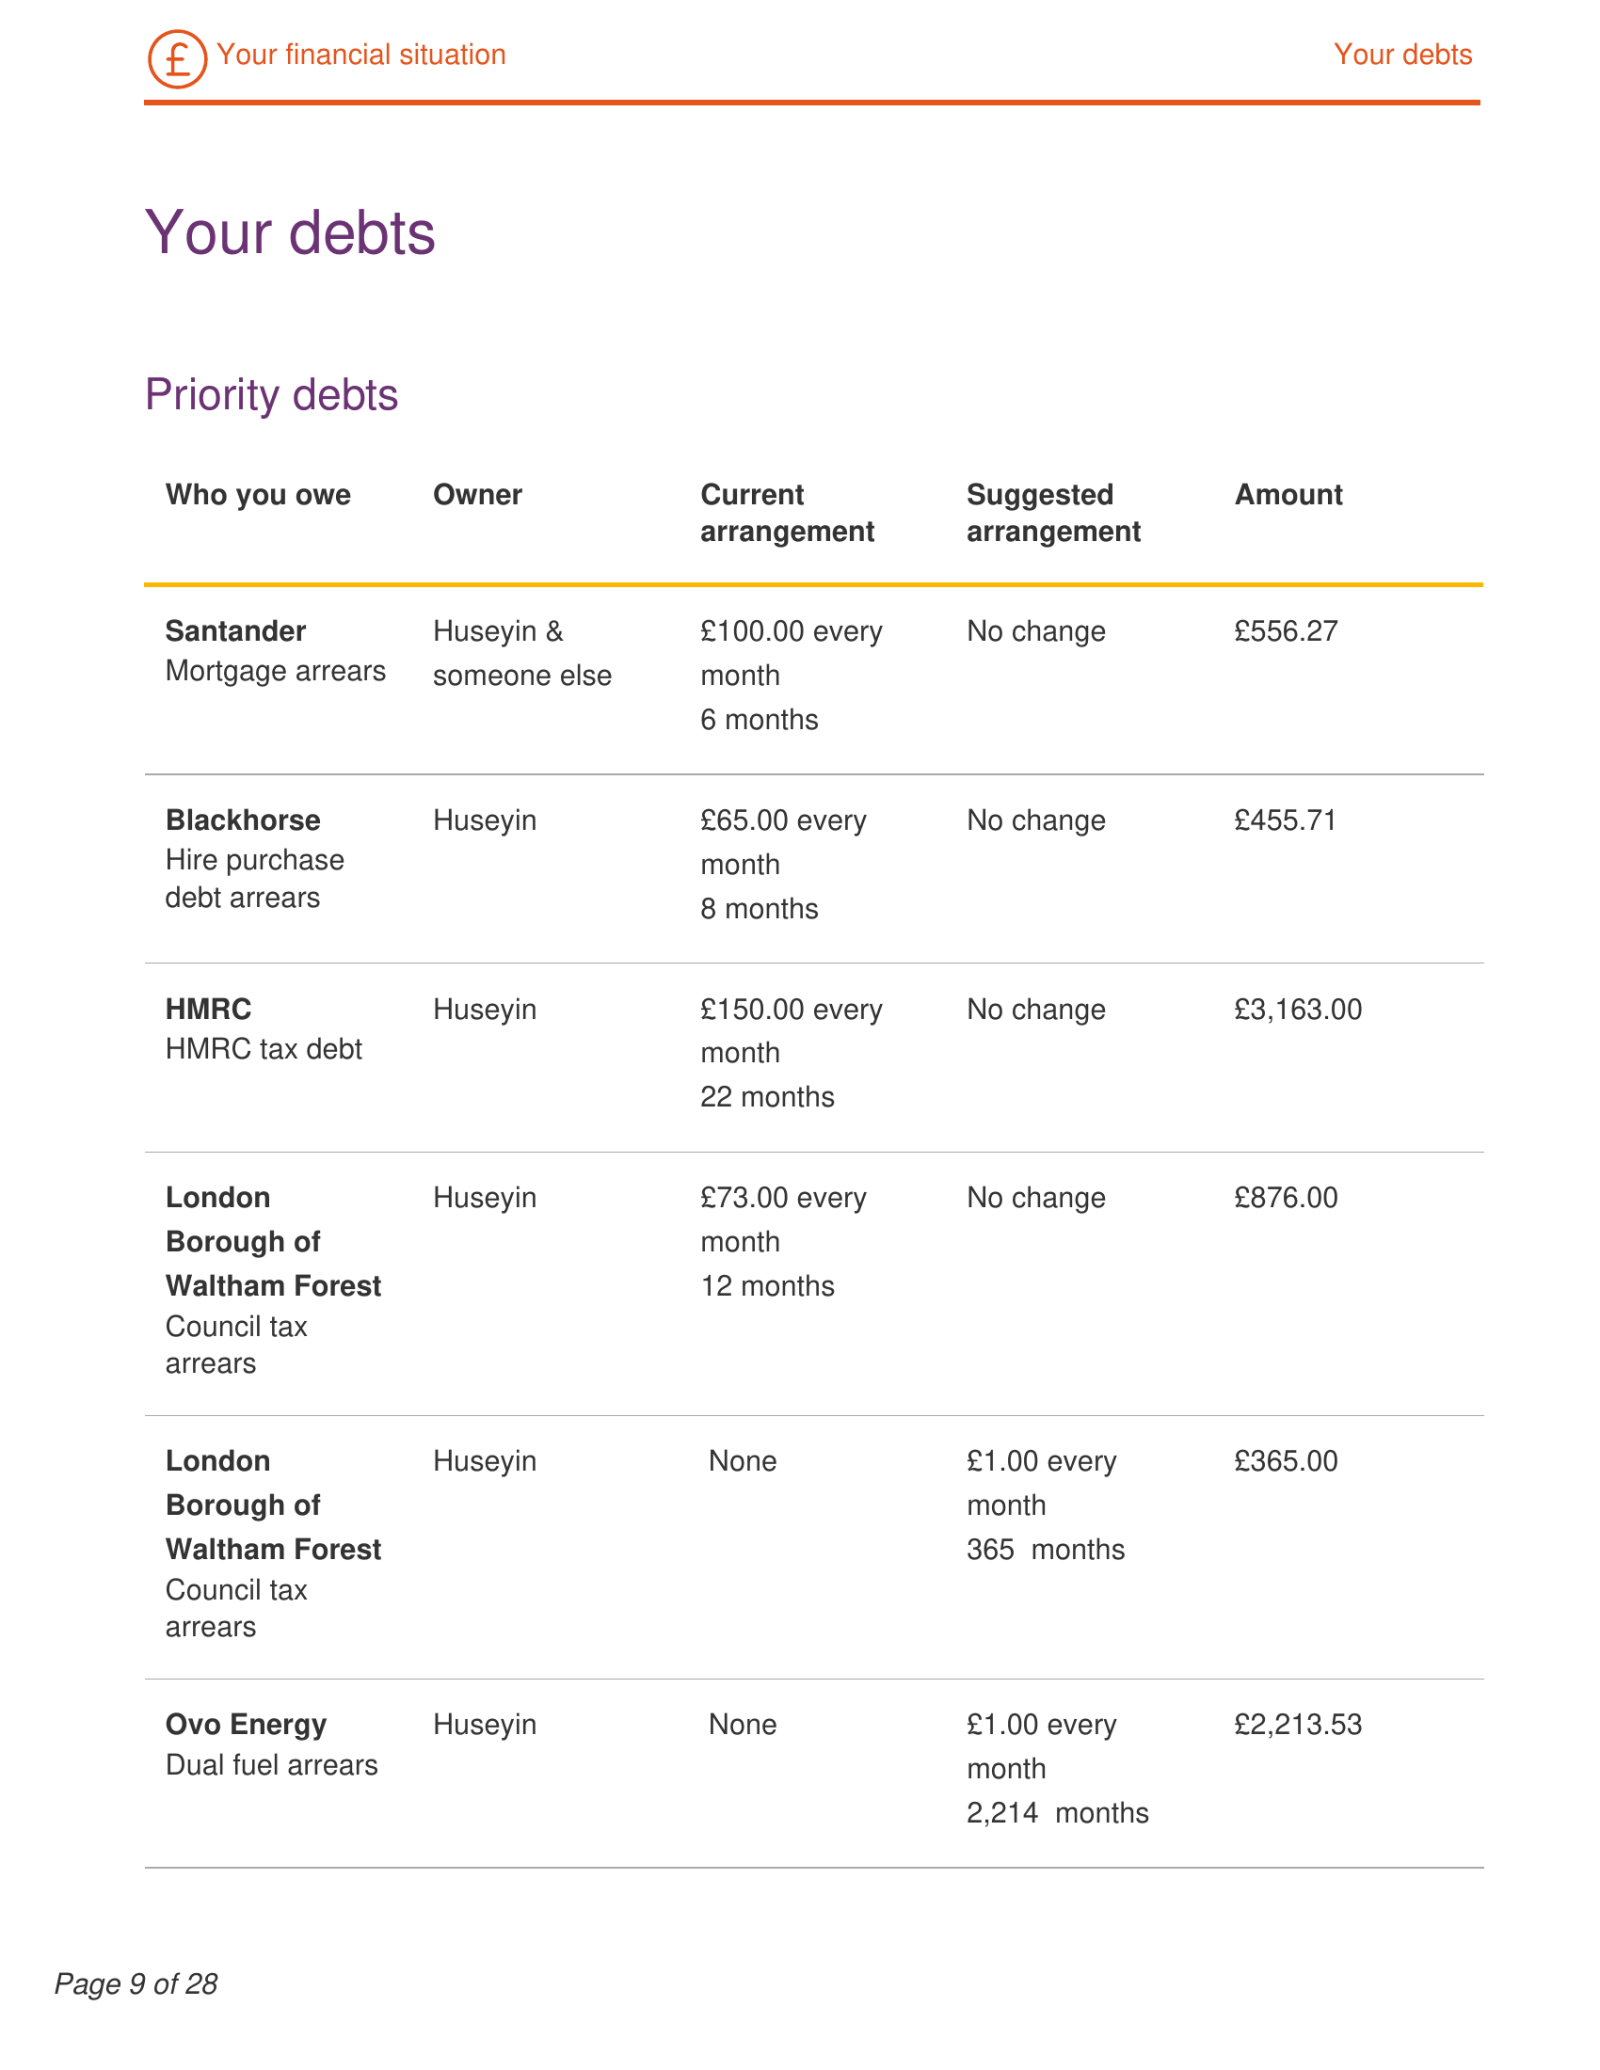
My main concern now is the house. The mortgage is interest-only with around £80,000 outstanding. The arrears are now down to around £350, which I should be able to clear shortly. My Santander deal finishes on 2 October 2026, and Santander has told me I need to clear the arrears first before they consider what they can offer me. The actual mortgage term ends in October 2027. They said I need to look into that as well, and they might be able to extend my interest-only mortgage for another 7 years until I am 70.
I also have around £2,200 OVO arrears, council tax arrears, around £3,000 HMRC Self Assessment arrears, some Black Horse arrears, and some VAT/Corporation Tax debts connected with my business which I am dealing separately with my accountant.
Honestly, protecting the house is my biggest concern. I have lived here for around 25 years and it is probably the one thing in my 62 years that I can look at and feel I have achieved something substantial for my family. Losing it would devastate me and my family.
I also have ADHD and long-standing general anxiety and I am finding all of this extremely difficult to manage.
I am going to speak to StepChange again, but because their own budget already shows me in deficit, I am not sure how much practical help they will be able to give me. Because of that, I would also really like to find some local hands-on help, like a specialist Citizens Advice debt adviser, a law centre, a debt charity, or a caseworker who can actually sit down with me and help me work through the priority creditors properly. Does anyone know what kind of organisation I should be looking for?
I am finding all this extremely difficult to manage due to my ADHD and long-standing general anxiety.
StepChange have also suggested looking at later-life lending, including a lifetime mortgage, but I really do not feel comfortable with that at the moment because of the effect it could have on the house and what I leave my family. I am not ruling anything in or out, though. If there are sensible ideas involving reduced arrangements, temporary holds, borrowing, refinancing or anything else I may have missed, I would really appreciate people’s thoughts.
I know people here normally like the SOA done through Lemonfool.co.uk, but I have only just completed a detailed StepChange one. Would it be okay if I attach the StepChange I&E instead, or would you still prefer me to redo it through Lemonfool?
I am honestly feeling pretty desperate, and I really don’t know what the best way forward is anymore. I would be very grateful for any ideas.
Thanks to everyone in advance.
Comments
-
Hey - just a message to say I hope you are ok. That is a lot to deal with. I hope someone more knowledgeable sees this in the morning. There is always a solution.
Hastings Direct 4775.99
La Redoute 676.21
Barclaycard 295.20
1 -
I think post any SOA you can and people on here can figure it out.
DFW info LBM: March 26
Total 03/26 69,481
"You put one foot in front of the other and one day you look back and see that you have climbed a mountain" Ready for the climb.💪
1 -
husni, I'm not surprised you are feeling anxious.
I'm really concerned that you've been posting about a DMP for a year now. And in June raised to issue of mortgage arrears.
I'll go back to the advice given in June. You should not be paying money towards consumer debt when you have mortgage arrears.
And you should never use money to pay consumer debt when you have Council Tax arrears, HMRC arrears and VAT arrears.
What's not been explicit is that your mortgage ends next year whilst most people answering here assume that your current mortgage fix needed renewing. So they're giving advice may not be appropriate.
Based on your comment about income above and your previous SOAs, the biggest problem isn't your expenditure. It is that your adult family are still not contributing towards their living costs.
The answer to your increasing problems isn't to fiddle around with your money. It is to put a bomb under your family. And insist that they help clear a lot of these debts urgently. That means they work, or work more hours and they make major contributions to the household expenditure. Now.
Otherwise you may have to sell the house next year and move somewhere smaller. Smaller because it'll have to be a cash purchase and the cost of selling and buying will reduce the amount you can afford.
I'm not trying to raise your anxiety but to ask you to harness your efforts to deal with the big financial problems. And the biggest problem is that it is impossible for one barely average income to fund 4 adults living in one of the most expensive cities in the world, 3 of whom are not pulling their weight.
The Council Tax need dealing with now. Your adult children need to pay it, now. If the Council get a liability order, then the whole year has to be paid, not instalments and the next stage is bailiffs. They need to understand now that when they move out they need to pay priority debts or there are consequences.
I'd suggest you show these threads to your family.
With regard to practical support, the mix of business debt, priority debt and consumer debt is a difficult mix.
You might check if Christians Against Poverty work locally as they offer face to face help. And that may help your ADHD and anxiety.
tigergambit has already referred to business debt line.
You might also find it useful to talk to Shelter about the housing and mortgage situation.
If you've have not made a mistake, you've made nothing3 -
i’m not an expert in the debt side of things, and I can see from your post how important your family is to you, but my honest opinion is to take leaving something to them off the radar at the moment.
None of us have a crystal ball or know what is likely to happen in the future; accident, illness, care costs; and you may find circumstances change . Or they may not.
I would suggest your priority needs to be yourself - maintaining a roof over your head for you for now. The rest can wait until you’re in a better position to properly think about what you want to do about it.All shall be well, and all shall be well, and all manner of things shall be well.
Pedant alert - it's could have not could of.3 -
I understand the sentiment but neither the local authority or HMRC are going to wait for their taxes.
If you've have not made a mistake, you've made nothing2 -
I think a list of your debts would be helpful to start with, you don't really want to get lost in the minutiae of an SoA at the moment, it's more important to see the big picture.
Please include the business debts (unless you have a limited company with no personal liability for any of them).
Priority debts: lender, rough balance, any payment arrangement in place
then
Non priority debts: lender, rough balance, any payment arrangement in place
Then information about your house - IO mortgage of 80k, ends next year, may be possible to extennd it until you are 70. How much is the house worth?I think you should talk to StepChange about lifetime mortgage options and do this soon. You cannot rule this out because you would like to leave more to your family, with a IO mortgage you may lose the lot…
Who else is living in the house and how much are they contributing a month now?
Do you have any spare rooms?
What are your pension provisions?
How is your business doing?2 -
From a previous post the house is worth around £550k so I would seriously consider a life time mortgage. This can still be payed down when you are in a better financial position or downsize in the near future.
Are your adult children still in full time education?
Why is the house solely in your name rather than jointly held with your partner / spouse?
1 -
I have to echo what others have said, you should always prioritise essential debts, it can lead to serious consequences if you don`t, the non essential credit debts really can be ignored, by trying to please everyone, you are making the situation a lot worse than it need be.
Basic rule of thumb is pay essential debts first, mortgage/council tax/tax arrears etc, all unsecured credit can wait, as the potential penalty for non payment is much less severe, and in most cases no penalty at all.
I’m a Forum Ambassador and I support the Forum Team on the Debt free wannabe, Credit file and ratings, and Bankruptcy and living with it boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com. All views are my own and not the official line of MoneySavingExpert.For free non-judgemental debt advice, contact either Stepchange, National Debtline, or CitizensAdviceBureaux.Link to SOA Calculator- https://www.stoozing.com/soa.php The "provit letter" is here-https://forums.moneysavingexpert.com/discussion/2607247/letter-when-you-know-nothing-about-about-the-debt-aka-prove-it-letter1 -
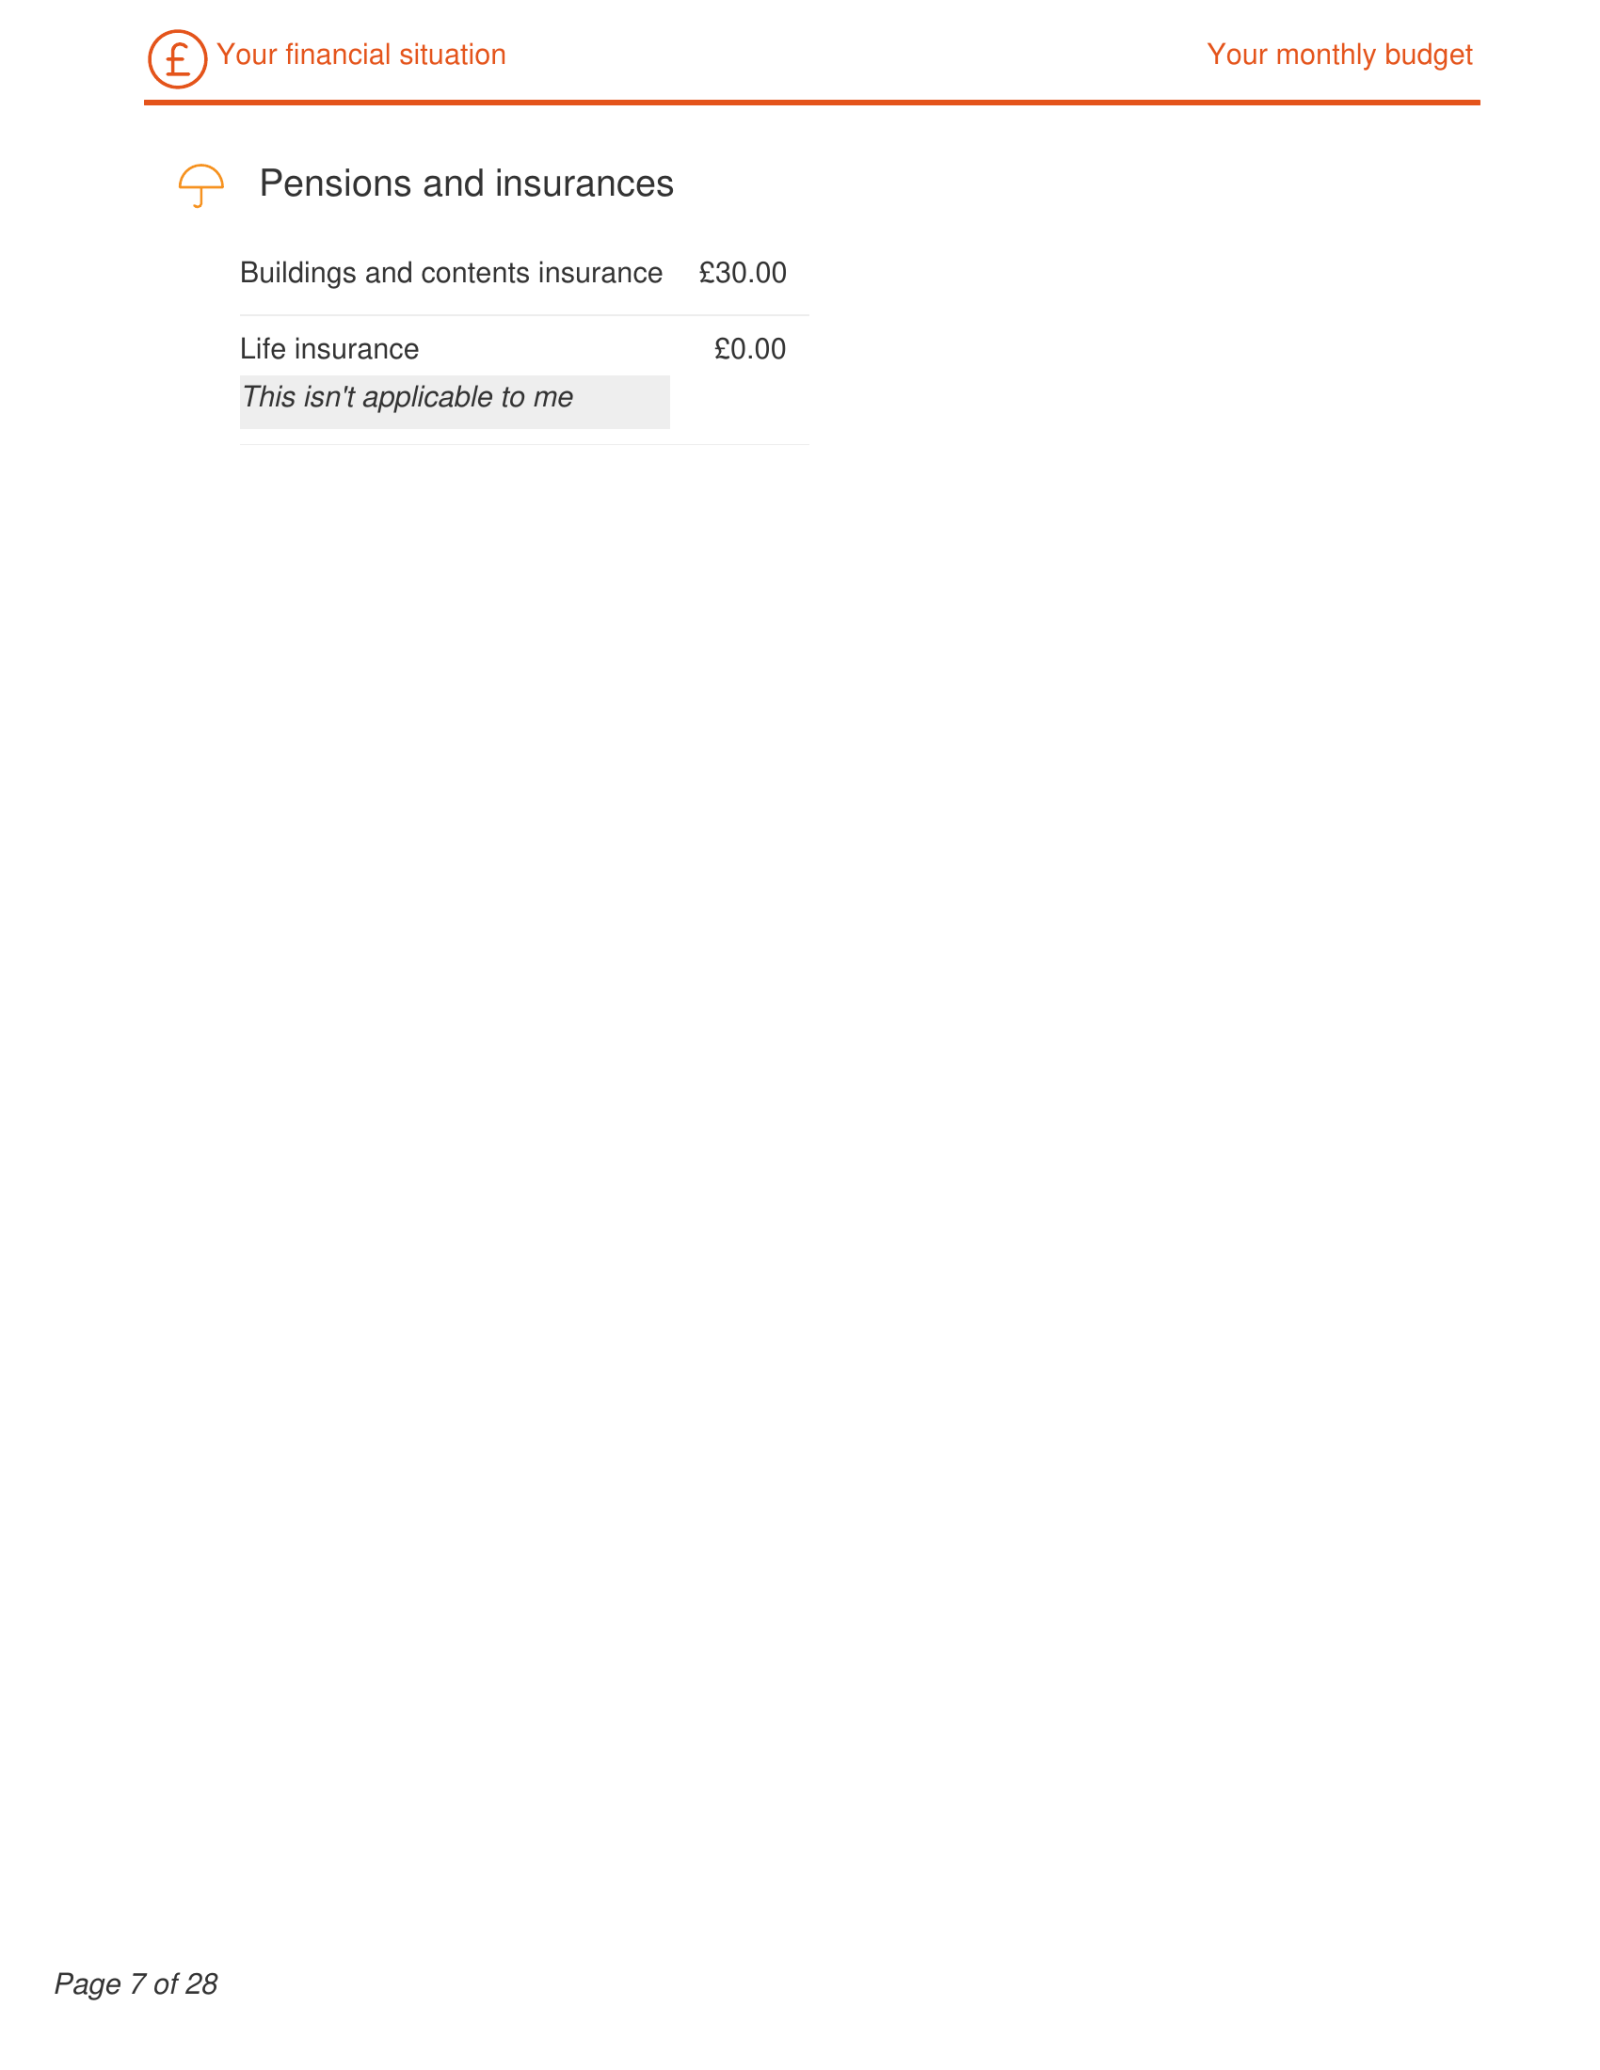
Thanks everyone for the replies. I’m attaching the relevant pages from my StepChange I&E rather than redoing the whole thing on Lemonfool at the moment.
The Santander arrears shown there are slightly out of date. They are now around £350 and I should be able to clear them very shortly.The four unsecured credit card debts total around £34,400. I have now stopped the DMP payments and will offer token payments for the time being. I completely accept now that I should not have been paying unsecured creditors while priority debts were falling behind.
The StepChange debts total around £42,000. There is also a Capital on Tap business debt of £15,222 which is not included in the StepChange I&E. That debt has a personal guarantee, so I understand that I can be personally liable for it. I had been paying £50 a month, but I have now stopped those payments as well while I concentrate on the priority debts. That takes my overall personal exposure to around £57,200.
The VAT and Corporation Tax debts are liabilities of my limited company rather than personal debts, and I am dealing with those separately with my accountant. The VAT arrears are around £1,293, and Corporation Tax is around £2,098.
The house is jointly owned with my wife, and I now think it is worth around £500,000. There is about £80,000 left on the interest-only mortgage. My current Santander deal ends on 2 October 2026 and the actual mortgage term ends in October 2027. Santander has mentioned that extending the interest-only mortgage, possibly until I am 70, may be something they can consider, but nothing has been agreed, and when I show them the updated I & E, I don't think I have any chance of them doing this.
Several of you have mentioned a lifetime mortgage. I haven’t spoken to StepChange again yet, but I will. I am still very nervous about lifetime mortgages because of the rolled-up interest and its effect on equity, but I accept that I should at least investigate them properly rather than just dismiss them
There are four adults in the house. My wife does not work, my son is setting up his own business but is earning very little at the moment, and my daughter is still studying. They have all helped me financially when they can, but there is no meaningful regular contribution at the moment. I do accept the point that one income cannot realistically support four adults while the household is already in deficit, so this is something we need to discuss as a family.
I don’t have a private pension. My wife and I should both receive the full State Pension when the time comes.
My Amazon business was successful for about 15 years and provided us with a comfortable living. Over time I took too much money out and didn’t leave enough working capital for stock and future costs. Then Covid made things worse and eventually the business more or less stopped.
With my son’s help, I am now trying to rebuild it. He will be investing some money in the business and taking over parts of the day-to-day work because I am currently driving around 60 hours a week for Uber. I know the Amazon business can work because I ran it successfully for many years, but realistically it will probably take around 6 to 12 months before I can start taking meaningful money from it. My worry is that, with all the arrears, I don’t know whether I have six months to wait.
I know some of the replies are difficult to hear, particularly about later-life borrowing or downsizing, but I genuinely appreciate people being straight with me. I would rather understand all the realistic options now than carry on moving money around until another bill falls behind.
Thanks again, everyone, and I will look forward to your replies.
0 -
This is going to be blunt.
The solution absolutely screaming out at you is to sell up and live in another [cheaper] part of the country. As you can Uber anywhere, you can just pick that up again in your new area.
You should be able to clear all of your debts, lower your regular costs, and hopefully drop the adult children that are currently cadging off you along the way. And reduce your hours from 60 per week!
The stress that you are putting yourself through is so unnecessary. In my humble opinion.
1








Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards