We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Quick sense check for my brother's fire service pension options




Hi
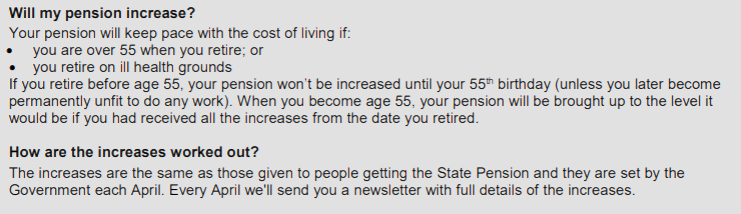
My brother is being made ill health retired at 49 from the fire service (bad back) - below is snapshot of benefit options. It looks pretty clear to me which option he should take, but just want to check that there's only one real sensible option….
I believe he has a choice of being in Legacy or Reformed Benefits plan:
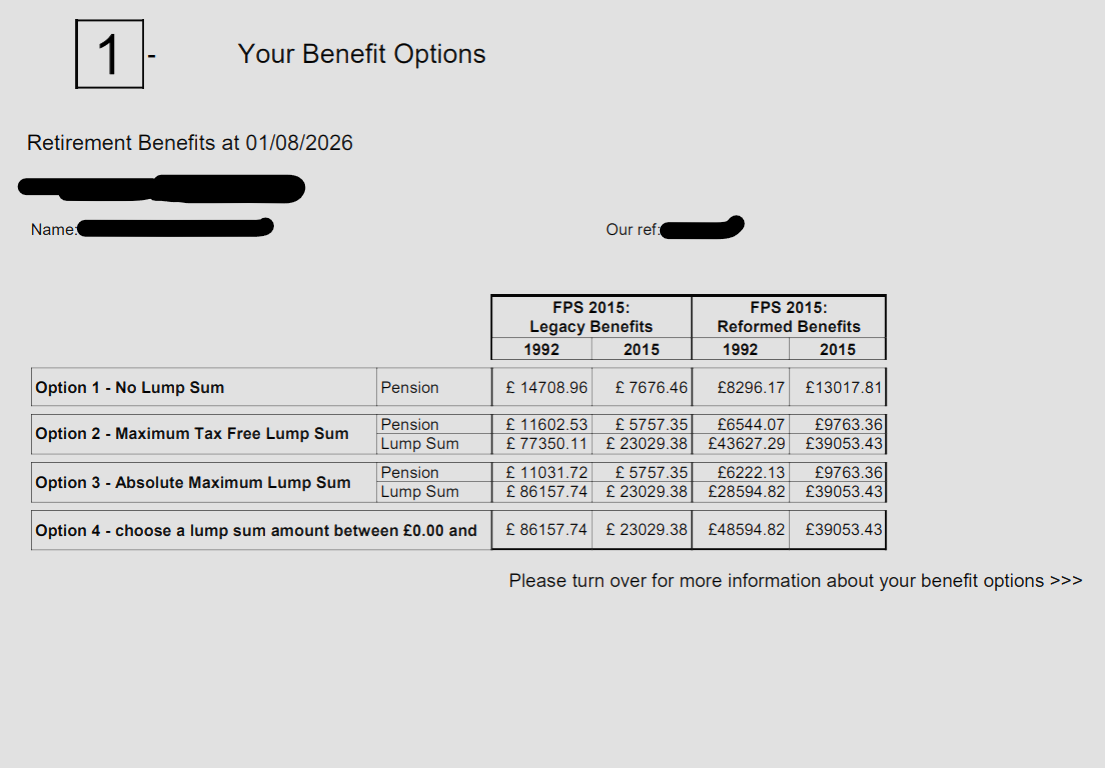
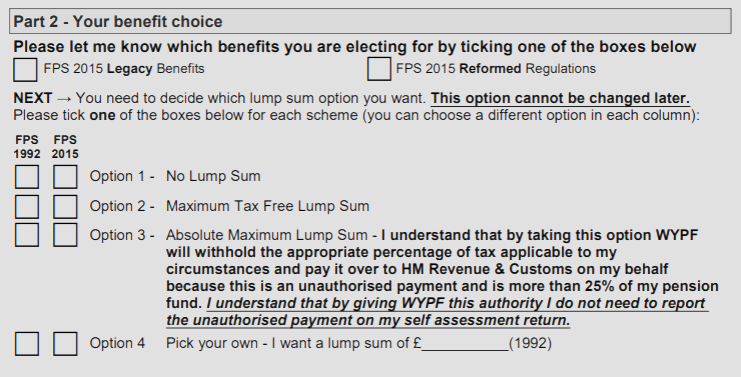
My thoughts is remain in Legacy Scheme and take no lump sum.
Thanks
Comments
-
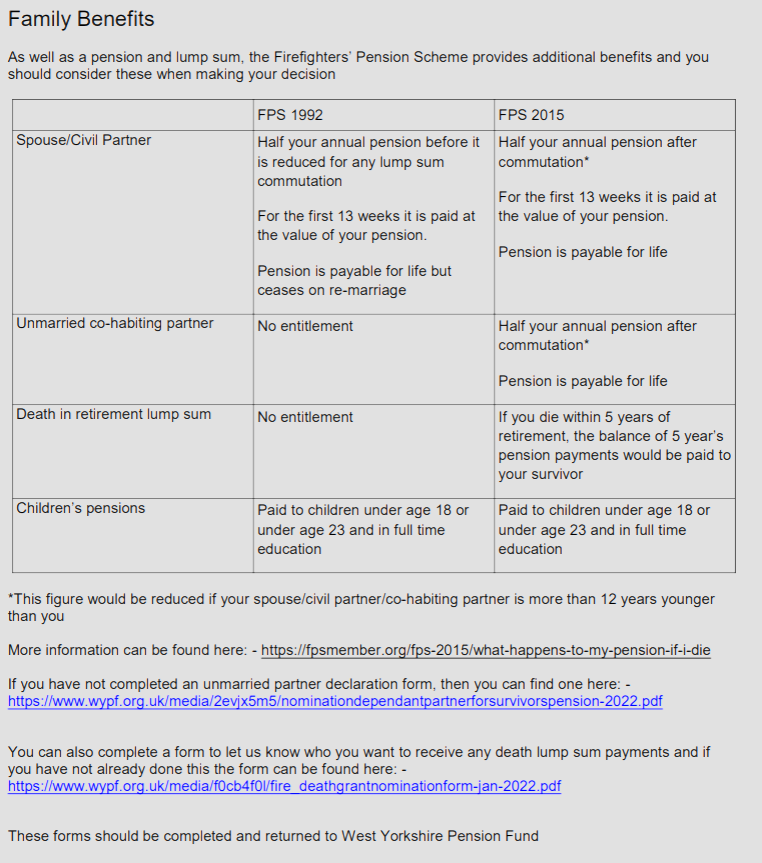
what are the different terms for legacy and reformed - annual increases based on?, survivors pension?
Does he need any lump sum?
I’m a Senior Forum Ambassador and I support the Forum Team on the Pensions, Annuities & Retirement Planning, Loans
& Credit Cards boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com.
All views are my own and not the official line of MoneySavingExpert.1 -
I'd be talking to his FBU rep, they'll hopefully have contacts for pension guidance.
1 -
-
You could do crude calculations of total income if your brother lives to say 90, but I think that is missing more important factors.
In my view his best option depends on how much income your brother needs to enjoy an acceptable standard of living, his current savings, and his post-FB plans.
For example he could take on a less strenuous job and live happily on the wages plus a lower Pension, knowing that SP would be paid in about 20 years. Also ongoing employment would provide additional pension. I assume he would need to pay further NI to get a full State Pension. He may have currently no savings at all. Under those circumstances a significant lump sum now could give more flexibility than a higher income.
Rather than coming to a snap decision a sensible next step could be to write down a life plan of income and expenditure over time. He is lucky in that he would not seem to have to worry about inflation.
3 -
He is lucky in that he would not seem to have to worry about inflation.
That "no annual increase until age 55" warrants attention.
0 -
thanks all. Just to add he recently started as a park ranger £27k salary and no real need of the lump sum atm. He will also have a not insignificant inheritance from elderly parents at some point (old money)
0 -
Not applicable in the case of ill health - cost of living increases will be applied from day 1.
4 -
I certainly very agree this post.
A 49 year old should take good advice from all sources available, his health may get worse, he may live in to old ago with poor health.
Nice slow decisions being well informed is a fair signpost IMHO.
1 -
Forgive me if I have missed something here.
You say as well as well as retiring on ill health grounds your brother is also getting divorced. If the financial settlement with his wife as yet to be agreed and settled, surely the pension quotes maybe subject to change if there is ultimately a sharing order?.
1 -
As he's been awarded an ill health retirement pension, it must be taken when due and can't be deferred pending the outcome of his divorce settlement. At the appropriate time, he will need to ask Fire Service pension for a CETV for divorce purposes (stressing that it is for divorce purposes). It matters not that the pension is already in payment - it's just a way more complicated calculation.
3







Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards