We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
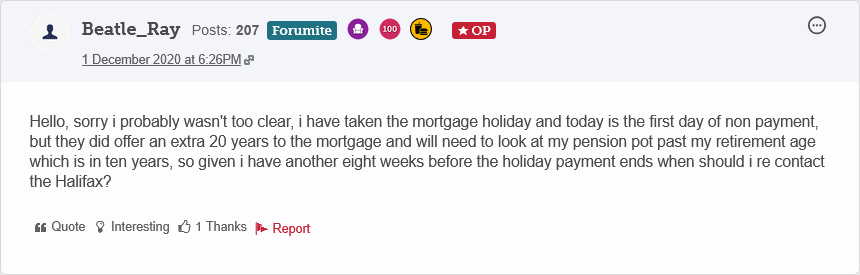
What happens when i can no longer pay the mortgage
Comments
-
I took the holiday period during Covid, i believe that was offered with no penalty, the income had dropped to almost nothing due to the pandemic, the DW does work but does not bring in enough to support the mortgage payment, we have had the selling the house conversation, although she isnt happy about it she does accept it.
My logic is that if i can get free of the mortgage then aside from a the utilities then i have no financial burden and can start living a little, i just need to find the right approach with the Halifax and understand how they will react as my situation i doubt is unique
0 -
Yes, looking at the date I can see that it predated the Charter, so you should be able to use it now, but it is vital that you talk to your lender before you miss a payment.
Have you talked to an estate agent yet to make sure that the value you put on the property is reasonable for someone looking for a quick sale?
You should also be prepared to rent for a period while you look for the right property as you will not want to delay your sale by getting caught in a chain on the other side of this deal.
1 -
I would immediately phone the mortgage provider, they are there to help. If you are up to date, which it sounds like you are and have a good payment history then they maybe able to give you a payment holiday. Leave it and then that option is going to be harder to offer. The same goes for other bills also, common sense has come to lenders and they do what they can to help.
0 -
Google mortgage charter - you can get 6 months interest only.
You can also google SMI.
I am sure you will have options. It depends on how long you need, what other income you will have (pension etc).
I am a Mortgage AdviserYou should note that this site doesn't check my status as a mortgage adviser, so you need to take my word for it. This signature is here as I follow MSE's Mortgage Adviser Code of Conduct. Any posts on here are for information and discussion purposes only and shouldn't be seen as financial advice.0 -
Hopefully the OP has more than the basic state pension to look forward to.
It's unfortunate that some small business owners tend to follow the mantra that their business is their pension and do not establish any meaningful provision outside it. Hopefully not the case with regard to the OP, but he has ( as far as I can see ) made no mention of his own expectations in this regard.
1 -
There was potentially something there a few years ago, hopefully still intact …
 1
-
I have probably glossed over some details, but tracker mortgages often have no penalty if you switch deals. Could you switch to an interest only deal, making repayments more affordable until you sell?
1 -
From what you say, you have enough saved to cover the mortgage for the next 5 months. Would now not be the time to market your property and actively downsize?
Not being a forced sale should give you a much better return, without impacting on your credit rating.
Others have mentioned equity release etc, but you would need to carefully consider health and also if you have any beneficiaries etc.1 -
I think the OP should use the equity they have to support them financially, rather than worrying about beneficiaries. If equity release is the best option to unlock the money they need, they should use it. If downsizing is the best option they should do that…
2












Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards