We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
What happens when i can no longer pay the mortgage




Hello, need some guidance please, my company that i run has just been dissolved and I'm trying to start another company as I do have the basis of a small business that I can run but the start of it for the next couple of years is going to be tough with a small income, but I have done this for 45 years, I'm 64 in a couple of months, my house is worth £475,000 and i owe £55,000 on it, the mortgage is on a two year tracker at 4.75% and the payments are £1011.74 per month, we made the payment yesterday but only just but I'm going to be without much income for the next few months and thereon for maybe a year or two, the mortgage has four years to run, i have never missed a payment since we took our first mortgage out in 1993, tbh I'm getting tired of paying the mortgage and have for the past five years topped up my income from my savings which i have just over £5000 left, i want to sell and downsize but the DW is not too keen but soon she will have to face reality, so, my question is do i phone up the Halifax and say, look lads, i can't pay, I'm going to put it on the market, therefore can you give me a breathing space whilst i do that, i expect to buy a property for approx £390,000 leaving us circ £40,000 after moving costs etc, what is the best way to handle this, after 33 years of paying a mortgage i just want to be free of it and not have the stress but acknowledge i owe the debt and need to pay it,, thanks in advance
Comments
-
You definitely want to be in control of that process. If the bank sell after repossession then they won't be worried about the price they achieve as they only need to get £55k back plus all their costs.
Certainly one to contact them to ask for that space but do you not have any other money you can access to get money for the next few months? Pension etc? If you're not bothered about borrowing in future then credit rating hit won't be important.
Remember the saying: if it looks too good to be true it almost certainly is.0 -
I think your idea sounds sensible. Telling your mortgage provider your plan is better than keeping them in the dark, at least give them the opportunity to cooperate with you. They will want their money eventually of course but if they know you're downsizing they might play along.
One thing to bear in mind is that Halifax might not freeze your interest. So be careful that the debt doesn't accumulate higher than what you are able to pay back, once all the costs of selling and buying are accounted for.
Have you considered getting employment somewhere, at least until your business is up and running again? Since you have owned your own business for the last 45 years this might be a lot easier said than done.
0 -
Thank you for the reply, if i did look for another job then I couldn't start the new company up due to my time working the new job, i know i can do it but I'm getting tired of paying a mortgage but just need to extract myself in the right way from the mortgage free will take so much stress off me
0 -
"Thank you for the reply, if i did look for another job then I couldn't start the new company up due to my time working the new job,"
But if you did have a job the timescales and urgency around the new company are not so important, what does your wife do ?
It could be a long time before you are able to draw a consistent amount of money from the new company if it works.
0 -
You say my house, is it solely in your name? If not you can’t sell it without your wife agreeing.
Your mortgage if fairly lairly low and you are over 60 so something like a life time mortgage might be an alternative solution.
0 -
The mortgage charter is an obvious place to start, assuming you've not used it yet.
In your scenario I would feel like the extension option is particularly appealing. You can always overpay once the new business is where you want it.
0 -
Looking at past posts it feels like you have been running a business for some time that makes far less than minimal wage, what do you propose to do that changes that future ?
0 -
Does DW work? Could she get a part time job to lessen the load?
"You've been reading SOS when it's just your clock reading 5:05 "0 -
It's called forbearance and Halifax are pretty good at it
0 -
From the looks of previous posts, you have already used the mortgage holiday option a few years ago…
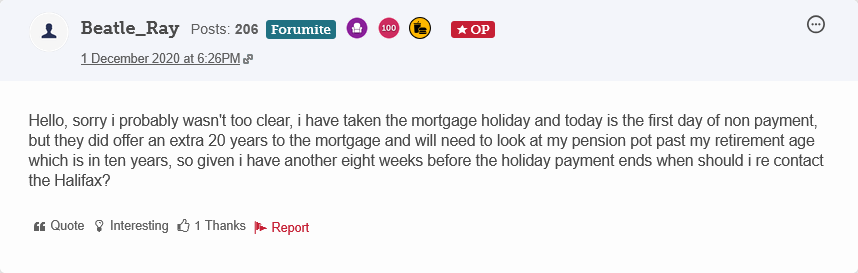
Similarly the business has been doing poorly for most of the last 6 years it seems which presumably resulted in the recent closure of that entity?
It feels like you have been trying to down-size for the last 6 years, always just a year or so away but never actually doing it.
If you go down the path of asking for forbearance from your lender and a further period of non-payment then you really have to be very sure you are actually going to do it this time…
If not then look quickly at an equity release product (Lifetime Mortgage) since as long as your wife is not a lot younger than you it offers the easiest way to bring your mortgage to an end with the option of no further required repayments on the new product.
… but… make sure you understand fully what the limits are on voluntary payments and how the porting of that product to a new, smaller property would work, especially if you have allowed the interest to roll-up for a while before you actually want to move.
It would be better to down-size rather than do this, but if you really can't commit to making that happen then this may be the only practical route.
See a good broker with experience with equity release, there are other retirement products, but with the nature of your income you are very unlikely to be able to get a RIO product for example.
1








Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards