We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Considerations for Post Retirement DC Fund: Please Help
Comments
-
You mention that DB income covers or will cover 90%+ of your exoenditure which is fantastic. Someone else mentioned falling under a bus. You might want to check what falling under a bus will do to the survivor's DB income. There may be some slack the DC pot will need to cover.
1 -
Thanks so much. I'm always amazed and grateful by the thoughtfulness and generosity of people comments on this forum - thank you to everyone who has responded - you have given me food for thought.
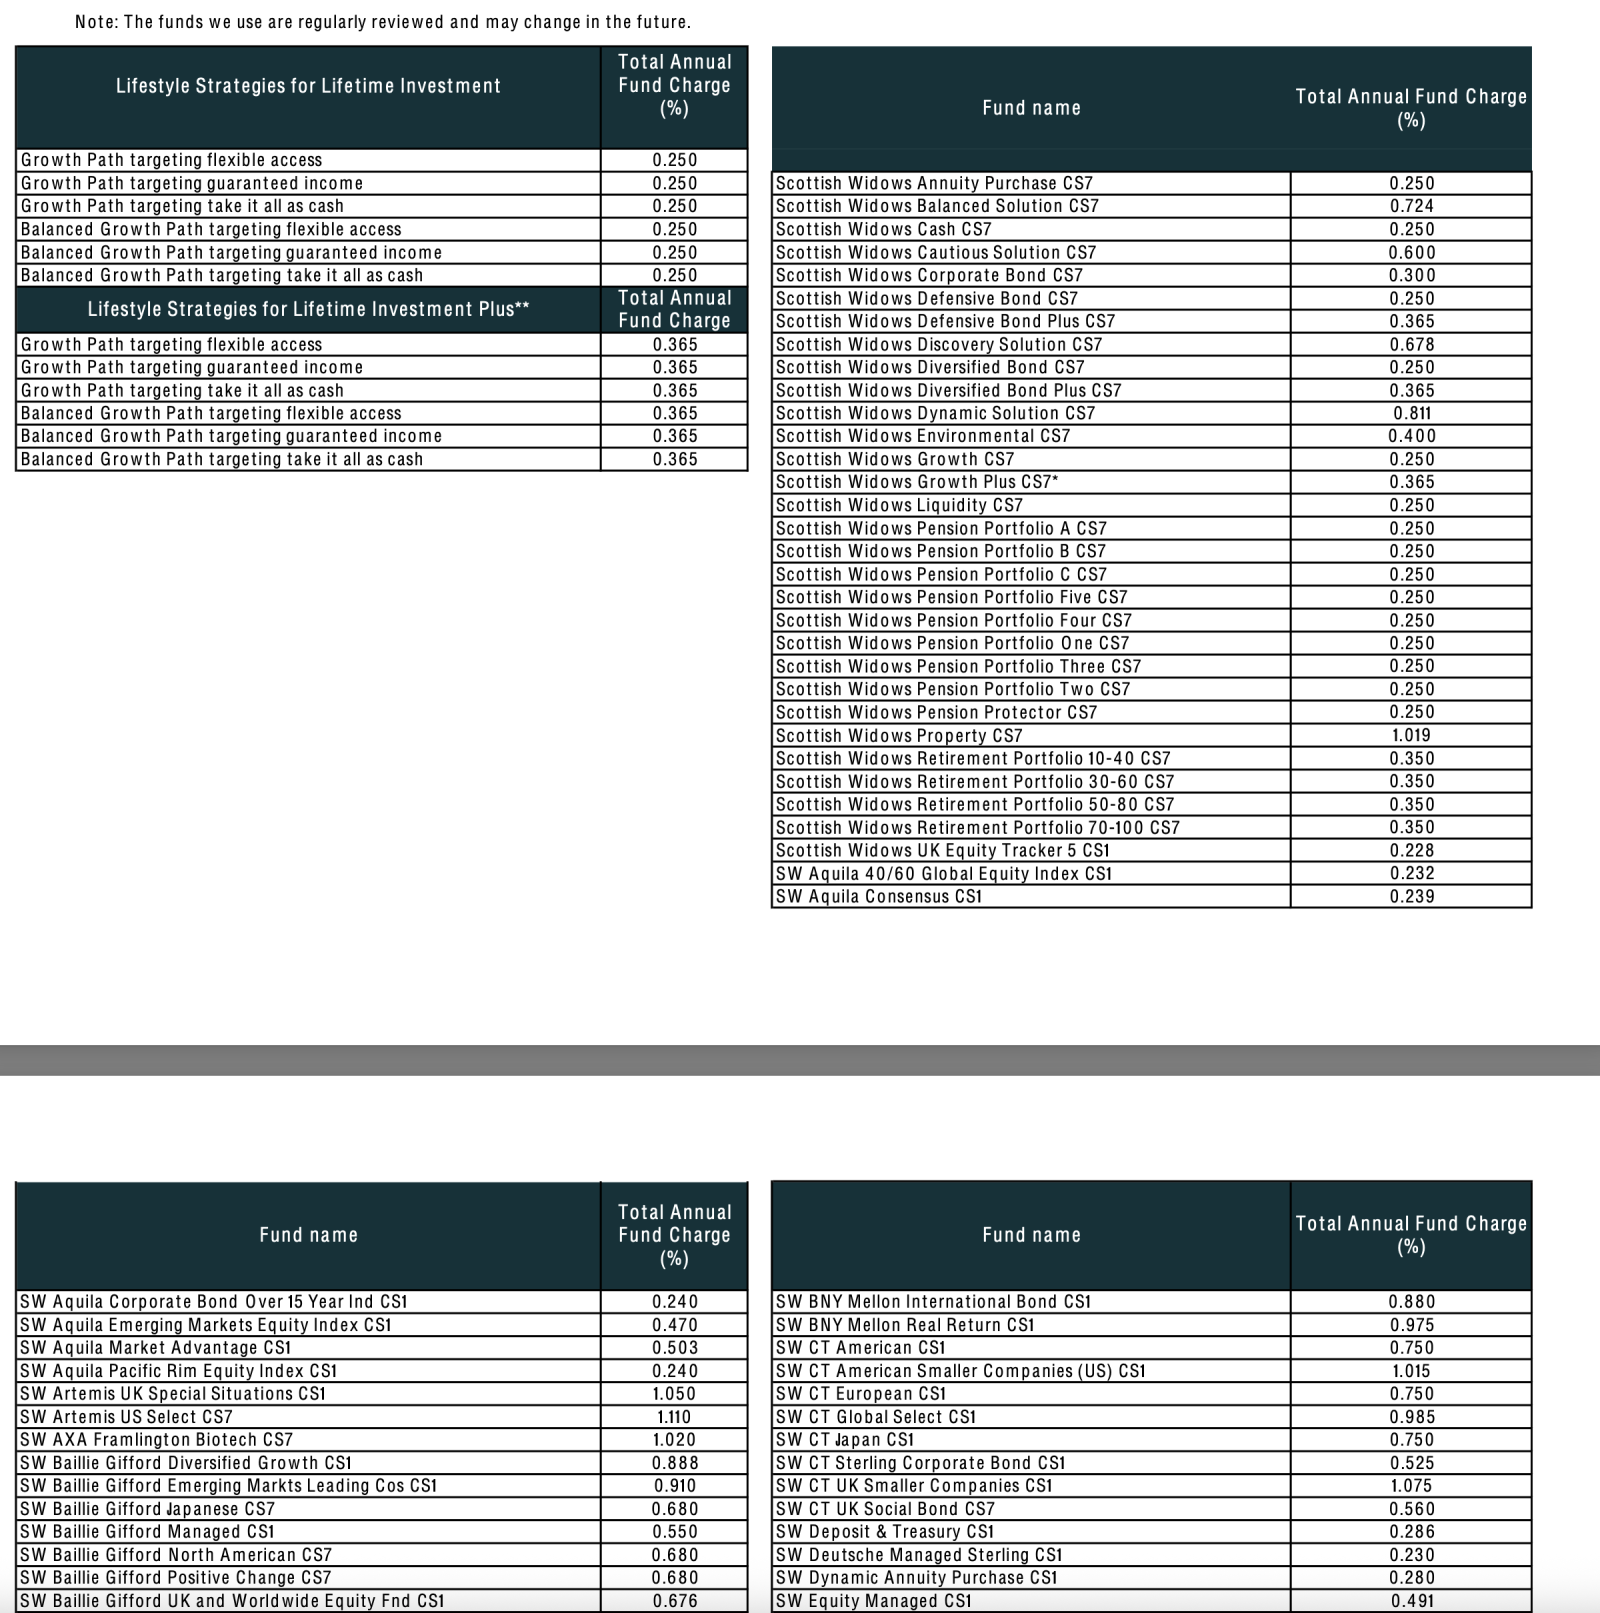
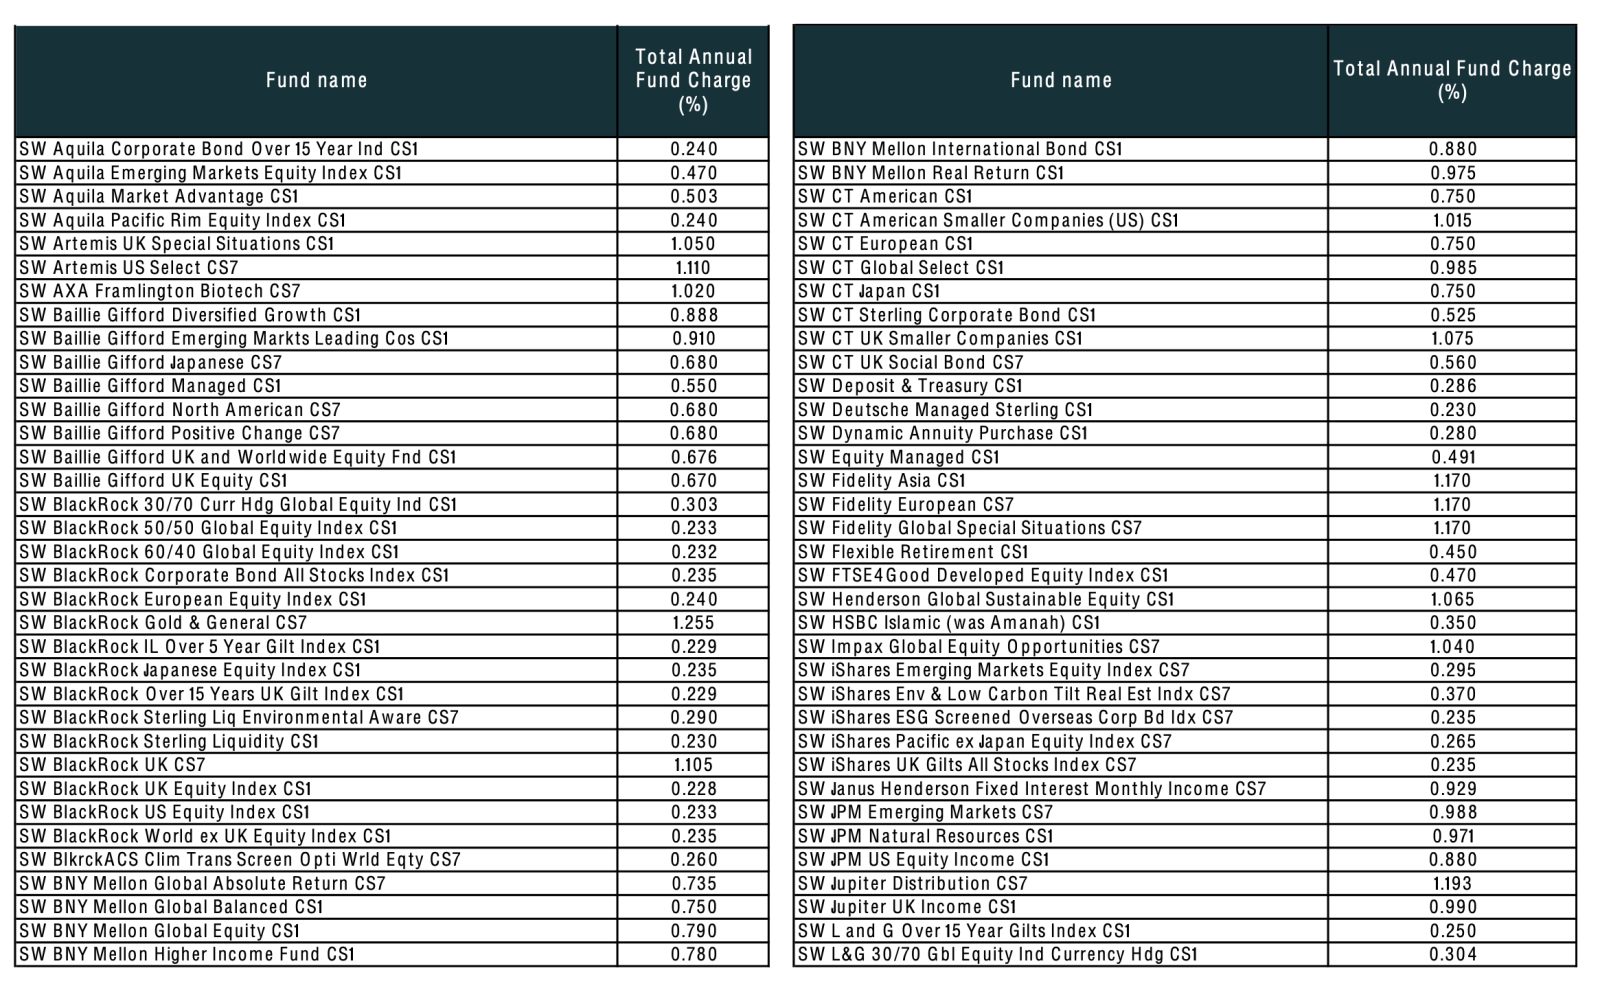
FWIW I have obtained a list from SW of the funds I am permitted to choose - most I guess would not be relevant. It feels totally overwhelming if I'm honest.
If anyone feels like casting a quick eye across this list and pointing me towards one or two funds I should consider further, in line with my original post, I'd be most grateful!
Thanks in advance…
 0
-
Yes that is a lot of choice. And the names don't always give you a clue what is in the fund (eg SW Flexible Retirement).
You also seem to have some duplication eg SW L&G Over 15 years Gilt Index CS1 appears twice. I wonder why?
Also some of the funds end CS7 and some end CS1. Are you sure you can invest in either one? Or can you only invest in CS7 (or only in CS1)?
What is it you are looking for now? You mentioned Vanguard 60/40 before and there is a Blackrock 60/40 Global Equity Index CS1 in the list with a 0.232% charge. Or are you going to go for a 100% equity fund and a 100% bond fund split 60/40 as separate investments?
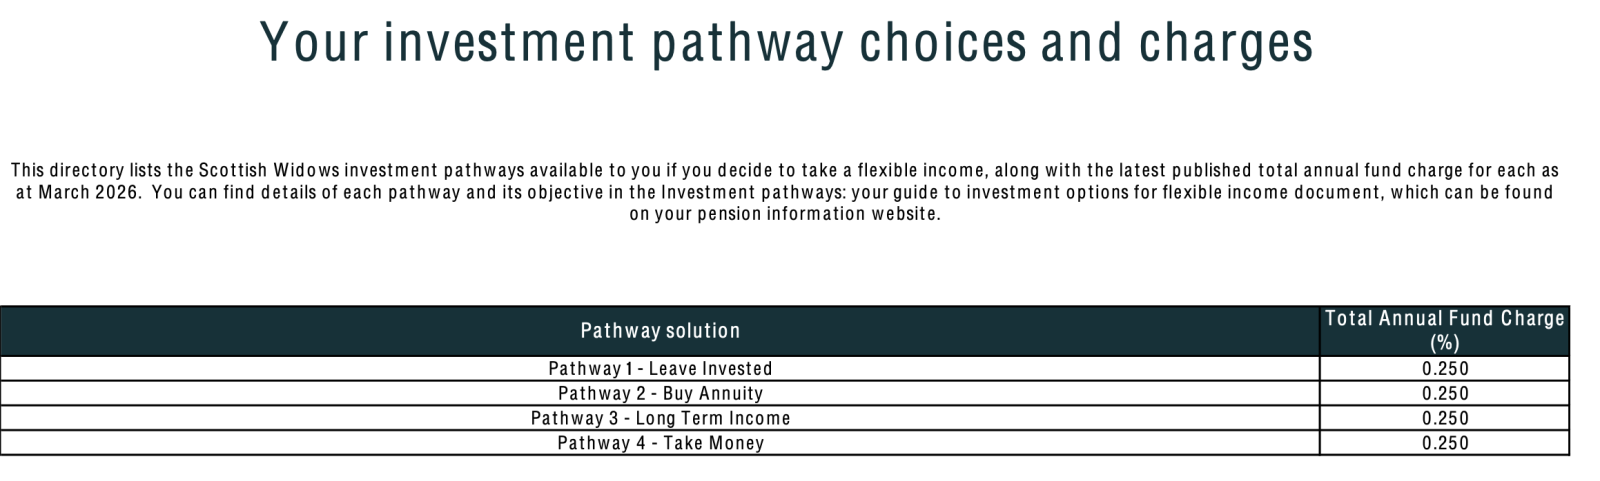
They have a list of Pathways at the end which look reasonably cheap. You might want to investigate Pathway 3 and see what that gets you. If nothing else you might want to use the 0.25% charge shown for the Pathways as the cap on the charges on any stand alone fund you pick.
0 -
The sequence you are looking for is
Step 1: "how aggressive do i want to be at this life stage with this slice of my money". And how diversified. Do I have preferences for my investment. Upon reflection I want to invest in assets ABC in approx this mix
Step 2. Find a fund or funds which does that to implement it. Fund shopping without doing Step 1 is a fools errand. How do you tell which is a better fit for you among the hundreds.
With that in hand SW have that or they don't at a fair price. And you move or you don't.
That said. From your list. Prune.
Lifestyle Funds are not very relevant once you reach retirement. It's an accumulation approaching retirement de-risk in stages thing. Ignore them
Unless you have done the prior step to want something specific by way of investment. May as well delete all the expensive ones. Which kills off most of the "actively managed" ones. You don't know why you want them. So odd choice to pick one randomly.
Which will filter the list down to passive or whole of market index investing. Not paying extra for someone to do stockpicking a subset for you. Global Developed Market stocks
You might decide you want to add Emerging Markets, Or Smaller Stocks, Or have high hopes for a specific region or country, or be sufficiently worried that the US is a bubble - that you put more money into other regions. There are specific and geographic funds on this list. Which support those ideas.
This kind of portfolio build is in two parts. One is just investing in more different things - smaller companies and more countries to add to the list of stocks you own. Which can have a goal of "less bumpy ride overall" as well as one of seeking investment return in more places.
And then there is tilting the industry or regions where you invest further. This is you thinking you know better. It will be right or it will be wrong probably both over time. And the passive investment as a religion community think it is heresy - which in their belief system. It is.
If you don't want to get into all of that.
It leaves middle of the road stuff.
Go and read these fact sheets to get familiar with the way these things are described.
Look at regional split. Look at the top 20 and how much % of the value of the fund is in those stocks. Look at the names of the actual underlying investment
So an example or two to get you started on relevant fact sheets
SW Black Rock 60/40 Global Equity Index CS1. This is a mostly UK equities fund. 40% overseas. 60% here. In sterling. Making GBP Currency exchange less of a factor for you than other choices. But its ALL equities. And mostly UK. A global investment without a tilt to sterling and the UK would have about 4% UK stocks. 56% less. A rather odd fish. 100% equities. Lower risk to GBP currency movements. Underweight the USA, tech , AI etc.
SW Black Rock World ex UK Equity Index CS1 is equities and everywhere but here
SW Black Rock UK Equity Index CS1 is equities only here.
0.228%/0.235% This is about double what it should cost. More like 0.10%/0.12% Enough to notice. Depending on the platform fees and what else you do. Maybe not enough to care. Versions of passive equity indices (lists of stocks) World ex UK and UK is available from many providers on many platforms. And as single funds
world/global/global developed markets versions with a standard mix often 4% UK or the slightly higher Vanguard ones. You can usually see on the fact sheets the regional splits. Or the trust net / morningstar web sites.
These example equity funds allow you to choose how much to bias to the UK currency and stock market LSE. From nothing at all - we are doomed point of view (All world ex UK), to 4% which would be markets by value - assuming the markets price it correctly (in which case buy the standard single global fund instead), or 10% or 20% or more. As you bias to UK you lower some of your sterling currency FX exposure. But you invest in a different list of companies and industries. Some international funds are based on USD as the common currency. And so the exchange rate back to GBP can help or hurt as well as underlying performance. For a long time we have had a strong US market and a tail wind from the pound dumping value vs the dollar. It could continue. Or our political leaders could turn things around a bit (relative to others). Nobody knows.
Those two mixed to taste and a bond fund for however much of that you want makes a three fund portfolio. Or 2 if you don't want to customise how much UK
FINANCIAL HEALTH WARNING
Bonds how they work. Why long and short duration are different beasts. And why funds vs holding actual bonds are different again. Is a whole education topic. Module 301. Not 101. If you buy a specific bond fund without understanding how they work and the specific content of this one. It can surprise you vigorously with losses that are not a shock, a surprise or a bad event - just "how they work" vs global economic conditions and central bank actions. Arithmetic. This is undesirable.
Recommending a bond fund to you is therefore REALLY hard. And I am not going to even try.
It depends on WHY you want it. Cash equivalent (for access), inflation hedge, part of a long term diversified investment with more than one asset class. Or other reasons not listed. Some of the funds on this list are designed for these different roles. And cannot be picked blind to intent. Perhaps to get adequate potential return overall you have to mix in some riskier stuff. It depends.
Start by looking at government bonds. Sterling. Or hedged back to sterling for US and other government bonds is broadly speaking canon for guidance - but you can buy it with and without the currency hedges.2 -
Thanks gm0 for such a detailed response. Sadly it highlights the limits to my own knowledge. I'm trying to avoid IFA fees for what should be a relatively simple decision - given DB pensions cover main needs and this is almost "extra" money - but am beginning to wonder if DIY is not for me and I should bite the bullet for advice…for me this is a significant amount of money…
I'm definitely looking for low cost tracker funds and so would definitely discount the more expensive active managed ones. I'm getting more confident with reading factsheets but am amazed at how confusing fund names can be: for example something with 60:40 in the title can mean the equity/bond split, or alternatively could be all equities and the numbers refer to geographic split…hadn't even considered the Fx currency issue. My knowledge on bonds is low enough to avoid choosing a specific "only bond" fund as I wouldn't have the confidence to know I was choosing wisely, therefore my eventual single fund choice would need to be a fund that already combines equities/bonds in a 60:40 ish or 70:30 ish mix to suit my risk profile.
I can see that products like Lifestrategy overweight the UK on the basis of how much it contributes to the world market - this feels risky to me, but that said, I already hold Lifestrategy 60:40 in my S&S ISA! Therefore I suspect I would feel more comfortable with a fund whose equity distribution better reflect the world market which would presumably favour the USA?
How much hassle is it to move monies from say Scottish Widows if there is nothing that fits my thinking to another provider?
Does anyone have a view on the following funds - they seem to fit my needs, and I see them referred to positively often in other post, but am I missing something?
- HSBC Global Strategy Dynamic Portfolio
- HSBC Global Strategy Balanced Portfolio
- HSBC World Selection Portfolio 4
Thanks again in advance for any comments.
0 -
I have a mix of the top 2 in fund form as the majority of my pension and my ISA and it is nice and easy - I just wanted a little more finessing of the risk. I have more dynamic in the ISA where growth won't incur tax and more balanced in the SIPP.
They are multi asset funds but aim for a risk level rather than a specific split of equity/non equity (like Vanguard do with their Lifestrategy funds).
I know nothing about #3
I’m a Senior Forum Ambassador and I support the Forum Team on the Pensions, Annuities & Retirement Planning, Loans
& Credit Cards boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com.
All views are my own and not the official line of MoneySavingExpert.0 -
Just to note that if this is an occupational pension you might find your employer has negotiated a discount on some or all of those fund costs.
You could still be benefitting from those discounts even if you're not longer employed by them.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Ofgem cap table, Ofgem cap explainer. Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Best kettle!
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.0 -
Moving is in general easy. You open an account. And "pull" the DC fund across (the new provider does - like an ISA).
There are people who cannot move trivially for specific reasons linked to benefits in the existing scheme. Such as guaranteed annuity rate offers and such like baked into their scheme. They need advice as once lost by moving these (valuable) benefits are gone. So the law was changed. Ceding scheme puts a hold on it. Standard DC pots without that stuff. Easy.
Your I don't know much therefore logic to make a safe choice - middling multi-asset fund - is fine. The person it needs to work for is you. Be happy with the risk level selection and why you chose it. Will it be "best". Nope. Will it be OK. Probably over the long haul. Will it feel like a big mistake? Possibly if a crash arrives just after you do some trading. And maybe you look back later and say "I should have been more aggressive". All with the benefit of hindsight. You need to do you. And be happy. And not panic and sell at the wrong time in whatever turbulence turns up. Spoiler: Knowing what to choose for "best" is close to impossible a priori for the professionals as well as us consumers
If moving look for cashback as well as a place that a) has your investments of choice b) good fee structure - for those investments. All the information is on the web. But there are subtle aspects. Trade costs (which matter or don't based on your plans to do it vs setup and leave alone). And some platforms charge different capped amounts for ETF vs Fund e.g. Fidelity. Which is cheap to hold a pension in ETFs but not the cheapest player to hold Funds.
I recommend you get a free trustnet account. Get these 3 funds or others up (some data is there some not)
Build a "model portfolio" proportions to taste. Run the what is this portfolio - overlaps and what is it / how does it behave reports?. Look at the history of the fund or portfolio vs the broader market. How much does it lag raw global equities index returns. How spiky is the journey in the "moments of excitement"
No real comment on the specifics. I hold a similar thing L&G Multi-asset 3. As a small experimental component alongside in one of my pensions. And by similar I mean branded self balancing fund a mix of equities, fixed interest, alts and other with a middling % equities.
In general I favour raw index trackers. Which do a thing. That tracks a publicly available data series. And what is in it is known. Cannot change arbitrarily (fund manager/company action) rather than companies growing or dying and entering or leaving the index. I like my fund managers on the tightest of possible leashes.
But that's my bias. When i buy passive within an asset class. I want to get that - not passive-ish. Their incentive is to run the fund well, keep assets flowing in not out and thus to "perform enough" here in the short term to avoid that outflow shrinkage scenario. Their salary depends on it. This is not fully aligned with your long term interests and risks. As it incentivises short term risk taking within the constraints of a given declared mandate for a fund. Most selective funds "die" (outflow and shrink and bad performance history and get merged back and replaced with the new shiny thing when their luck runs out. Pure trackers in contrast are more immortal. Can of beans.
As has been said. Take time to understand your actual fees. (Embdedded fund costs and scheme/product/plaform. I built my drawdown around keeping my occupational for quite a few more years. Because it provides simple investment options at subsidised prices. Don't read a generic fund factsheet and treat it as gospel.0 -
Thanks again gm0 (and others) - I really like the idea of a model portfolio on Trustnet - job for tomorrow!
Final thoughts though - I think I have stumbled across a Scottish Widows fund that seems to tick my boxes (based on previous elements of my post:
Scottish Widows Managed Growth 4 L Acc
Would welcome any thoughts!
Only challenge seems to be that this does not exist in the list that my employer says I have access to (earlier in post).
That said, it seems to be a pretty standard, well established SW product and my money is currently with SW - surely I would be able to transfer my money to this fund in a flexi-access drawdown account if I decide to go ahead, right??
0 -
Fund lists in a given product or scheme are in general a closed list. Yours is quite long. Some schemes and master trusts have 10 or 20. You have several options here in most categories
But don't ask don't get also applies. No harm in asking.
With an inhouse fund management arm item there is reduced friction but not none. With a 3rd party one they buy in/link to - more work their end so less likely.
Bureaucracies will mostly have a policy in place which says when a customer asks to customise the investment range just for them - the answer is NO in flaming capitals.
The request to add something - not already covered - to the product - will be passed to the relevant product planning team (black hole) - watch this space - we may add it in future - blah blah etc.0










Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.5K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards