Ready, steady… save!
You don’t need a chart to join in. Here are 2 ways to record your savings:
1. Cross it off
Pop a chart into your first post. Saved an amount? Cross it out! Read more »
£0.01 £0.02 £0.03
2. Write it down
Skip the chart and add updates to your first post. Read more »
“Another +£3 saved today. Go me!”
Use +£ before each new saving so it counts towards your total.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Looking for best 1 year fixed rate bond/ gilt
Comments
-
I hope you understand that most of that gain will come at maturity in 2035, the actual coupon is 0.625% per year, so you won't get much payout if you were expecting 6% return paid to you every year.
0 -
I know get paid at end of term in 2035.
0 -
I said equivalent, meant effective when term ends in 2035.
0 -
-
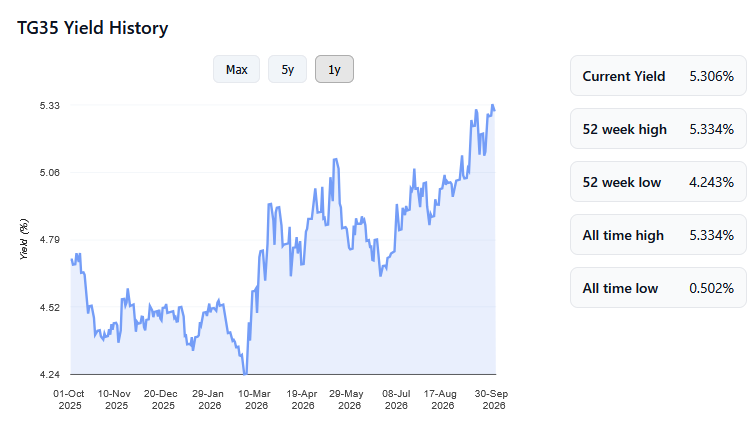
Tg35 is far from a 1 year bond - and its risk profile in past if not i hope now not suitable for short term holdings.
offering fairly flat to very negative (c18% drop) returns over a 1 yr window over last 5 years.
And opened about 0.40 - 0.6% - down this morning. Typical after I topped up my ladder 5k yesterday. But its a hold to par for me unless…..
might get out shorter term with better returns and not hold to maturity - if peace, intlation and rates return to lower levels - part of that 18% could partially reverse to best ytm - but that gamble onba small fraction of investments doesnt make it a good recommendation for this thread.
PS its currently trading around a c5.3% ytm, a guide if not actual reality, with the usual optimistic caveats (my platform charges for drip, tax on coupons etc).
Is your 6% a simplistic linear aver (total capital return or total return inc net coupon / total period say ), or a grossed up equivalent (say bond with all return taxed at 20 - soon 22% etc) ?
0 -
Yes should have said 5.4%
1 -
I've bought gilts quite a lot of times over the last couple of years whilst building a gilt ladder to fund drawdown from my SIPP. I know exactly when I want the cash which is when each gilt matures, there is little chance of needing emergency access to the cash tied up in gilts, so I know exactly how much I will receive, I knew the yield at each purchase point and was happy with it.
So I have not done badly and I'm very unlikely to do badly.
loose does not rhyme with choose but lose does and is the word you meant to write.1








Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 356K Banking & Borrowing
- 255K Reduce Debt & Boost Income
- 456.3K Spending & Discounts
- 248.5K Work, Benefits & Business
- 606.2K Mortgages, Homes & Bills
- 179.1K Life & Family
- 264K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards