We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
AI pension advice
Comments
-
Cash, earning 3.7 % would beat inflation 17 times over the last 20 years, barring the anomalies a couple of years ago and once more, only just in 2011
What were the actual attainable interest rates during those 20 years? It wasn't that long ago you had to scratch around to even get 1%.
0 -
That was going to be my reply too.
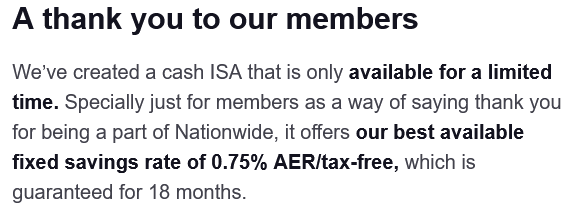
Cash rarely beats inflation. Back when 3.7% was beating inflation, actual cash interest rates were terrible.
Here's an extract from an email that Nationwide sent me in March 2021, for example:
 N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Ofgem cap table, Ofgem cap explainer. Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Best kettle!
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.1 -
YYes, However a typo on my part when putting into AI, current 4 1% for a 2 year bond.
But The plan doesn't stand or fall on .5% on a short term bond pot.
0 -
I am just going by current rates.
The cash pot is very short term and I'm sure there are bigger holes in the plan than cash fluctuations.
And my layman brain thinking, just have 12 month cash then, the other 12 month in 1 year bonds to lock in 4%?
I'm sure a good advisor can negate cash fluctuations
0 -
have you gone back to the AI and simplified the question? I’m confused what prompt you’d have even used to get that unnecessarily complex stepped income plan. All I’d be looking if retiring pre-state pension it’d have to factor state pension in, and perhaps a reduction in income after 75.
something like “I’m planning to retire at 57 and I have 400k in a pension fully crystallised. What gross income would you estimate to be safe to take at 57? Factor in full state pension at 67, and a 20% reduction in income at 75. I understand the DC will need to fund all income from 57-67 and then reduce down as the state pension takes up some of the income need”
in that case chatGPT at least suggested a range of 20-24k with 22k being the middle ground assumnig reasonable returns and ability to be flexible on drawdown if needed
0 -
I'm sure there are bigger holes in the plan than cash fluctuations.
The first hole is that you've got a pretty high chance of running out of money before you reach state pension age.
Here's another cFIREsim run for you, looking at a 10-year retirement (long enough to get you to SPA) with an initial draw of £40k pa gross (so about £2880 a month net, roughly what you've asked the AI to give you).
It fails 24% of the time. So, if you follow the plan, you've a roughly 1-in-4 chance of getting to 67 and having to live the rest of your life on your £12.5k pa state pension alone.
And in roughly half those failures, you run out of money before you reach SPA. Meaning you having to live for up to three years on charity / benefits / loans until your state pension comes into payment.
This is why, in the very first reply to this thread, I suggested a more realistic retire-at-57 income for you would be £24k pa. You'd achieve this by:
- Spending £300k on a RPI-linked annuity. That would buy you ~£12k pa of RPI-linked annuity, which will pay out until you die.
- Investing the remaining £100k in an index-linked gilt ladder that will pay out £12.5k pa for the next ten years. This will bridge you to SPA.
Doing this will mean you've got ~£24k pa, increasing by RPI, guaranteed for the rest of your life.
Here is the summary letter for my IFA from AI
I am sure your IFA will have a good laugh.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Ofgem cap table, Ofgem cap explainer. Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Best kettle!
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.0 -
I did start with something like this and tweaked and adjusted with commands like," I want at least 2750 net for first five years" etc and it kind of evolved
0 -
The whole point is i dont want level income for the rest of my life, I'm not going to be wandering around Angkor Wat when I'm 75, but I will be next year.
I've no idea what Cfiresim is, but my answer to you is you can't give every person the same advice, for a start life expectancy will be different.
I'm not advocating for the above plan at all, but you say a good chance of running out of cash before SP?
The first 3/4 years, the most expensive are covered by the cash and bonds, how badly would the market have to perform for a pot to lose that much by SP?
I get being cautious, especially if financial advice is your job, but at least try to be objective.
0 -
I just typed more or less word for word what you suggested, and yes the answer was more or less the same.
It then asked if I had a cash buffer and what the pot was invested in.
I replied 50k and a classic 60/40 split and it's gone straight to the 3 bucket approach in my original post, cash, bonds, equities.
0 -
You think AI is objective?
You are like many - 'critique my plan' and get all defensive when the flaws are pointed out.
I'm no expert but I do know that the many regulars on these boards know far more than you or I will ever do so instead of being dismissive maybe listen.
1













Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.5K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards