We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Vanguard Life Strategy Blended Low Risk 20% stocks/80% bonds



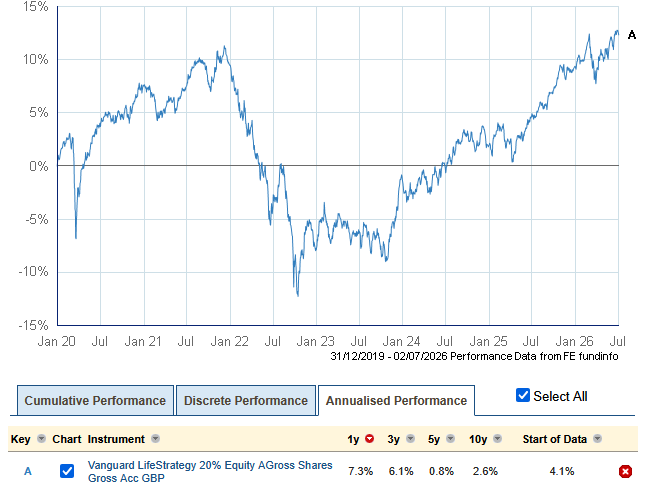
My wife invested £35K in 2020 ,although low risk this plan made a loss until 2026 when it eventually produced a gain of 2%NB this was an investment in Vanguards General Investments Fund.This year[April] in order to simplify our investments she decided to transfer this fund to Hargreaves Lansdown, and close the Vanguard Acct, as she has some investments.in the form of stocks and shares ISA with HL.She is wondering whether it would best to sell her Vanguard holding of 226.4989 units,and invest in another HL fund.She is in her mid eighties like myself, her husband.She cannot afford to sell if there is to be a loss,because of our ages we dont have much time for a new investment to make a profit!.If theres anyone out there who is in a similar position or could give us some alternatives.?Thanks for reading this thread M and M
Comments
-
In 2020 interest rates were very low, so the 80% that was in bonds did not return much. When interest rates rose, the bonds fell in value. That is water under the bridge. The fund has since been recovering and the bonds are now giving decent returns. If you want to stay low risk with only about 20% of your investment in equities, I do not see any reason to switch. Do you have anything in mind to switch to?
 0
-
Bonds are quite often misunderstood as being low risk and they can actually be quite volatile themselves as you've seen. You've unfortunately hit almost the worst ever time for them in the bond crash over that period.
Drawing a line under that, what you do next really depends on your goals. You clearly have low risk tolerance I can see.
If it was me personally at your age, I'd be looking at 2 options:
- Leave it as is. The yield to maturity of your bond component is now likely to be around 4.8% which is pretty decent. The return though is likely to better than you've seen in the past. Though bonds are still volatile and it is possible the value of your investment could fall again.
2. Move your investment to a leading Cash ISA for the certainty of the return that provides (which at the time of writing is more or less at par with inflation).
Others may have better suggestions. Good luck.
0 -
.She is wondering whether it would best to sell her Vanguard holding of 226.4989 units,and invest in another HL fund
There are a lot of Vanguard funds and quite a lot of HL branded funds ( and thousands of other funds on the HL website). The branding of a fund is not important - a HL fund with a similar equity/bond split ( 20/80) will always perform very similarly to a Vanguard fund with a similar split.
So the real question is do you leave it as a 20/80% split fund, or do you instead move the money to cash savings?
0 -
She is wondering whether it would best to sell her Vanguard holding of 226.4989 units,and invest in another HL fund.
Generally speaking, own branded funds of platforms and providers tend to be fairly weak, either in cost or quality.
One of the things about investing on a whole of market platform is that you have access to the whole of market. So what good reason would there be to stick with an own brand option?
,although low risk this plan made a loss until 2026
It was low volatility rather than low risk.
Investments will act within their normal expectation around 95% of the time. The other 5% that you will act outside of expectation. 2022-23 was one of those periods in that 5%. For GILTs and index-linked GILTs in particular, it was the worst period in over a hundred years. The losses on those were similar to a stock market crash. Bonds collectively have basically made nothing over the last seven years.
we dont have much time for a new investment to make a profit!.
Going 20% equities and 80% bonds wasn't really reducing risk. It was piling high on an asset class that was expected to perform lower than it had done over the previous decade. Nobody expected the speed of the unwinding of the post credt crunch gains caused by quantitative easing. I think everyone was hoping for a longer-term reduction to bring it back towards the long-term average. However, external events sped it up.
Bonds play out typically over a longer period than equities much of the time. So whilst bonds are worth the same as they were around seven years ago, they have beaten cash since 2011. So when you invest in bonds, you are talking long term rather than short or medium.
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.4 -
You could maybe think about using a mix of funds to achieve the same equity proportion. More effort, but gives you more control. For example, 20% in a world equity index fund, 40% global short term bond, 40% money market fund.
Vanguard have quite long term average duration on the bond part of their funds which is more sensitive to interest rates. Going for shorter term bonds reduces the volatility a bit.
0 -
Thanks to everone who replied to my thread,i am considering what has been said,and i will probably leave things as they are at the moment as we have both used our Tax free ISA investments for this tax year.
0









Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards