We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
TG30 - 0 3/8% Treasury Gilt 2030





Apologies for the basic nature of this post, but from a complete novice perspective I'm just trying to get the fundamentals right.
I have some cash savings I'm trying to redeploy into various 'capital preservation' vehicles for a couple of years. Looking at short term Gilts I've identified the TG30 as potentially interesting, but my understanding is limited (non-existant actually!)
It's currently priced at about £85 with 4.3 years until maturity, so in mind equivalent to about 3.75% interest.if purchase and held until maturity in 2030 as I intend. And this return is free of CGT right? However, am I right in thinking there are added incentives of biannual coupons too at 4% or so? I think I may be getting that bit mixed up with the overall yield. Can someone just set me straight? Thank you
Comments
-
Yes you are getting confused. The coupon is 0.38% so nowhere near 4%. The gross yield is over 4% but that includes the capital gain (CGT free as you say) on maturity.
4 -
OK, yes, thanks for clarification. Still fairly sttractive perhaps. It's curious to me how many gilt issues there are, ofen for similar terms, but different yields. TG30 in particular seems interesting, but a couple of other shorter ones too. I'll take another look.
0 -
The running yield - which is the yield you get yearly in interest coupons (of which you receive half, twice a year) for TG30 is 0.441% at the moment.
The clean price is £85.06 and the dirty price including accrued interest, which is the price you actually pay if you buy it, is £85.12.
The current total annual yield (capital gain plus coupons) if held to maturity is 4.17% at the moment.
You can look up gilts, reorder the columns and click on the arrow at the right of each one for more information on this site:
https://www.dividenddata.co.uk/uk-gilts-prices-yields.py
And this site also lists them, with links you can click for more information on each, and it is updated more often during market hours too:
6 -
Thank you, that's very useful information.
0 -
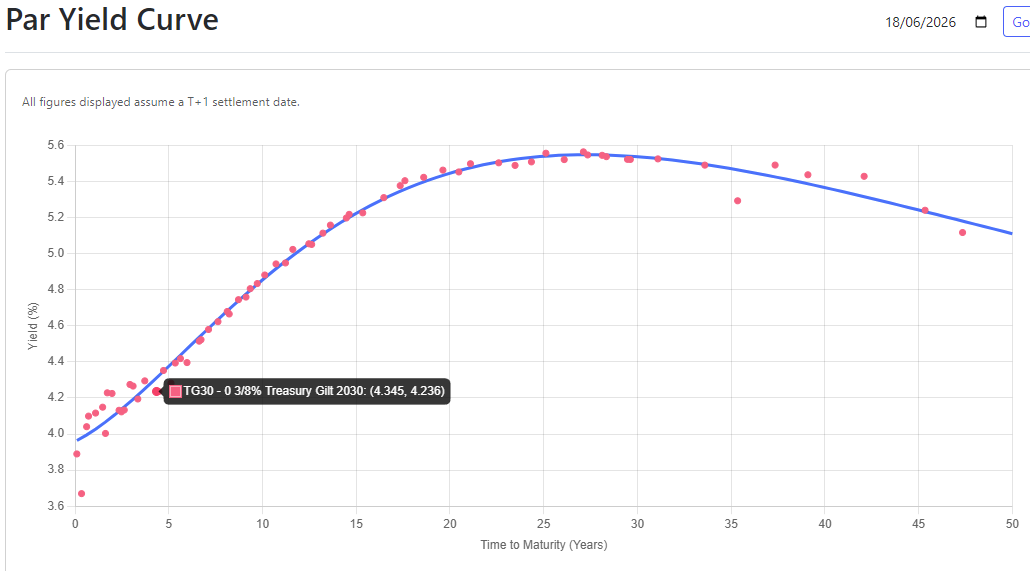
TG30 doesn't look especially interesting to me - it's slightly below the fitted curve but that's pretty normal for low coupon, shorter dated gilts. The curve is a good way of getting an overview of the different gilts and how much yield you get for different durations. This example is from the same site posted above.
 1
-
Thanks, for that. And this is all dependant on holding til maturity I guess. I'll take another look and compare.
0 -
Yes. By holding to maturity you guarantee the selling price of £100 per bond as that's what the government will pay you, plus the coupon payments along the way. If you sell early to someone else they will pay you only what they think the bond is worth for it's remaining time - which varies both up and down depending on what coupons are available on newly issued bonds, how markets think interest rates will vary etc. etc.
1 -
To be fair if you are a basic rate taxpayer and hold the gilts outside an ISA or SIPP then you should look at the net yield column and on that front TG30 is the best of the short dated conventional gilts. T30 for example may have a higher gross yield but its net yield is a fair bit lower.
On the gilts yield page you can play with the tax rate in the box at the top right of the page (just in case you are a higher rate taxpayer). The options are 0, 20, 40 or 45. Presumably next year it will add on the extra 2% tax payable on interest. That hike is another reason to focus on the low coupon variety.
2 -
Yes true, but only by dint of it being the longest duration low coupon gilt that falls into the short-dated category ;) TG31 is even better for only 6 months more duration.. but that takes it over 5-years away.
Pensioncraft have a version of the curve that takes tax into account, though I guess it's quite easy to produce similar from the net figures at gilts yield.
1 -
Fair point. Only the OP knows how long he is prepared to wait for a gilt to mature. I thought I would only have short conventional gilts and anything longer would be an ILG but that didn't stop me buying a conventional gilt maturing in 2056. Just demonstrates a lack of discipline on my part.
0



Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards