We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
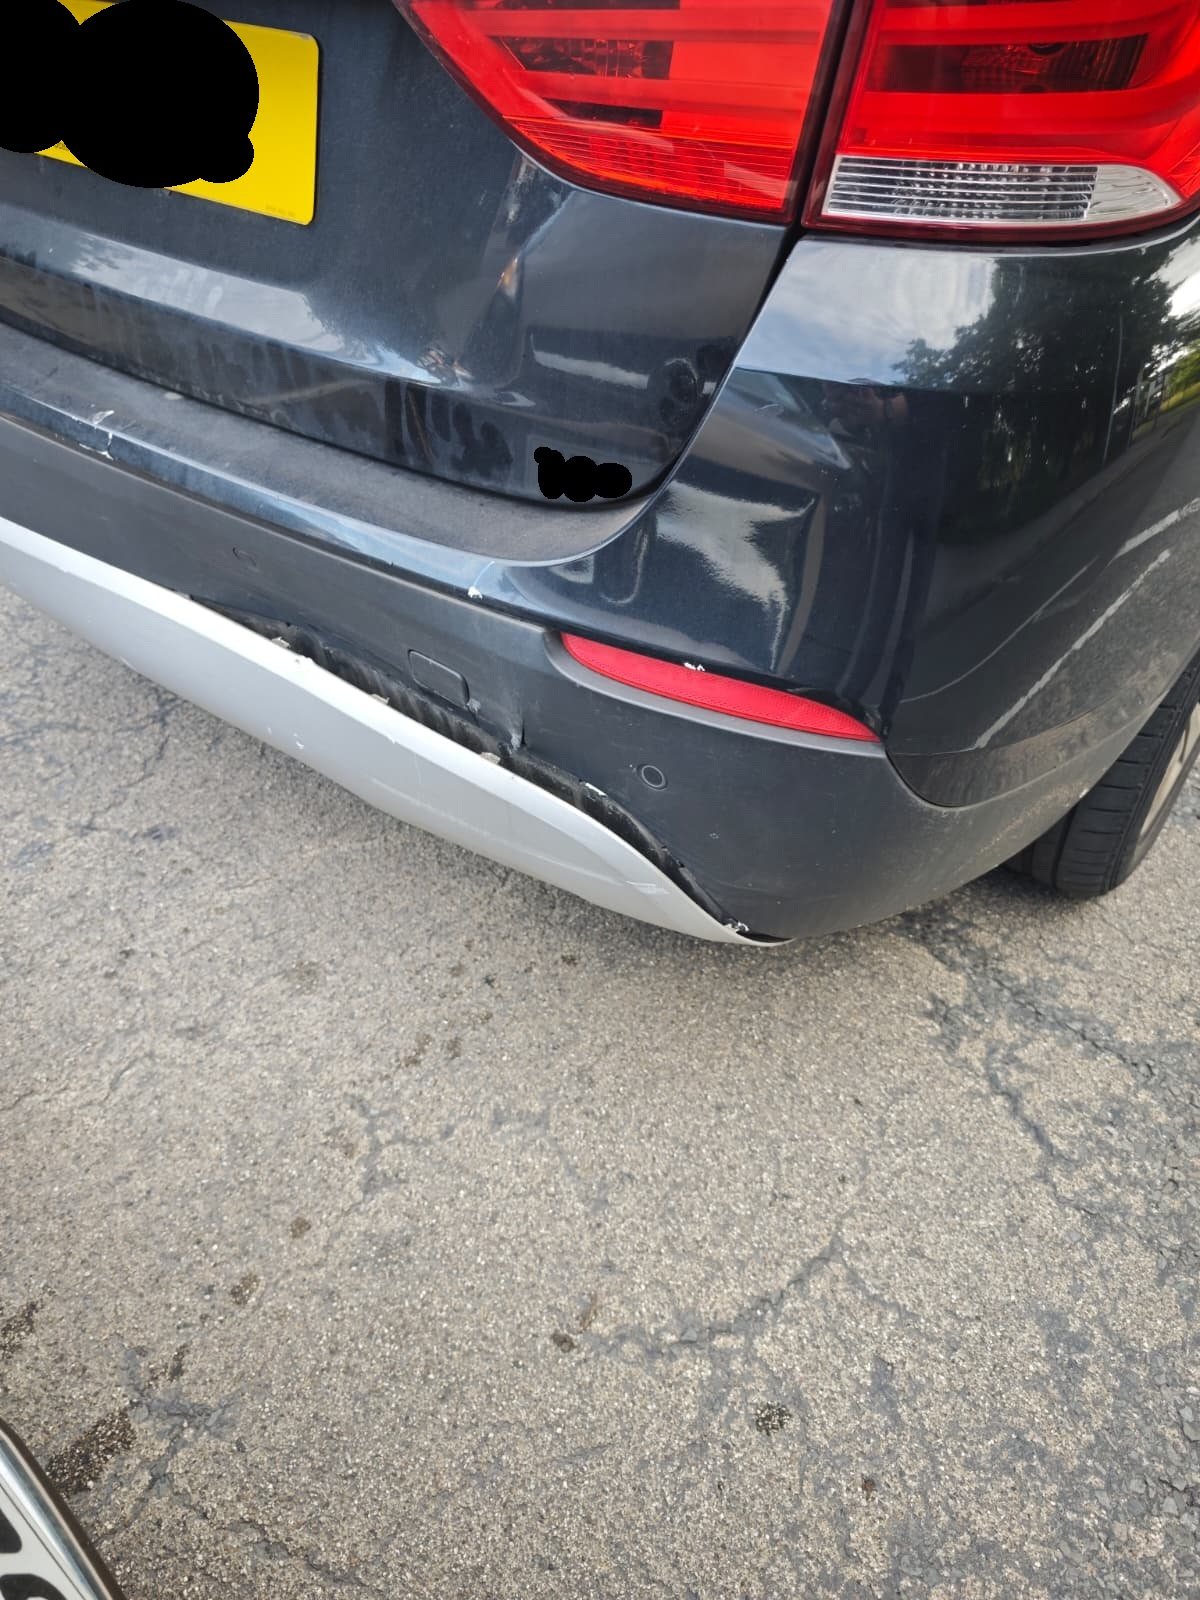
Rear-ended a BMW X1 at 5mph. 10 Years Unprotected NCB. Settle privately or claim?




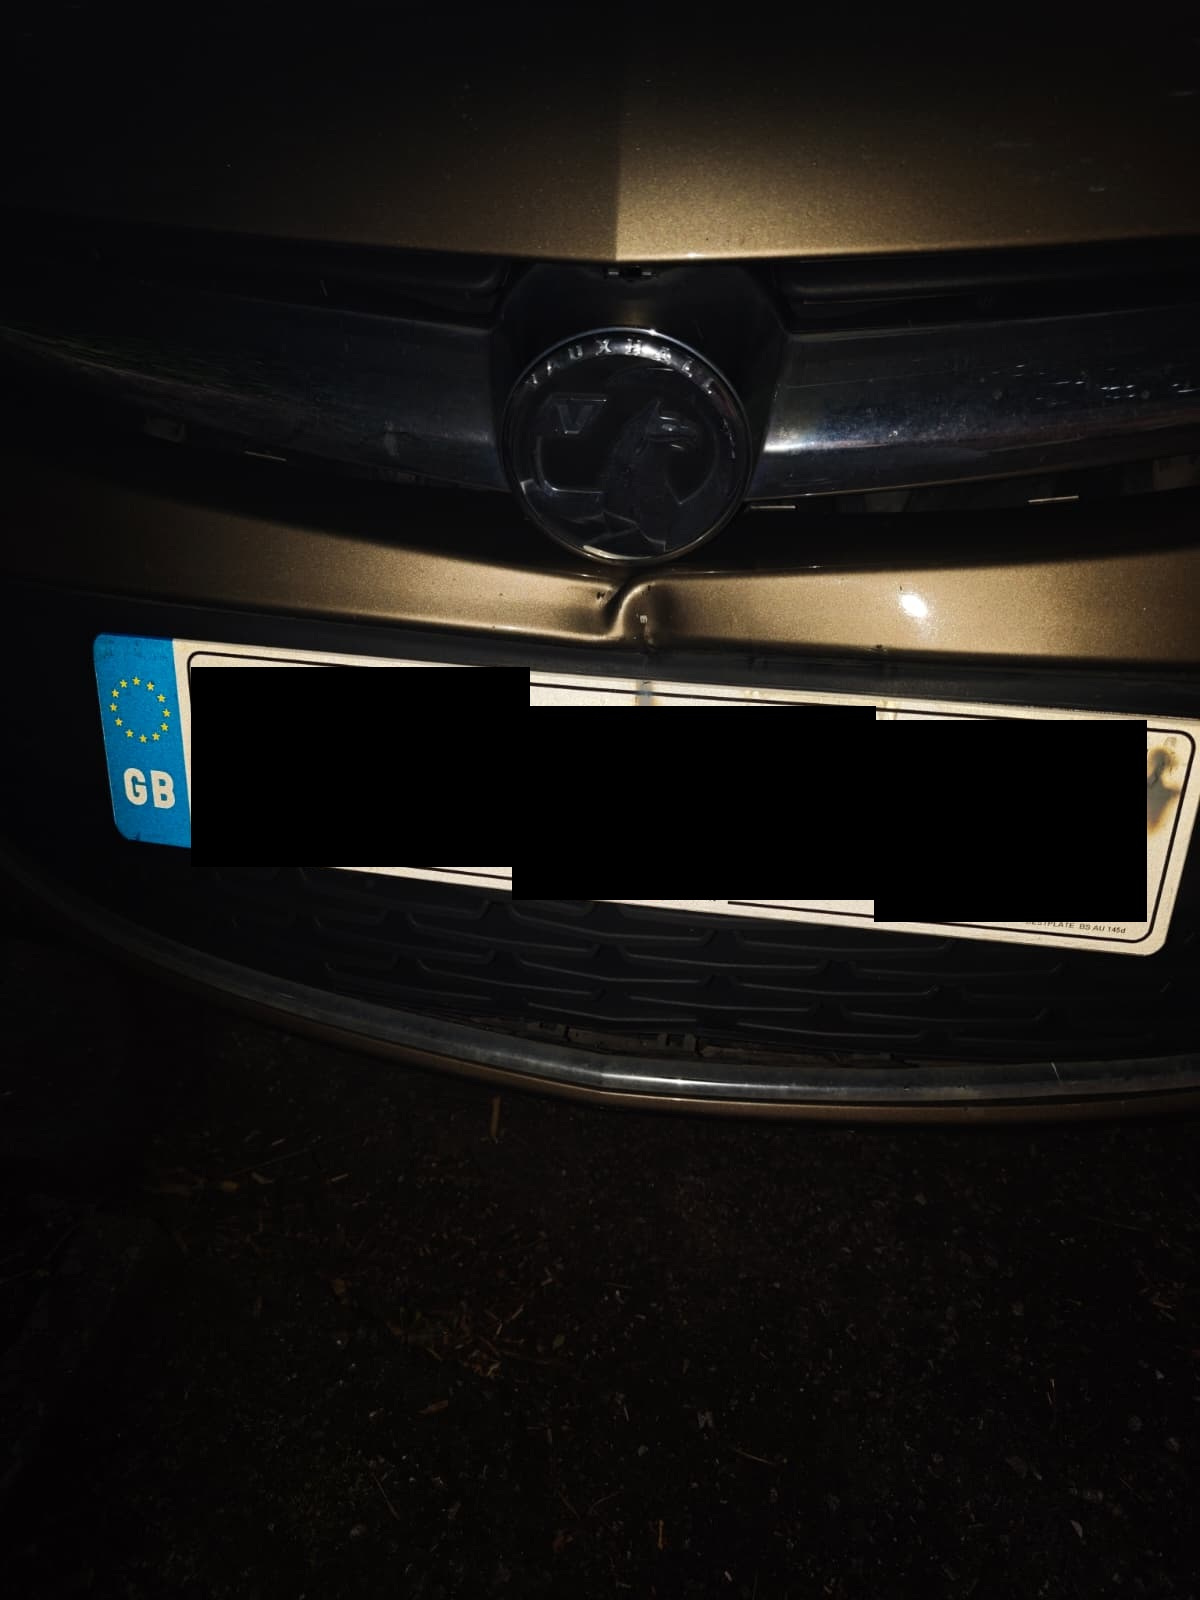
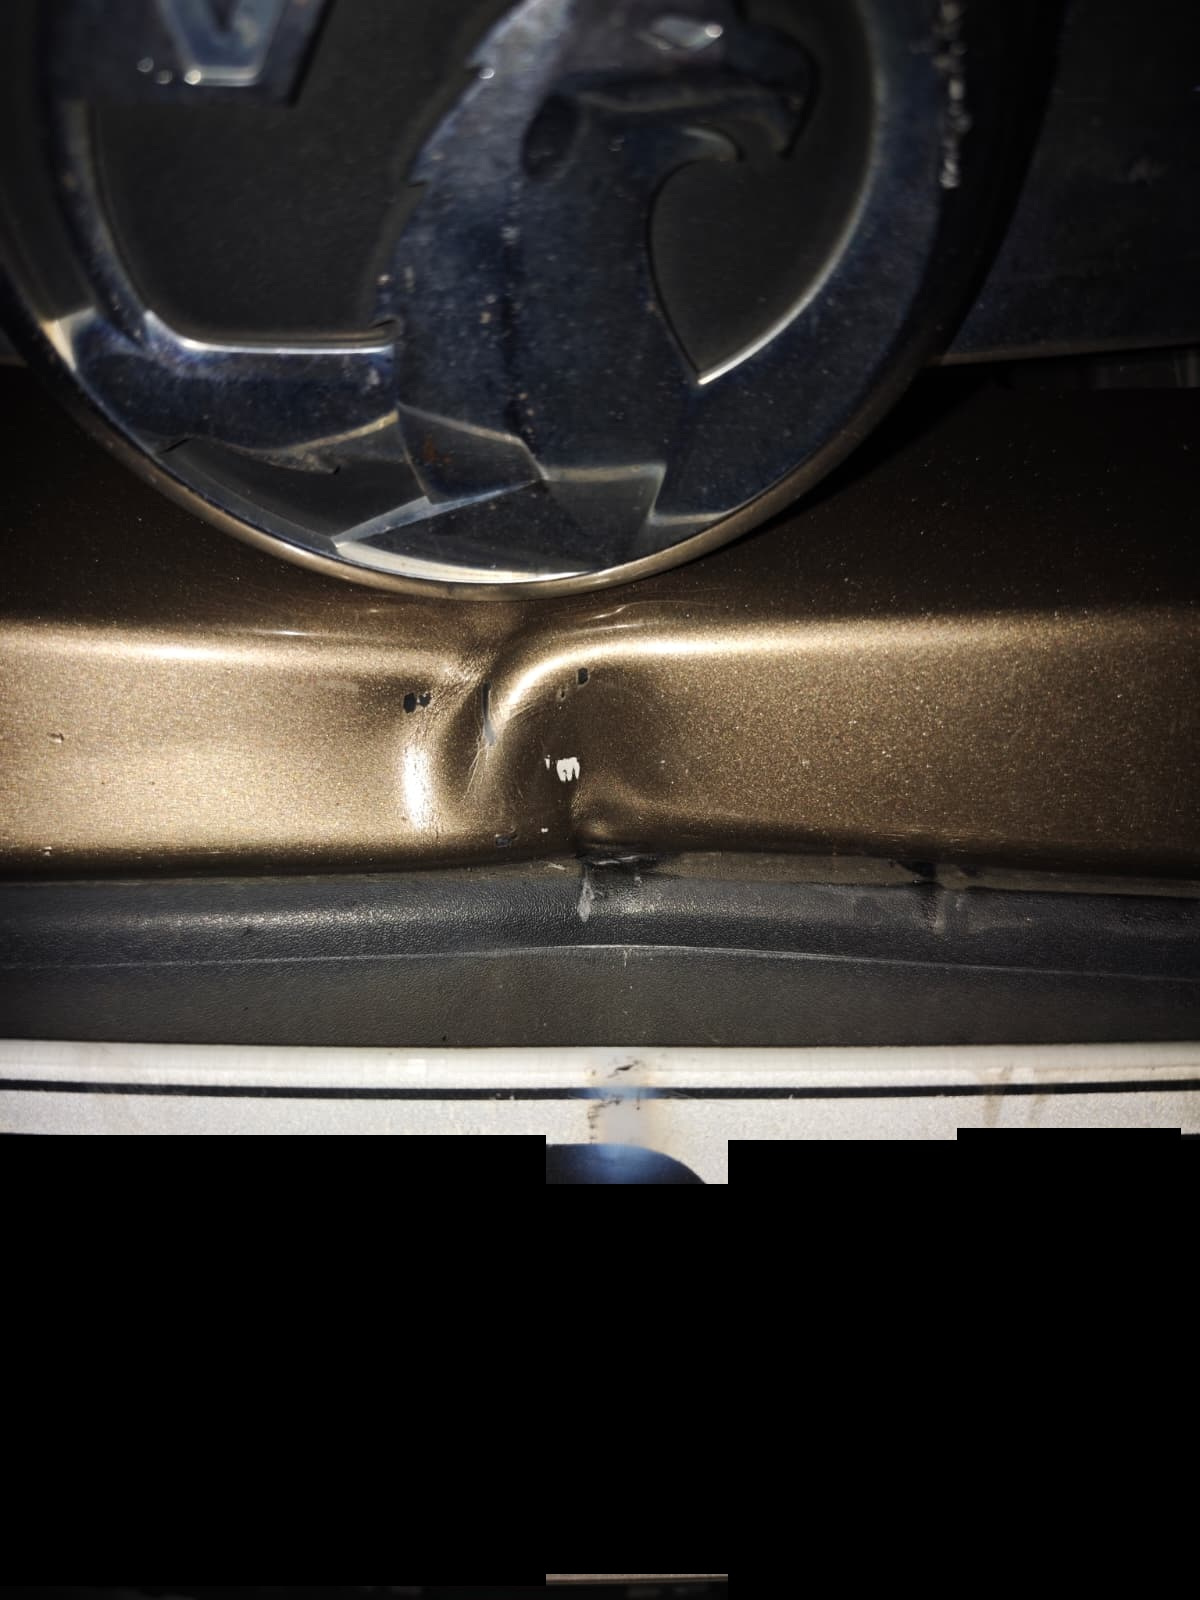
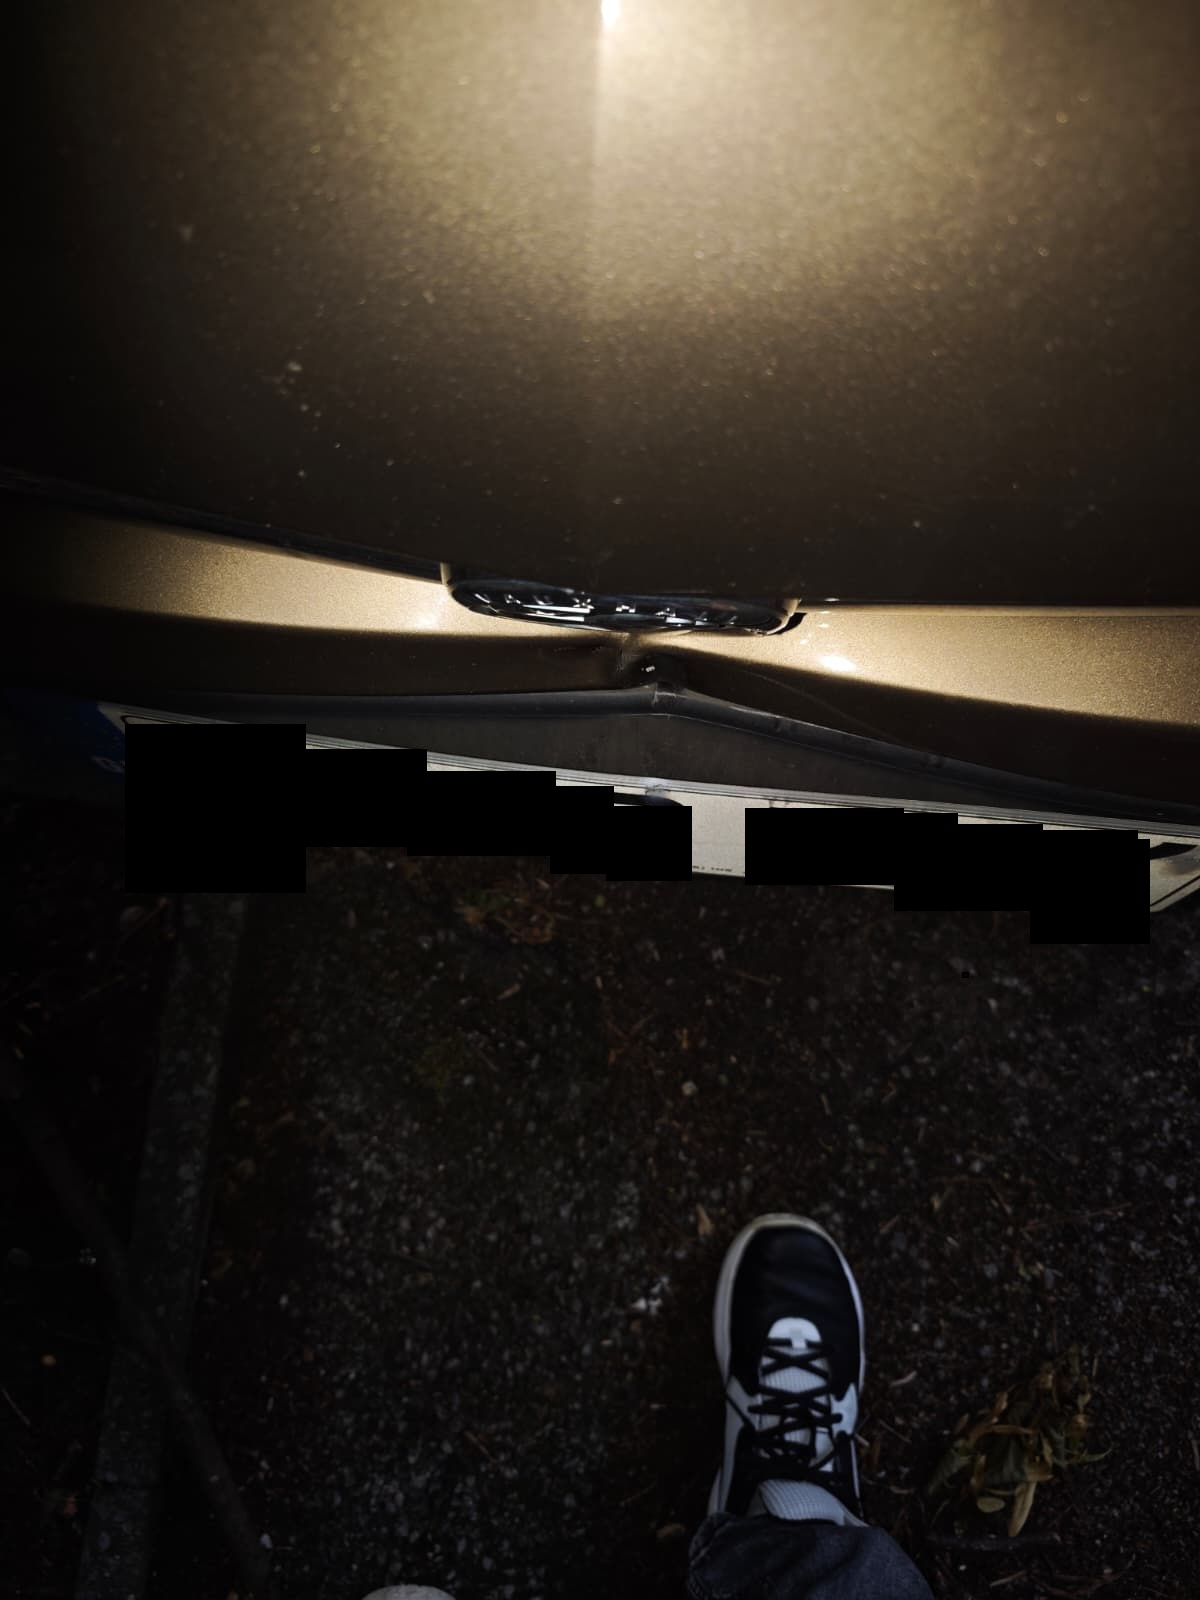
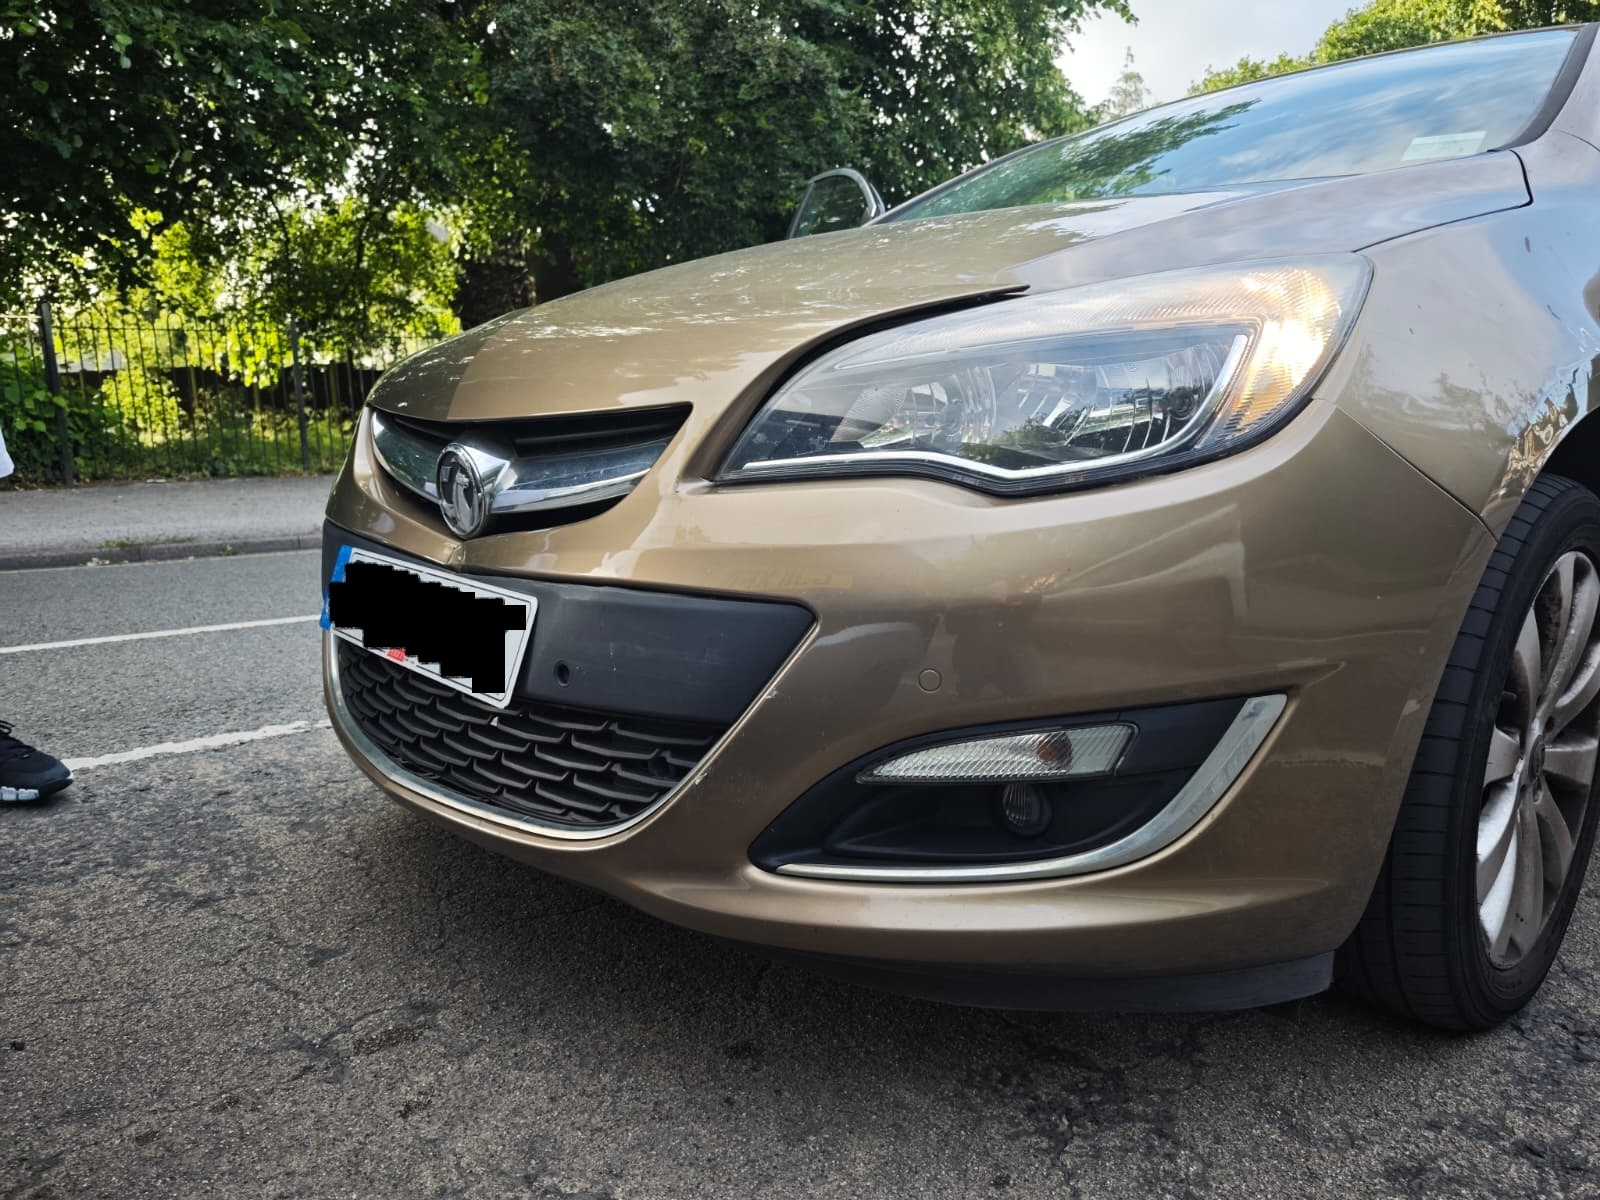
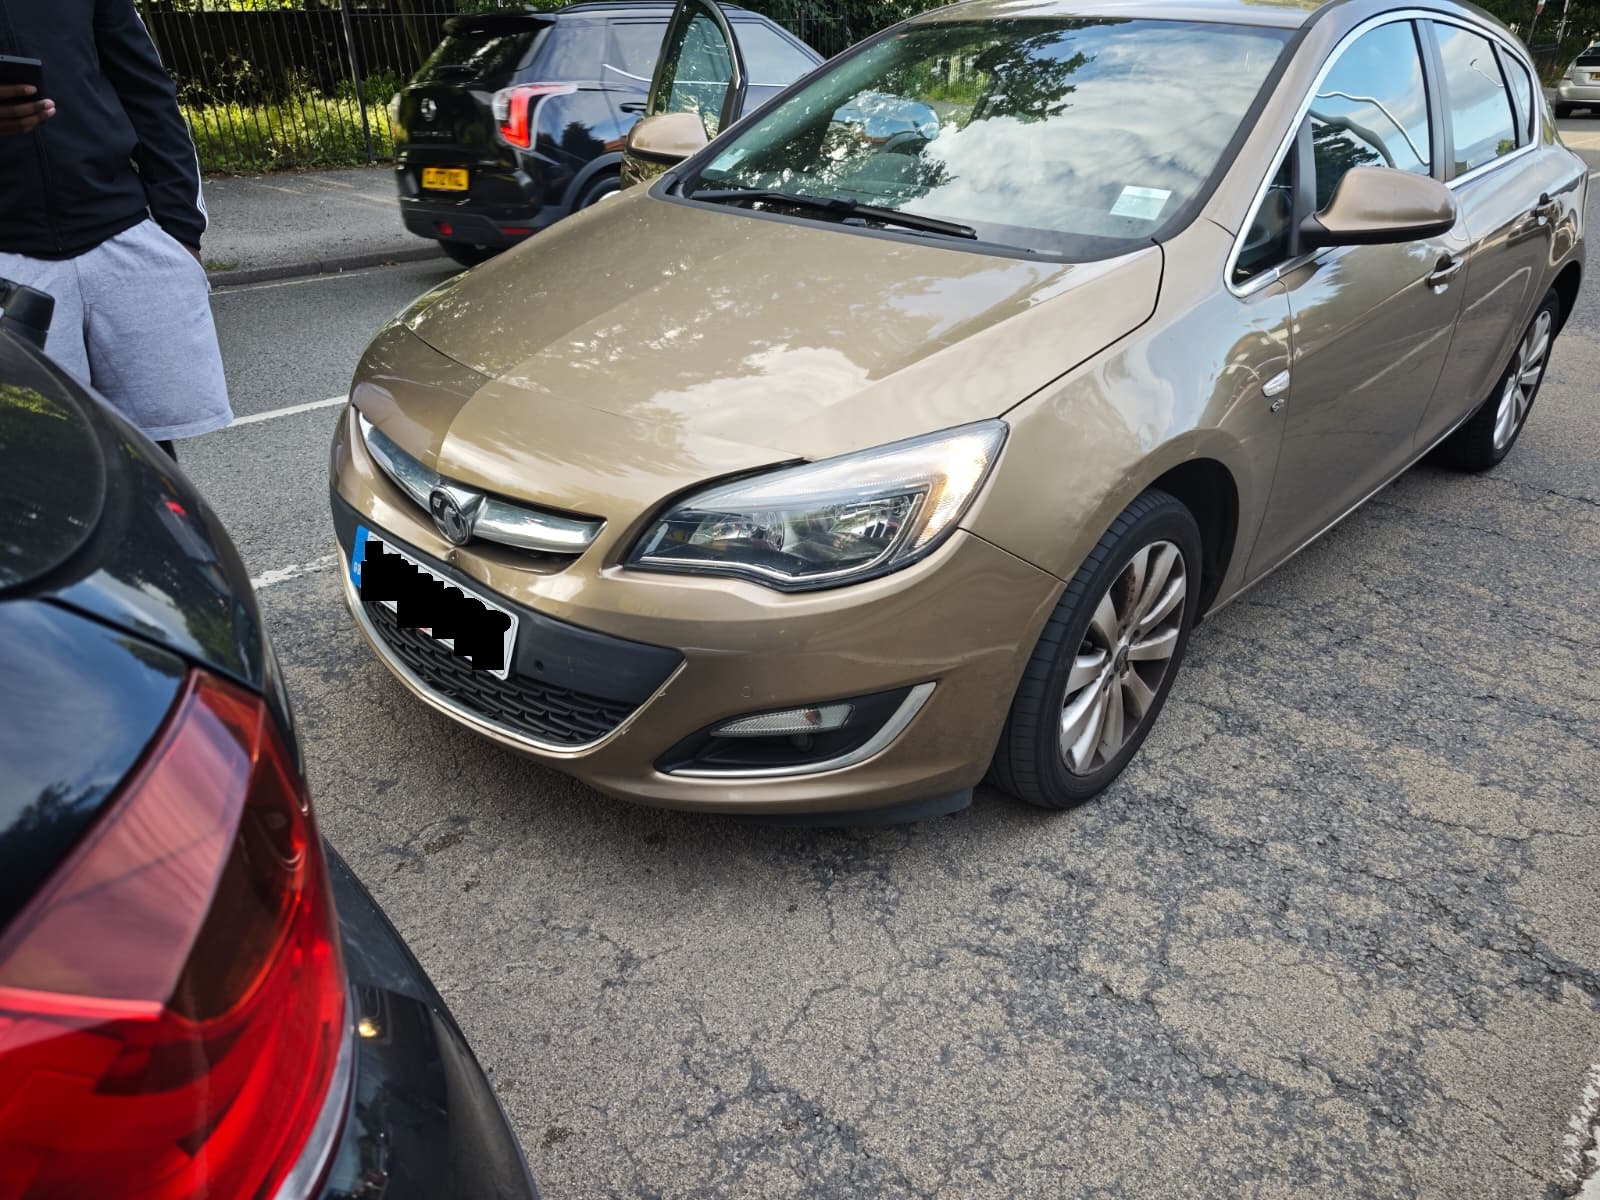
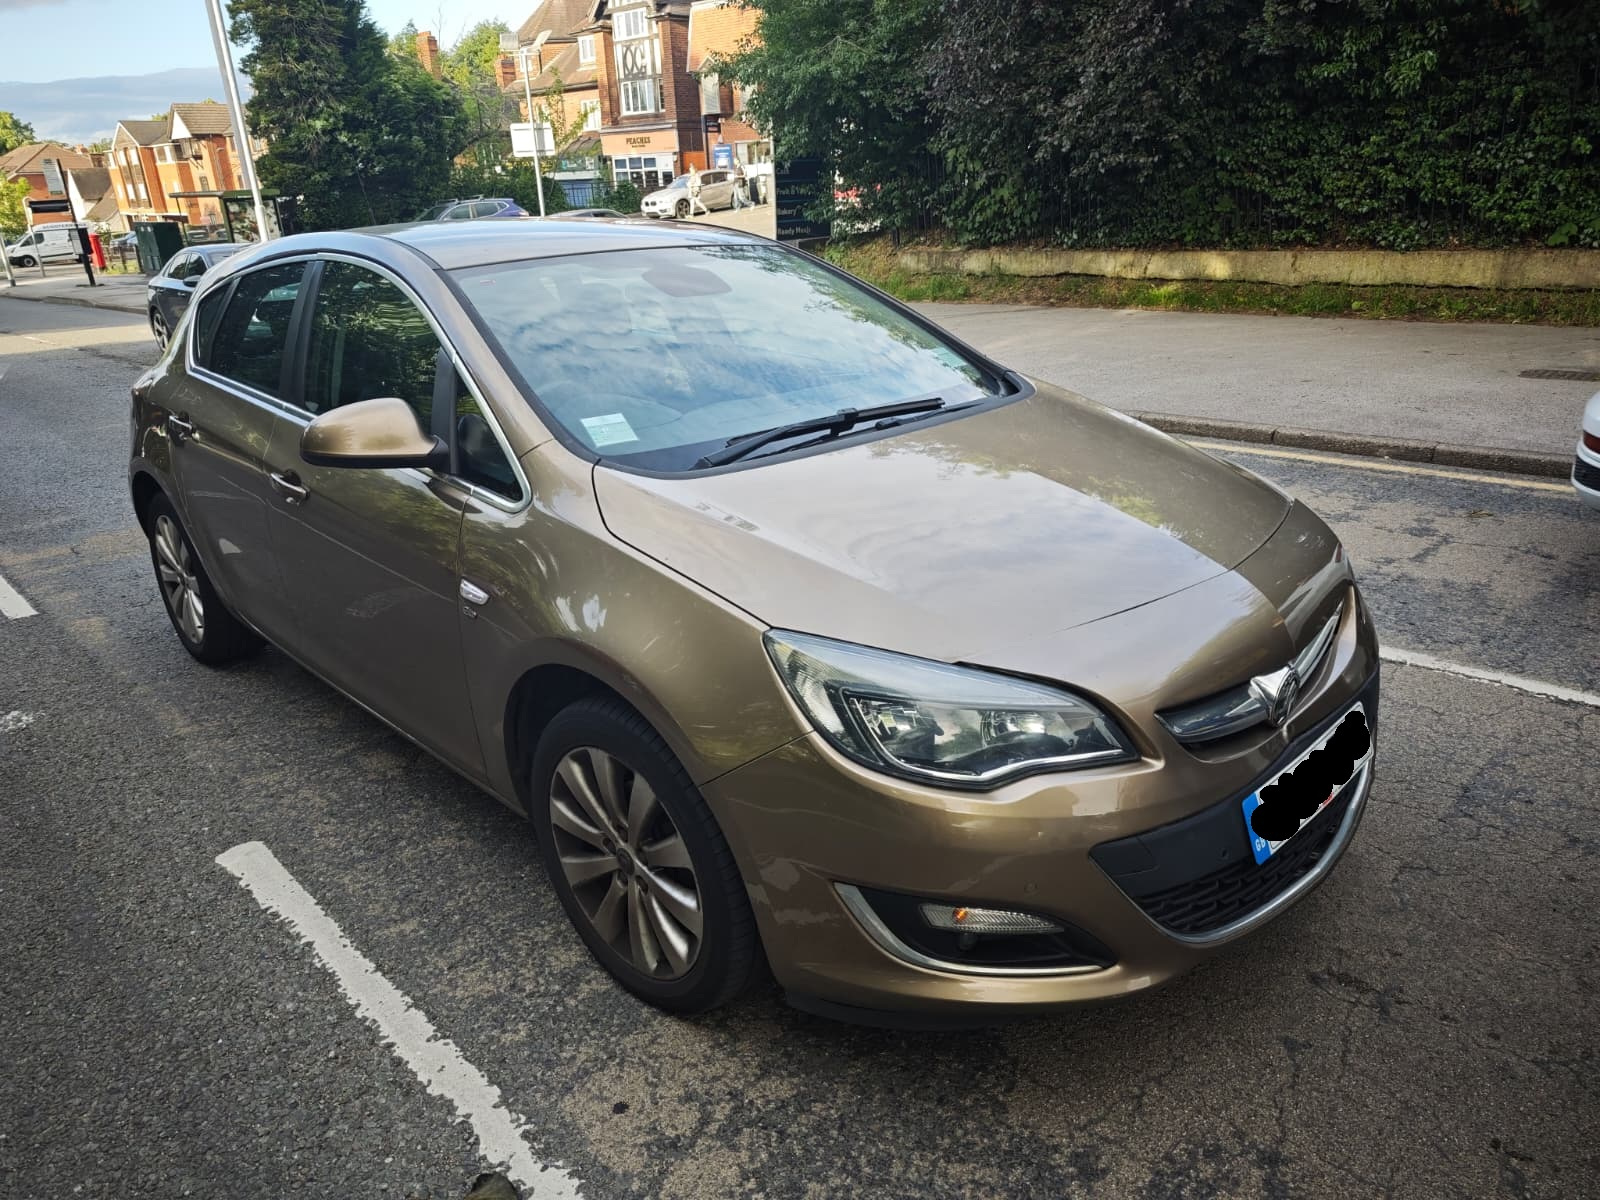
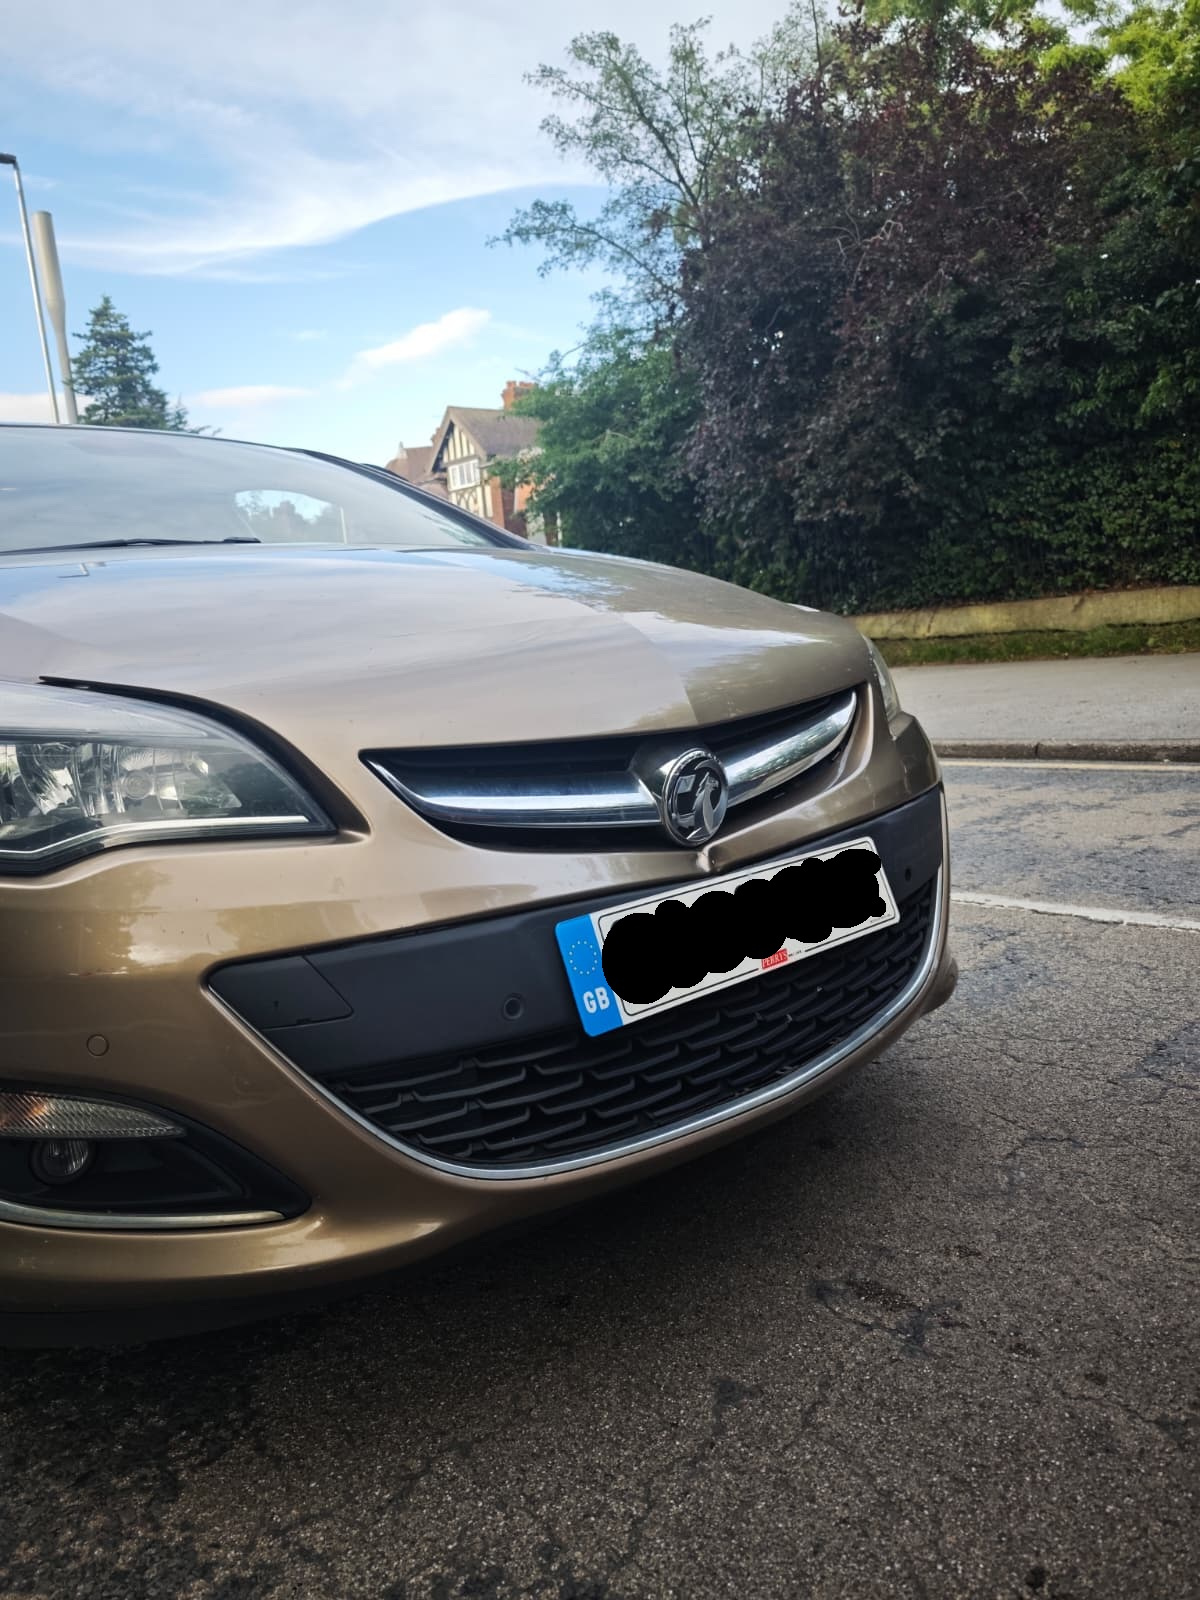
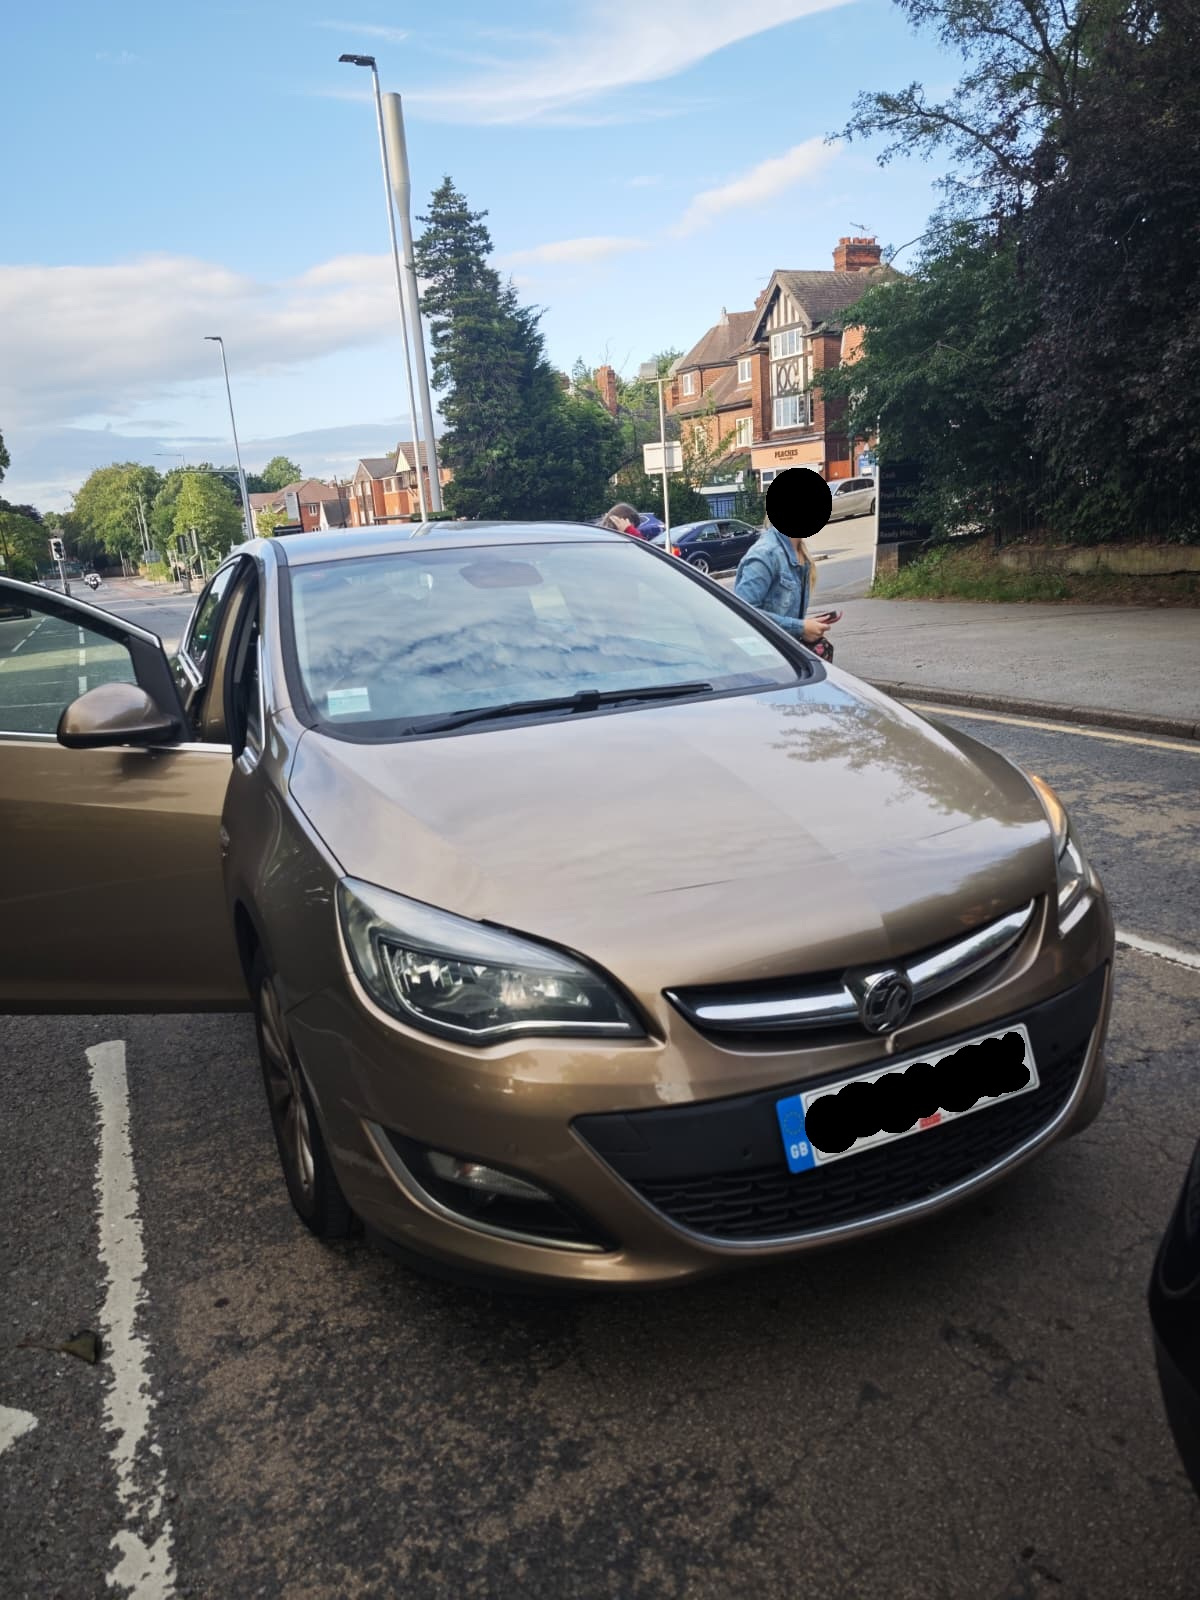
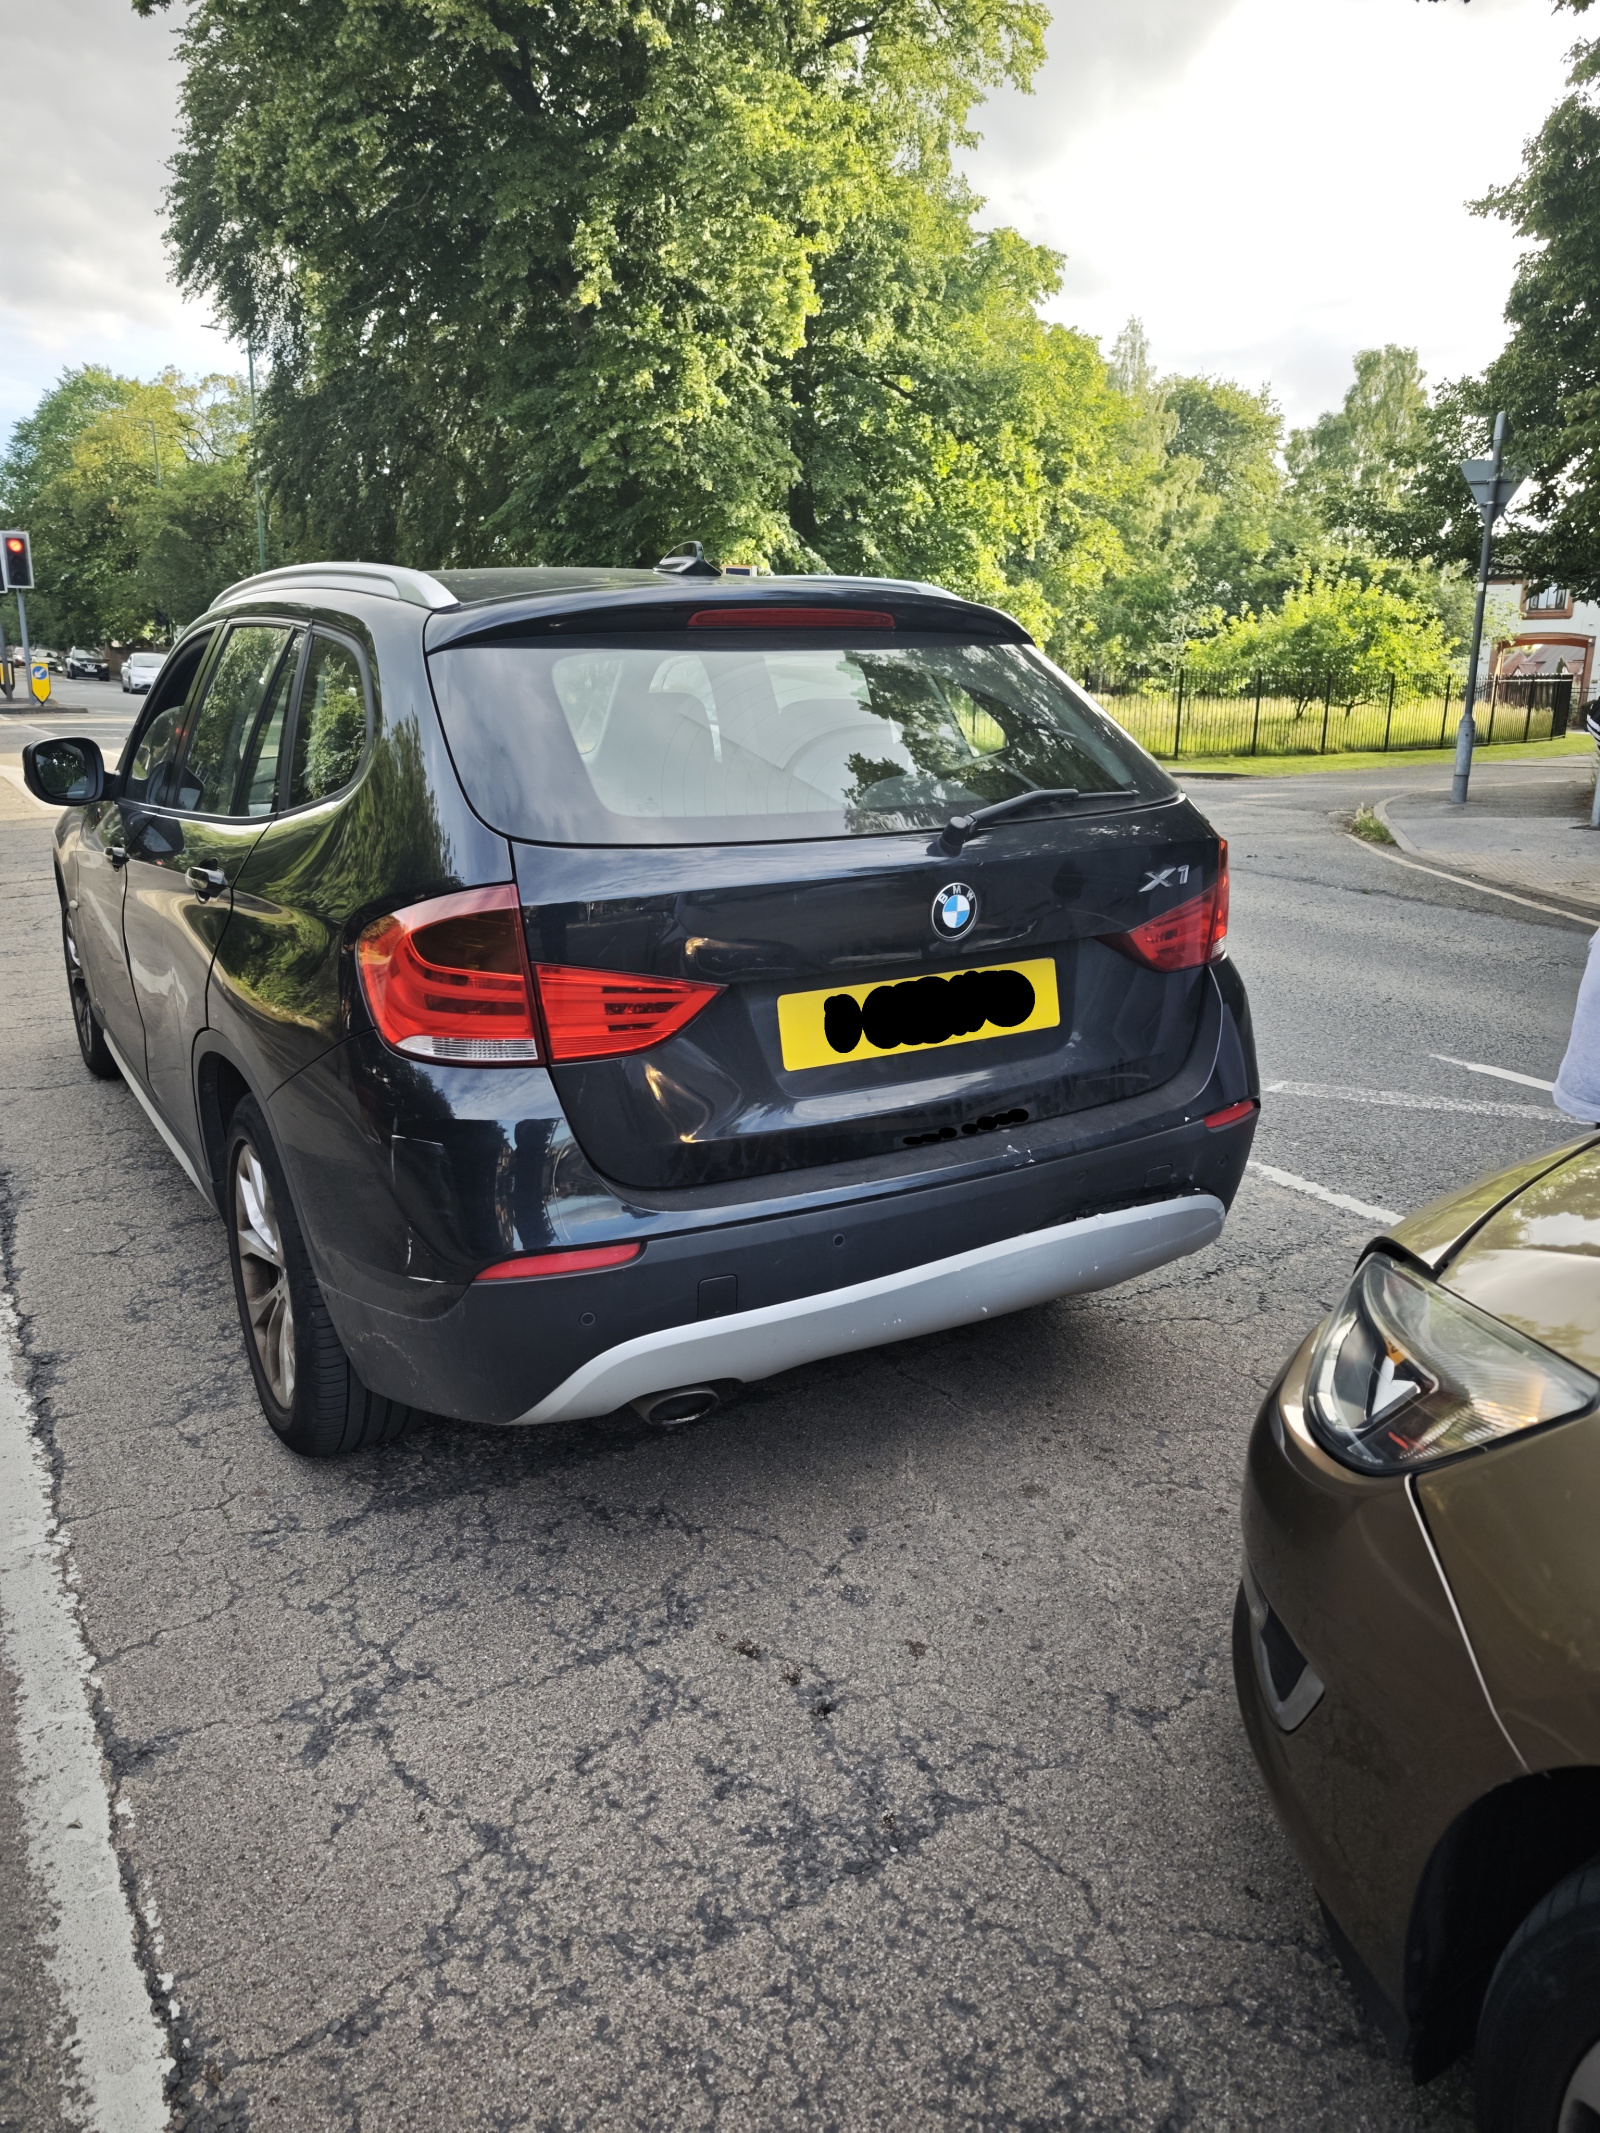
Hi everyone, I need some advice. I had a very low-speed stop-start bump today (moving from a dead stop at 1–5mph) and rear-ended a BMW X1. The damage to my car is a dent in the middle, sides of bonnet and front bumper. The damage to his lower rear bumper trim is scuffs and a small plastic split. Parking sensors are nearby but look intact.
I have 10 years Non-Protected NCB. I also have a declared 2023 non-fault write-off on my history. I just renewed my insurance with Aviva Zero, comprehensive, excess £250 (GoCompare can cover it). Car details: Vauxhall Astra Elite 2014 (produced in 2013) 1.6 Petrol. There were 3 witnesses in my car as passengers, my wife, 16.y.o. sister and her 15y.o. friend.
The third party has agreed via text to get a garage quote next week for a private settlement. I haven't given him my car insurance details yet, and he hasn't given me his, either.
1. Does anyone have an idea of what a garage might realistically charge for lower plastic trim repair/replacement on a BMW X1?
2. If the quote is reasonable, is it worth paying out of pocket to protect my 10-year NCB, or will a fault notification screw my premiums anyway
3. AI (Gemini) advises logging it with my insurer as "Notification Only / No Claim" to protect myself legally. Should I do this or not? Will this trigger a premium spike on its own?
4. Can I run a quote through comparison websites, adding all my details plus yesterday's car accident to see how much more I would have to pay for the annual premium now? AI says some insurers share quoted data and could prematurely flag my profile…
5. If I decide to settle the claim privately, what document should I prepare? Should I print 2 copies? And then what, should I arrange a meeting with him? I live in Mansfield, he lives in Nottingham, I may go to Nottingham next week, should I just arrange a meeting with him, and arrive somewhere where he is? Should I bring my wife as a witness? Then we both sign 2 copies, one for him, one for me, and that is it - it is now a legal document? What does he have to give me? Is text message (SMS) from him about the quote from the garage enough? Or do I need any official document from the garage? Should I use credit or debit card? Can I somehow send him the document electronically, or is it too much hassle, and I should just go to Nottingham and meet face-to-face?
6. Should I fix my car as well privately or should I make a claim? Or leave it how it is?
7. Should I give him my car insurance details, and ask for his today ASAP even if neither of us going to make a claim?
P.S. Sorry for so many questions, I have anxiety and never been at fault in car accidents before. I am driving for 17 years with no accidents caused by me and never encountered such a situation in my life. I want to settle this, how it should be, and keep going, forget about it. I hope you can give some advice. Please, no criticism, prejudice or mockery. If I forgot to mention something, please let me know.
Comments
-
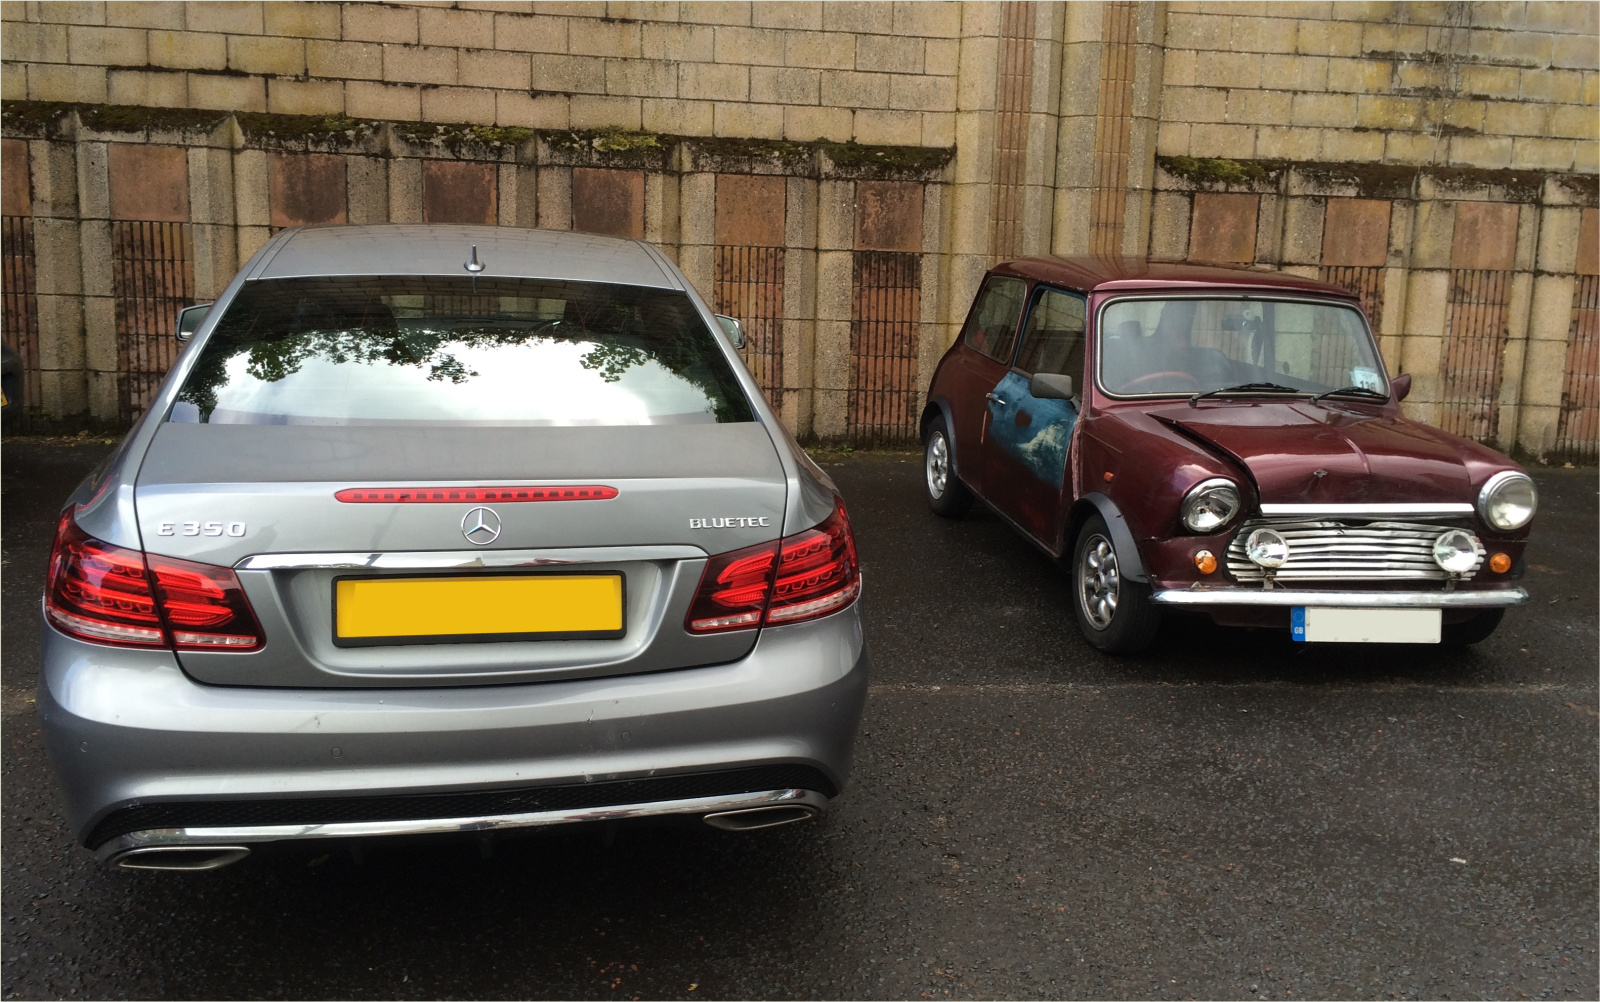
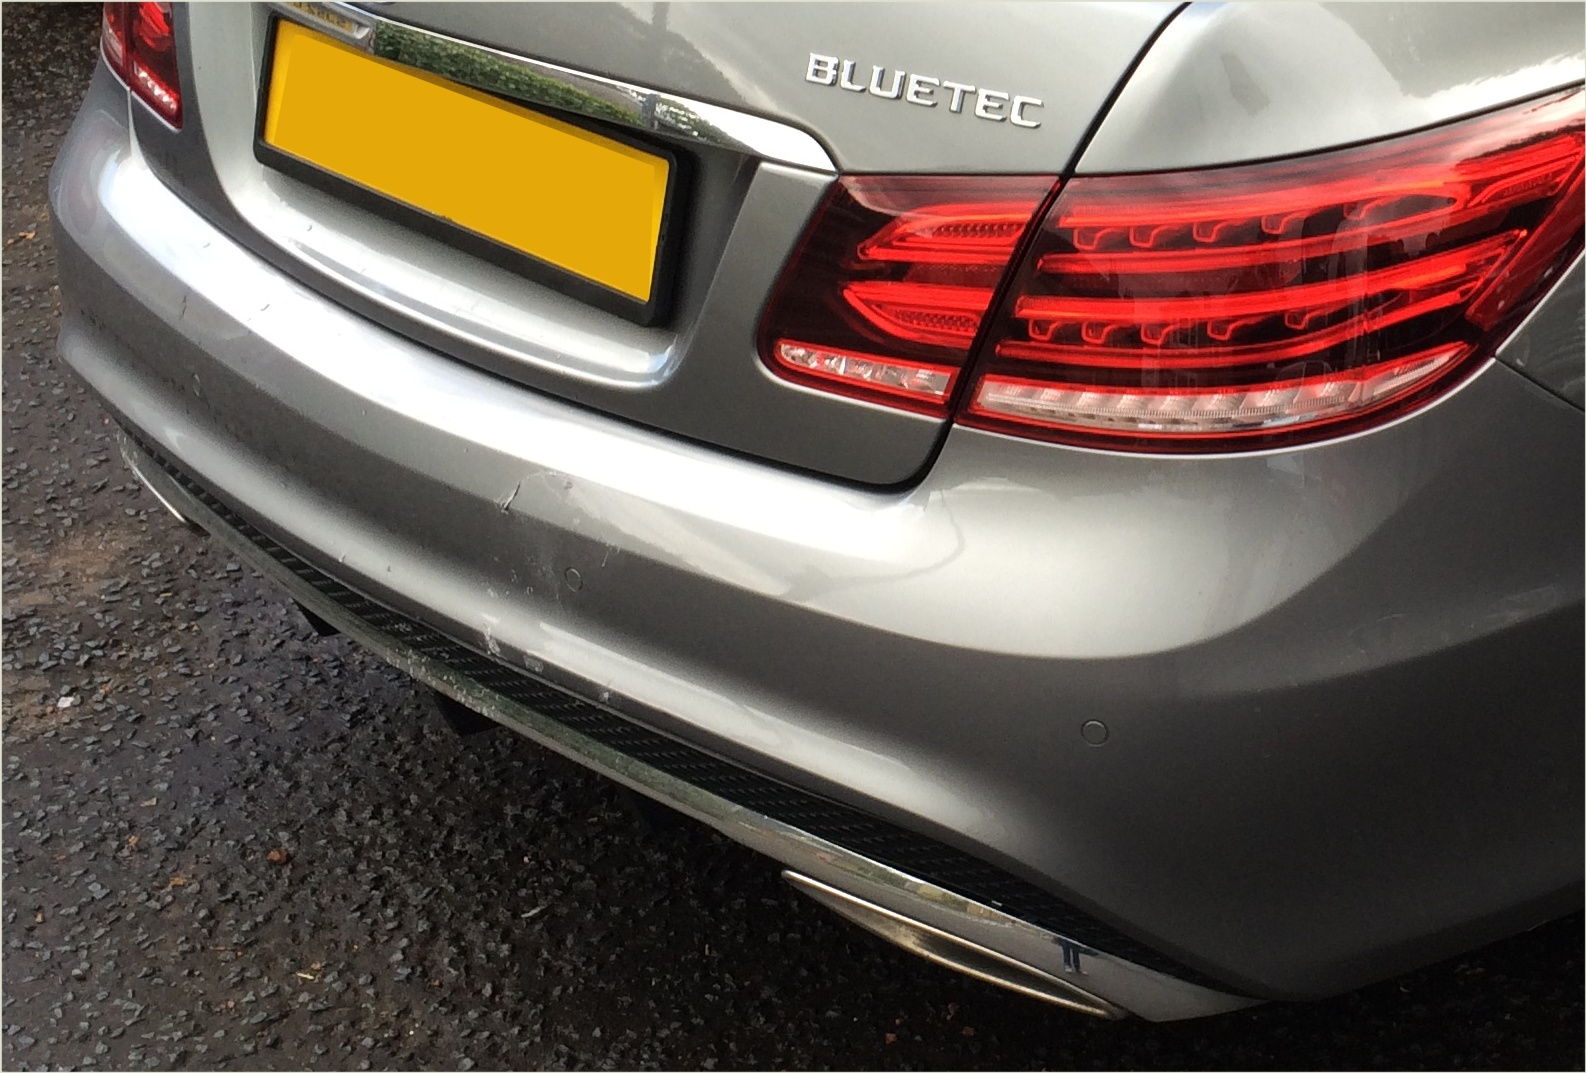
Photos from the accident
0 -
-
What does your insurance say? I'm unaware of any insurance company that doesn't require notification in their terms and conditions. Please check. It would be unadvisable of anyone here to tell you to breach the terms, even if we were to try and settle offline if we were in your place.
If you were to take that route of settling offline, pay the garage directly and get an invoice, and notify your insurance. It keeps a record. If they change their mind and still report a notification (as they should), your insurance would know you didn't tell them. They probably won't terminate the agreement there and then, but they could use it against you in a claim and invalidate the contract you breached.
I remember on the motorway there were 4 cars involved, I was the last one with a slight pump, no issue to my car or the other person, I reported it with no claim, it didn't increase my premium because back then they only asked if you had made a claim. It doesn't mean this would be the case for you, insurance companies have their terms.
I'm FTB, not an expert, all my comments are from personal experience and not a professional advice.Mortgage debt start date 11/2024 = 175k (5.19%)... Q1/2026 = PAID (3.94%)0 -
I'm going back 10 years here, but I was the recipient of a similar accident (low impact, german car, parking sensors etc.) where my vehicle was hit in the rear by a young lad in a mini while I was stationary at a red traffic light, resulting in a similar amount of damage (with regard to the number of damaged parts, your impact looks more severe) all damage was rear bumper down, the lines on the boot lid are just reflections.
After exchanging details I was phoned by the father of the lad who was also keen to settle without involving insurance for similar reasons to yours. As I had only owned the car for about a week before the accident I wasn't prepared to take it to a back street garage for the repairs, so took it to the main dealer. I also explained to the dealer that I didn't want their overpriced courtesy car (which they would usually claim back off the at fault party) as I had a second car, and reminded them that this was being paid for by a well meaning father, so don't take the mickey with the quote as garages often do when they think that an insurance company is footing the bill!
In the end however, the car was still away for a week and the total cost (10 years ago) came to about £2,100. Had I taken the hire car option, they would have added about another £600 to the bill.
I am sure that in the last 10 years prices will have done nothing but increase, and this was without any major structural damage (which can occur even at low speeds).
The main word of warning however, is that even though the dad paid directly, and insurance wasn't involved, I still recieved a letter from my insurance about 5 months later stating that I had failed to declare an accident and that there would be a retrospective charge on my insurance premium, (even though I was not at fault). So this could only mean that someone (most likely the dealer who repaied my car), must have entered the repair into a central system somewhere which my insurance company had access to.
Long story short, you should tell your insurance company even if you don't intend to claim at this point as you, or the other driver, may decide to claim through insurance later once someone has assessed and quoted for the respective damage. This is also unlikely, but the driver may make a whiplash claim or something a few months down the line and you will then have to explain to your insurance company why you didn't declare it.
Probably not the info you want to hear, but this is the best way to protect yourself from any problems down the line.
Here is the current guidance from GOV.UK.
If you’re in an accident
If you have an accident causing damage or injury you must give the following to anyone with ‘reasonable grounds for requiring them’, for example an insurance company:
your name and address
the vehicle registration number
You also need to give the owner’s name and address if the vehicle is not yours.
You must report the accident to the police within 24 hours if you do not give your details at the time of the accident.
You must also report the accident to your insurance company, even if you’re not planning to make a claim.
 • The rich buy assets.
• The poor only have expenses.
• The middle class buy liabilities they think are assets.0 -
An X1 repair isn't going to be cheap and I would guess they want it doing properly. One fault accident with protected NCB may push your premium up slightly but I wouldn't have thought excessively so.
As you are anxious about it anyway, I would simply go through the insurance, let them deal with it and save yourself a load of worry and hassle and suck up any increased premium you may get next year.
0 -
OP's NCB is NOT protected.
Aside of that, it's an insurance job, getting an ad hoc repair agreed to the satisfaction of both parties at a reasonable cost could be problematic.
It needs to be declared in any case and better to do that than the insurer finding out, they could cancel your policy which will make getting insured in the future very difficult as the cancellation will need to be declared.0 -
OP
First of all, I don't need to tell you that you need to tell your insurance, but I guess many don't but that is their risk.
Take it around 2/3 repair centres and see what they say.
IMO - even the repair places you take it too may not be able to give you a quote without having a proper look at the car and even then the sensors may play up etc. They will charge you if they need to reove stuff etc to give a quote.
How old is the car and do you want a 100% repair result or happy with 90%?
What is your excess and what ddo you pay currently for car ins, take those into consideration along with estimates and decide.
0 -
Excess £250, covered by Gocompare. My car is registered 2014, produced in 2013. 90% happy about my car, I am not sure is he going to be happy about his car if it is repaired 90%. Paid for my insurance just 10 days ago £388.54 per year.
By the way, he asked about the garage, I said any reputable one, who can provide written quote, reasonable one, not the dealer. Also, I gave him for just records at this stage, not for claim, my insurer name - Aviva Zero.0 -
OK
I'd wait for a firm quote, as initial ones are often just estimates. VAT can quickly push the total up significantly. For context, our daughter's old car (a 14-plate sports car worth around £15k) was rear-ended by a coach while stationary at lights the coach was traveling about 2/3mph and push her car forward about 3/4 feet. Insurance initially used their system (likely AI-based on photos and impact details) to say it was repairable. But once the garage removed the rear bumper, they found a dented crash bar (Which we told the ins about and the central locking) and other issues (like central locking failure), declaring it a write-off.So even AI estimates can be way off. My guess is your repair will easily exceed £1k inc. VAT, but I hope I'm wrong. Best to wait and see what she comes back with.
Good luck
0 -
I forgot to mention. The accident was on 13/6/26 at about 19:20.
I have asked the other driver about his insurance details. He said, we have our numbers, we can do it later on, over the phone, text messages. So he did not give me his insurance details at the accident
Is it possible he doesn't have an insurance? Should I pay £10 myself to check online if he has the insurance or not?
Or should I still settle things privately if the quote is okay even if he has got no insurance at all?
I have sent him a message about an hour ago, but he didn't reply to me.
Hi ..., I don’t have a specific preference for a garage, but I’d prefer a reputable, independent local body shop rather than an expensive main dealer, just to keep the costs reasonable for a private settlement. Feel free to use a local garage you trust next week, and let me know what the written estimate says.
Also, just for your records, my insurance company is Aviva Zero. This is just for your records, as we are not making any claims at this stage. Could you reply with your insurer name when you get a chance? Have a good Sunday!
0






Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards