We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Barclays buys GoHenry




Comments
-
I heard that Barclays has a very 'mature' customer base compared to the market as a whole.
Obviously trying to get 'em young into the keep net before it's customer base goes to the big ATM in the sky.
0 -
I wonder how much the various boycotts of Barclays over the years may have affected their customer age profile. Especially where children often have their first account(s) with the bank their parents used, so the effect of one boycott could become multi-generational.
It's also interesting that Barclays seem to be promoting their investment platform a fair bit and reducing fees recently - perhaps to entice a slightly younger demographic which might bring their banking with them as well?
0 -
I wonder what's next for Barclays to hoover up.
Let's Be Careful Out There1 -
GoHenry.........never heard of it !
0 -
I never understood the appeal of Henry, idea is great but you need to pay £3-£10 monthly for that account and there is quite a few free ones HyperJar, Revolut, Monzo etc.
1 -
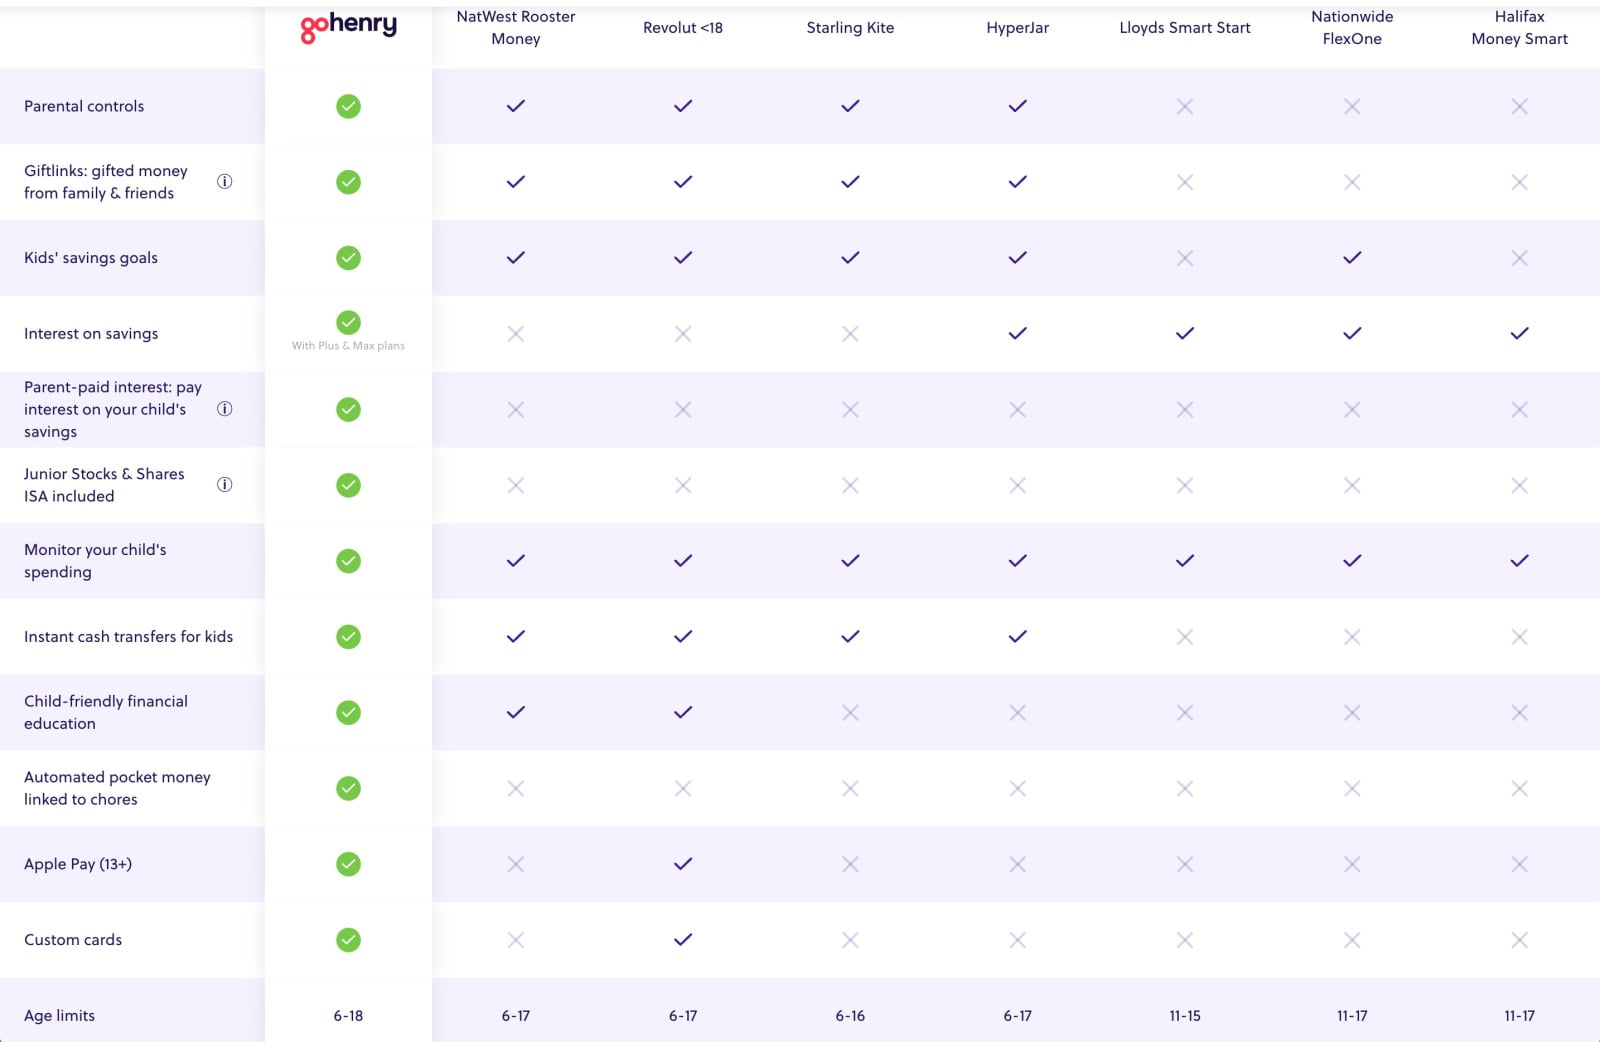
There are loads of competitors to GoHenry and probably more on the way.
I don't get the appeal of it. It's expensive, other banks have their own versions, with no fees, which do pretty much the same thing. Custom cards cost from £5 on top of the subscription (£4 to £10 per month). One of their few unique features is a Junior Stocks and Shares ISA. How many kids are interested in a Junior Stocks and Shares ISA? Another is that they allow kids to use it up to age 18, I mean, what self-respecting 17 year old would still be using GoHenry? 🤔
The cheaper plan allows one free top-up a month, after which each top-up costs 50p. It all adds up quickly if you're giving kids pocket money weekly or rewards for doing chores.
Do we know how much Barclays (over)paid for this acquisition?
I don't see the point of it. OK, they will soon have access to thousands of new child customers and their parents. But what's the plan then? Do they just expect kids to move from the GoHenry app to a stodgy old bank like Barclays when they turn 18 (though I can't really see any teenager 15+ using GoHenry) simply because Barclays own GoHenry? Will they pester parents to encourage their soon to be adult kids to open accounts with Barclays? 🤷 They're much more likely to want to use a more modern, app only bank like Starling or Monzo or Revolut. Maybe Barclays expect that they will follow in their grandparents' footprints? 👵🏻
0 -
@danny13579 as you can see other banks have something similar - Lloyds, Natwest etc. GoHenry had apparently about 300-500k customers.
So yes, creating own product, marketing it would take a lot of time and cost them fortune before they get to similar numbers - so much easier to buy and quicker. I assume it's down to their ageing customers, as you say most are older so this will possibly bring new stream of customers - I've stayed with my first bank for another 20 years - so that's what they would expect from some.
And you see banks battles giving £150 welcome cash just to switch - here potentially 0.5mln 😅
0 -
I could be wrong (this is not an area of savings/banking I am that familiar with) but I was under the impression GoHenry was amongst the first products aimed at kids in the industry, and most of the other banks' offerings are in response to GoHenry.
Barclays are presumable paying for an established brand name (distinct from Barclays and any global crash unease), who are well known in this space, and even the fee element gives it a certain authenticity to the (middle class) demographic using these sorts of products.
0 -
How do Barclays intend to do this? Do they expect young adults upon their 18th birthday to suddenly say to themselves that they're now too old for GoHenry so they're going to open a Barclays account? Do they intend to pester parents through the GoHenry app to encourage their teenage kids to open Barclays accounts as they turn 18? It's app based banks that appeal to young people, not crusty old dinosaurs like Barclays.
I'd guess from age 11 there will be various nudges and incentives to switch to a Barclays account, getting more generous as they pass 17.
I'm not sure all young people only want an app-based bank. They might add an app-based bank, possibly make it their main bank account, but would they necessarily ditch Barclays completely once they've been a Barclays customer for a while?
1 -
Newbie_John I completely get why Barclays are doing this. They want a ready to go system, with brand recognition and a large set of customers already using it. All wrapped up in a nice little package maybe even with a ribbon attached.
Even if they have 500k users, not all of these are paying to use it. It may be a third of these users are parents who pay a subscription fee of between £48 and £120 per year + extras such as the custom card fee (from £5 per card). The kids using it aren't paying anything.
Does anyone know what turnover GoHenry made in their last financial year, and what profit they made?
Also, does anyone know how much Barclays have agreed to pay for GoHenry?
As for staying with the same bank for life or for 20+ years, I think today's generation are far more savvy than our parents' and grandparents' generations who chose to stay with the same bank for life or are just too stubborn and resistant to change to move elsewhere. Barclays just doesn't appeal to young people. It doesn't even appeal to middle-aged people like me. The days of people staying loyal to a bank for life are on the way out. Savvy people know that loyalty, especially to banks, doesn't pay.
From one of the articles quoted by the OP:
GoHenry said the deal would enable its young customers to remain customers with Barclays once they reach the age of 18.How do Barclays intend to do this? Do they expect young adults upon their 18th birthday to suddenly say to themselves that they're now too old for GoHenry so they're going to open Barclays accounts? Do they intend to pester parents through the GoHenry app to encourage their teenage kids to open Barclays accounts as they turn 18?
Even if they offer free cash to young adults to move from GoHenry to Barclays upon their 18th, many will just move the cash over to their shiny new Monzo or Revolut account and leave the Barclays account languishing in the wilderness. It's app based banks that appeal to young people, not crusty old dinosaurs like Barclays.
0









Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.6K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards