We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Employer pension contributions past state pension age



I have been in my company pension for 5 years. I've worked for them for 10 years. I wasn't originally auto enrolled as my earnings were too low, and I requested to join 5 years ago.
I am 66 and have been informed I no longer qualify to be auto enrolled as I am past state pension age, which appears to be correct.
I have asked my employer whether they will continue to pay contributions into my pension if I request to remain in the scheme.
I have been told that they 'probably' will, but that it will be the decision of the new CEO (who only started yesterday).
My research seems to suggest that it would be mandatory for my employer to continue to make contributions under these circumstances, but I'm struggling to find a very clear explanation of this from a reputable source.
My employer has consistently shown that they will only ever do the bare minimum for their staff, so I don't want to give them the chance to dodge their obligations, so if anyone could confirm that it is mandatory for my employer to contribute and point me to a reputable source to back this up I would be really grateful.
Thanks in advance for any help.
Comments
-
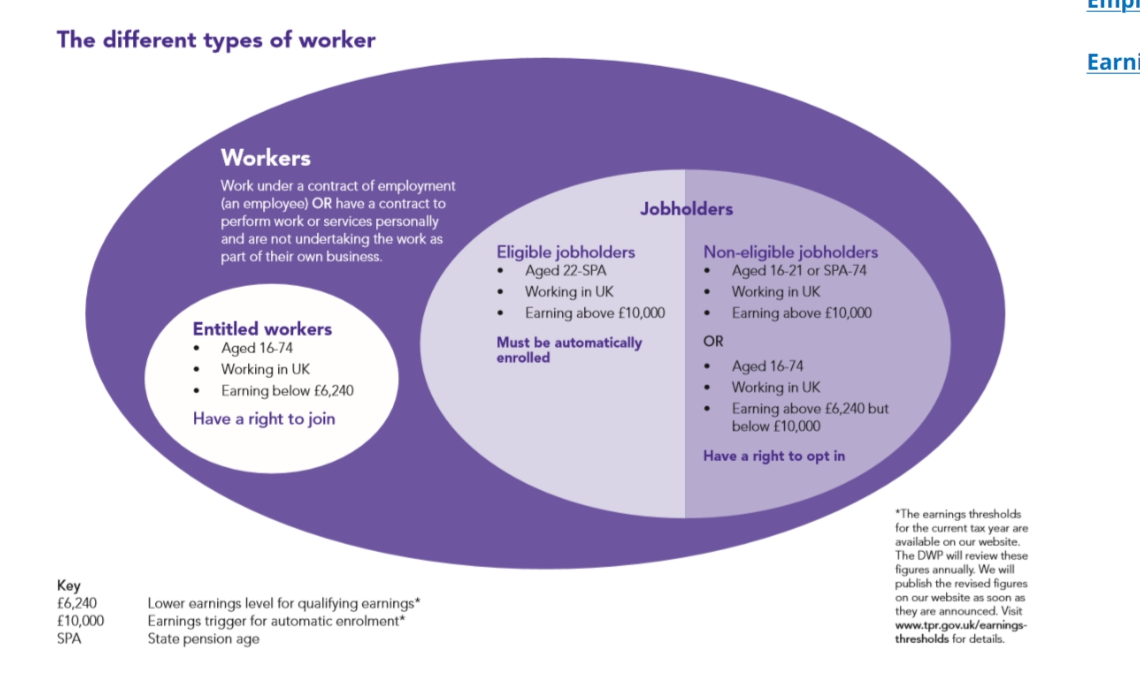
From the pension regulator, as a non- eligible job holder you have a right to opt in, from State Pension Age to 74 years old.
3 -
Yes, I know I can opt in. My question was about whether, if I do so, it is mandatory for my employer to make contributions, as they're suggesting that it isn't.
0 -
Employer duties and defining the workforce: An introduction to the employer duties
eligible jobholders
Non-eligible jobholders do not meet the additional criteria to be eligible jobholders, so do not need to be automatically enrolled. However, they have a right to opt in to an automatic enrolment scheme, if they choose, so an employer still has duties in relation to them.
An employer must give their non-eligible jobholders certain information about both the right of a jobholder to opt in to an automatic enrolment scheme and the right of an entitled worker to join a pension scheme.
The employer must give this information to the non-eligible jobholder within six weeks of the earlier of the date on which they become a non-eligible jobholder or the date they become an entitled worker, eg the employer’s duties start date or, if after their duties have started to apply, the non-eligible jobholder’s first day of employment.
This requirement does not apply if the employer has previously given this information, for example because the employer chose to use postponement in respect of the non-eligible jobholder and gave them a postponement notice.
If a non-eligible jobholder chooses to opt in to a pension scheme, they must do so by giving the employer an ‘opt-in notice’. On receipt of a valid opt-in notice, the employer must enrol the noneligible jobholder into an automatic enrolment scheme by following the automatic enrolment process.
- The employer must pay employer contributions to the scheme.
Detailed guidance no. 6 – Opting in, joining and contractual enrolment provides more detail.
1 -
is there anything further on your link? what you have posted suggests the employer can't get out of their duty but proof would be helpful.
fyi - my last employer (past SP age) was happy to pay in but they were employee focused so even though we were not well paid (charity) they did their best by us.
I’m a Forum Ambassador and I support the Forum Team on Debt Free Wannabe, Old Style Money Saving and Pensions boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com. All views are my own and not the official line of MoneySavingExpert.
Click on this link for a Statement of Accounts that can be posted on the DebtFree Wannabe board: https://lemonfool.co.uk/financecalculators/soa.php
Check your state pension on: Check your State Pension forecast - GOV.UK
"Never retract, never explain, never apologise; get things done and let them howl.” Nellie McClung
⭐️🏅😇🏅🏅🏅🏅🏅🏅0 -
This looks perfect. Thank you.
0 -
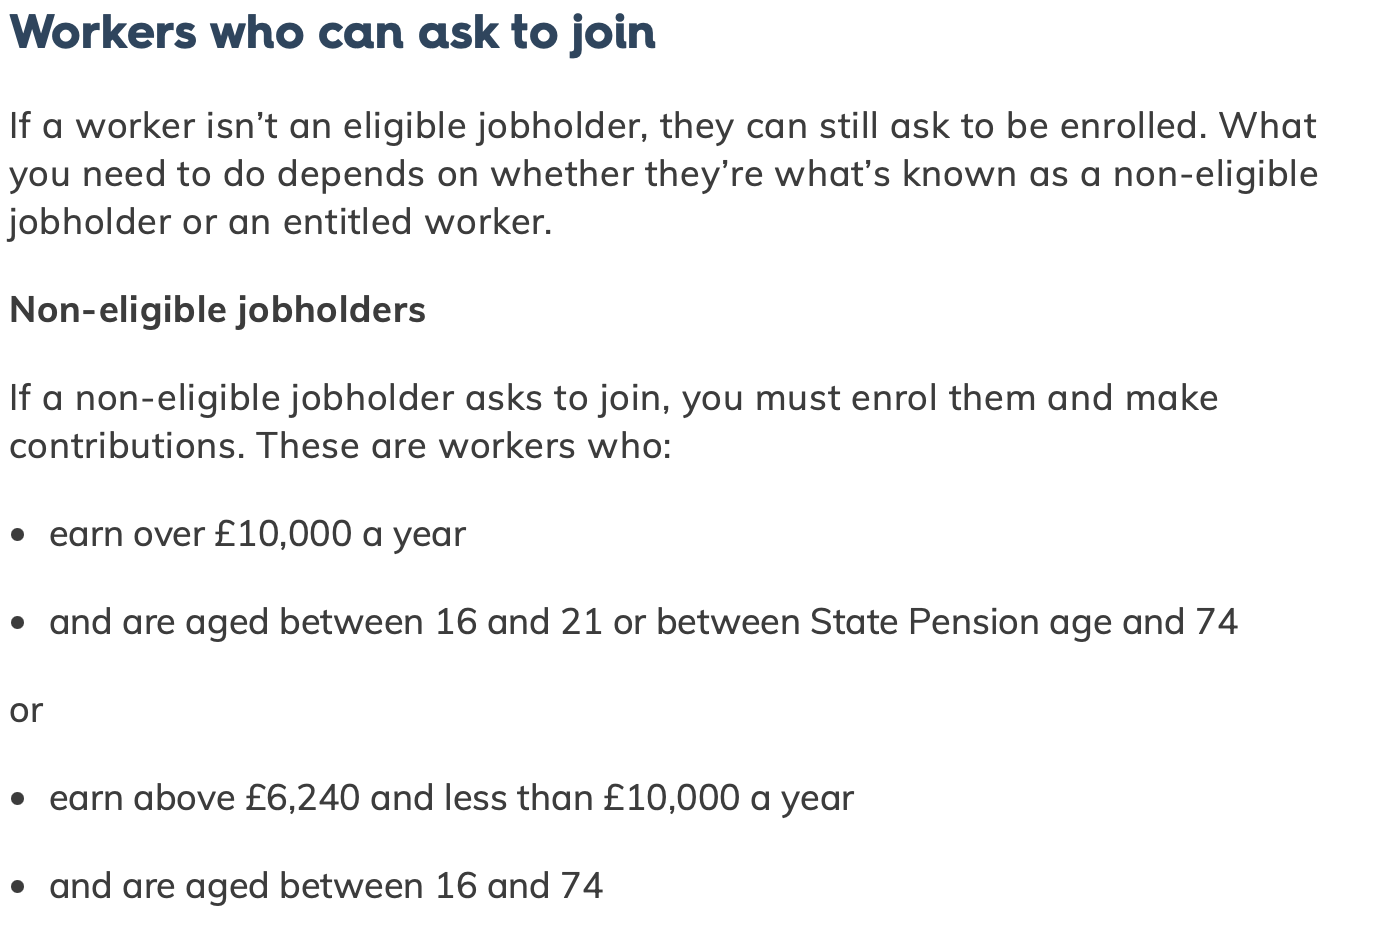
added a new post from the site that says they still have to contribute, no doubt the next question will be how much, but tbh all the rules are on that site so I'm sure they can work it out themselves
1 -
I also work for a charity. They definitely don't do their best for us, sadly.
1 -
Any chance your employer uses NEST? If so they only need to look at this page from the website Qualifying employees | Nest Pensions
and head for this paragraph:
 Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!1
-
No, I don't think they use Nest. The pension is with Aviva. Would I be right in saying that they don't have to contribute if you earn less than £6240 or are aged 75 plus? In which case neither applies to me, as I'm 66 and earn around £10k (enough to be auto enrolled if I was younger).
0 -
I'd focus on what applies to you (as shown above), rather than confusing the issue for your employer by looking at what doesn't apply.
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!1






Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.6K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards