We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
NFU Home Insurance - Help needed!


Good afternoon all
I hope to seek some advice/help regarding NFU home insurance. Following a rejected claim based on a claim in Nov 24 for a partially collapsed front stone wall, the NFU then ‘cancelled’ our home insurance and wife’s car insurance policy, giving two weeks notice based on having had too many claims and stating that the wall hadn’t been maintained. The wall had suffered decades of poor upkeep, which was beyond our control.
After registering an immediate complaint with the FOS given the timescale, the NFU then changed their mind, quoting that is was now not offering invitation for renewal. The FOS supported the NFU’s change of decision, which we rejected in the final settlement, on grounds that they had not acted fairly, honestly and with integrity.
Now after reviewing some of the documentation from the NFU, a loss adjuster had revalued the overall reinstatement value of the property to a minimum of £872,362 back in Jun 24, prior to the wall claim. This was a significant increase from the previous valuation of £460,602. However, the mid-term alteration value that was sent to us was placed at £650,000. Thus grossly under insuring the property.
Would this then fall under misselling a policy, given that NFU had been given instruction by ourselves to amend it and amended it incorrectly? Or is there any other form of redress?
Moreover. NFU were aware of the poor condition of the wall, failed to include a specific exclusion under the policy and therefore under their own T&Cs would have been covered it despite them taking monthly premiums. How is this fair?
What would be a good course of action or am I just wasting my time, trying to take on the NFU?
Thanks
Comments
-
Did you instruct a change to the sum insured? Did you get a revised schedule at the time?
It's not misseliing - they just need to correct the cover.
They don't need to exclude the wall - there is a condition in most policies that the property insured is kept in good condition.
Continuing to take monthly premiums is of course fair as the policy covers more than just the wall.
0 -
there is a condition in most policies that the property insured is kept in good condition.
And even if there isn't, the policy only covers the specified insured risks e.g. impact, storms, earthquake - not just falling down because it's old and knackered.
0 -
NFU are normally fantastic at dealing with claims. They don't reject much at all.
Lack of maintenance is a very common reason for rejection and rarely needs an additional clause as the main policy terms will normally clearly state it.
Indeed, checking the general conditions of my NFU policy I can see the following:
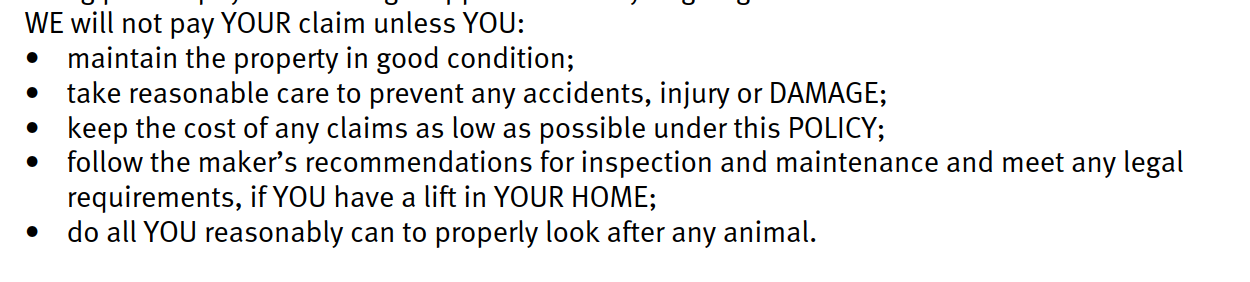 I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.0
-
Thank you for your replies.
XRS200 - The home insurance was advised by the assessor, who said the property was under insured. She quoted the upper level figure, £872,362, however what was quoted on the revised schedule was £650,000. So again, they were under insuring the property in full knowledge of what it should have been insured for! Why quote one figure then apply a different one? In essence, the corrected cover was never CORRECT!
As to the second issue, they knew the wall was in a poor state of repair, this SHOULD have been made an exclusion. They had full knowledge of this, yet failed to include it. In law, “If a structure cannot be covered by the policy at all, charging a premium for it is a breach of "fairness" and "value."USER1977 - The wall was in a poor condition, however after a month’s deluge of rain(3rd highest on record in Bedfordshire) the wall partially collapsed. So in fact it was storm damage that ultimately brought about the partial collapse. So despite it being covered by the terms, it breached their terms and conditions due to its poor condition. THe point again is, this should have been excluded, as they had knowledge of this. We paid a certain part of the premium on a wall that would NEVER been covered!
DUNSTONH - I beg to differ! We have been customers with NFU for over 22 years. Early claims were settled by obtaining own quotes and recieving a cheque to cover the claim. Since 2021, Nick Turner became CEO, a Texan, who has reshaped the business and direction, now 3rd party loss assessors turn up(the chap that assessed our wall called himself a surveyor, however wasn’t RICS registered. Had ran his own building company that went bankrupt, were he worked as a ‘tea boy’ for 18 months(quoted from his own Linkdin profile)), who are there for the NFU benefit not the customer. The reputation is on the decline.
“The backlash and complaints surrounding NFU Mutual primarily stems from disputes over underinsurance, low financial settlement offers on major claims and slow claims management involving their own network of loss adjusters and contractors.” FINANCIAL OMBUDSMAN
Interesting, the FOS highlighted exactly what we have experienced!0






Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.6K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards