We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
IHT Planning
Comments
-
Taper relief only applies if you've given away more than the NRB in the 7 years before your death.
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!2 -
Taper relief does not apply to most gifts. It only applies where the NRB is already used up, so tends to only apply to people who make very large gifts.
If you read the bit on the gov.uk website above the part you have copied, you will see the info.
2 -
fair enough.
Donate it all to charity then. No IHT to worry about. I’m sure your kids and grandkids will be thrilled with your decision.0 -
Donate it all to charity then. No IHT to worry about. I’m sure your kids and grandkids will be thrilled with your decision.
An alternative is to leave a certain amount to charity in your will ( minimum 10% of your net estate - which means in this case the estate after any NRBs are applied) then any IHT tax is reduced to 36% from 40%. Plus of course the actual amount you leave to charity is not counted for IHT.
1 -
There's also residence based NRB, but people who are single with no kids or who just want to stiff their spouse or direct descendants don't get that. So they are left with the base allowance of 325k. That seems very low to me, especially was it hasn't increased in recent years and also now that DC pensions will fall within IHT.
And so we beat on, boats against the current, borne back ceaselessly into the past.1 -
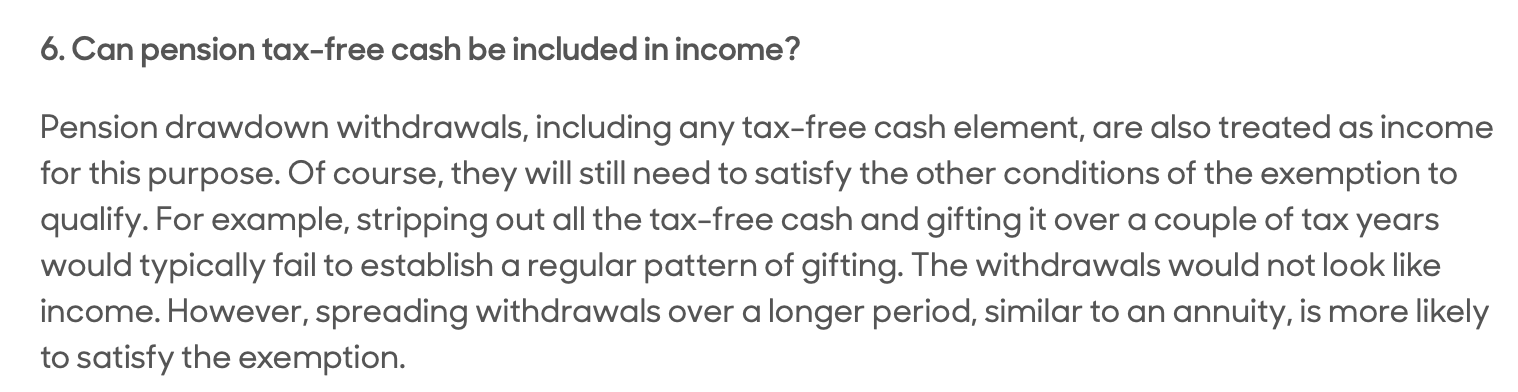
I don't think this would work, but what if you had a DB pension and a DC pension. Could you gift the entire DB pension as excess income and then live of income AND capital withdrawals from the DC pension?
And so we beat on, boats against the current, borne back ceaselessly into the past.0 -
Less likely to provoke controversy, you could annuitise your DC then gift excess income.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Ecoflow Stream, Best kettle :-)
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.0 -
The rules seem a bit fluid, and effectively it is up to your estate executor to convince HMRC that it was genuine Gifts from Income, and to have the paperwork to prove it.
Plus of course it is a bit of a loophole, so might suddenly get stopped one day.
0 -
By defintion, if you are living off capital then you do not have excess income.
1 -
See
and note particularly:
 Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!0











Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards