We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
TUPE and losing health insurance



My workplace is currently going through a TUPE transfer, and I’m due to move to a new employer on 31st March 2026. As part of that, there have been some changes to employee benefits, including removal of many optional ones.
I’m after a bit of advice on where I stand with something I’m dealing with just now. I injured my hip in October 2025 and started diagnosis/treatment in November 2025 through my employer’s salary sacrifice health insurance (via Equipsme, underwritten by AXA). It was only communicated on 30th January 2026 that this benefit would be ending as part of that transfer. By that point I was already in treatment, and I’m now mid-treatment awaiting surgery.
For context, it’s a labral tear with some associated tendon damage and inflammation all linked to a boney ridge on the cam of the hip joint. Its a sport injury, with the underlying cause being general wear and tear. After the initial injury, the plan was to try the conservative treatment route first. However, we’re now four months into that and it’s pretty clear it isn't working, so surgery is needed to fix the underlying issue with my hip cam. In terms of impact, it’s not stopping me working, but it is affecting day-to-day life and severely limiting ability to excercise - I have limited function in my hip flexor that just isn't getting better, even with steroid injections and physio.
To continue cover for this existing condition, the quotes recieved see cost jumps from roughly £60 per month under the salary sacrifice to over £500 per month privately. I’ve raised it with the union, but I’m trying to get a feel for whether anyone else has been in a similar position and how it played out.
I appreciate they may be legally covered here, but it feels like a very unfair position to be left in when I had already started treatment before any indication was given that the benefit was withdrawn.
As I see it, I have three options: pay the enhanced premiums for 6 to 9 months, pay out-of-pocket for treatment - both of which costing me thousands and are not realistic, or go back to the NHS - which likely sees about a 2 year wait.
Has anyone had experience of similar during TUPE, and where did you tend to stand with it in the end? I have raised it with my union, but its not going anywhere fast.
Comments
-
A lot depends on how your entitlement to health cover is worded in your contract, and the reason why the new employer believes they can stop that cover. Is your contract for a required benefit ("employer will provide health cover") or discretionary ("employer may provide health cover").
If the contract says the employer "may" provide benefits or reserves the right to change them, the new employer inherits that discretion. However, they cannot simply use this to withdraw benefits immediately without good reason, as it could breach the implied duty of trust and confidence
The legal position is fairly clear, but there will always be exceptions:
"Under TUPE, the new employer takes over employees’ employment contracts, including:
- all the previous terms and conditions of employment
It’s a breach of contract if these are not maintained"
There's some detailed explanations here:
https://www.howdengroup.com/uk-en/news-insights/effect-tupe-certain-insured-employee-benefits-0
"The transferee employer will usually need to continue to provide any contractual rights to benefits from an insurance scheme, such as private healthcare, life assurance and income protection."
If there isnt a valid reason to cease cover, or if your current treatment is regarded as a single ongoing claim, based on the below it seems like you have a reasonable case:
"For private medical insurance, it is important that there is continuity of cover, as at any moment in time a significant proportion of the eligible workforce are likely to be undergoing treatment. Claims for treatment prior to date of transfer would continue to be authorised and paid by the transferor employer’s insurer. All claims for treatment which take place on or after date of transfer should be submitted to the provider of the transferee employer’s private healthcare policy."
Try Acas if you haven't already:
https://www.acas.org.uk/contact
1 -
This is where I’m unsure how it stands. Legally, I’m not sure I’ve got a leg to stand on either, excuse the pun.
My argument is probably more on fairness than anything else, because it does feel a very unfair position to be left in — one that leaves me in limbo and is likely to lead either to a large personal expense or a worse overall health outcome. I paid into the scheme, so it feels reasonable to expect to be able to use it. I have no control over being withdrawn from it — I don’t want to be, but through no fault of my own, I am ..... and being withdrawn halfway through treatment feels very unfair.
It was an entirely optional salary sacrifice benefit, although most people opted into it because it was a very good deal, particularly as they got older. Contractually, it is an entirely optional 'perk'
I work for EDF, and the site is moving into decommissioning and transferring to NRS, which is an arm’s-length government organisation. I understand why private health insurance isn’t something they would normally offer, particularly given the public ownership element. However, this was not communicated until after I had already started treatment.
For context, It also wasn’t entirely clear at the time, as — unlike older nuclear power stations — the site is funded through a private decommissioning pot with no direct public funding (we will be the first to follow that model), even though the overseeing organisation is publicly owned. As a result, we didn’t really know what the final position would be until 30th January.
0 -
Have you spoken to your current insurer to see if they will continue to support it as an ongoing claim? If so, your current would still be liable. You should also speak to edf to see if they would be willing to continue to support the claim (in the case they weren't legally obliged to).
1 -
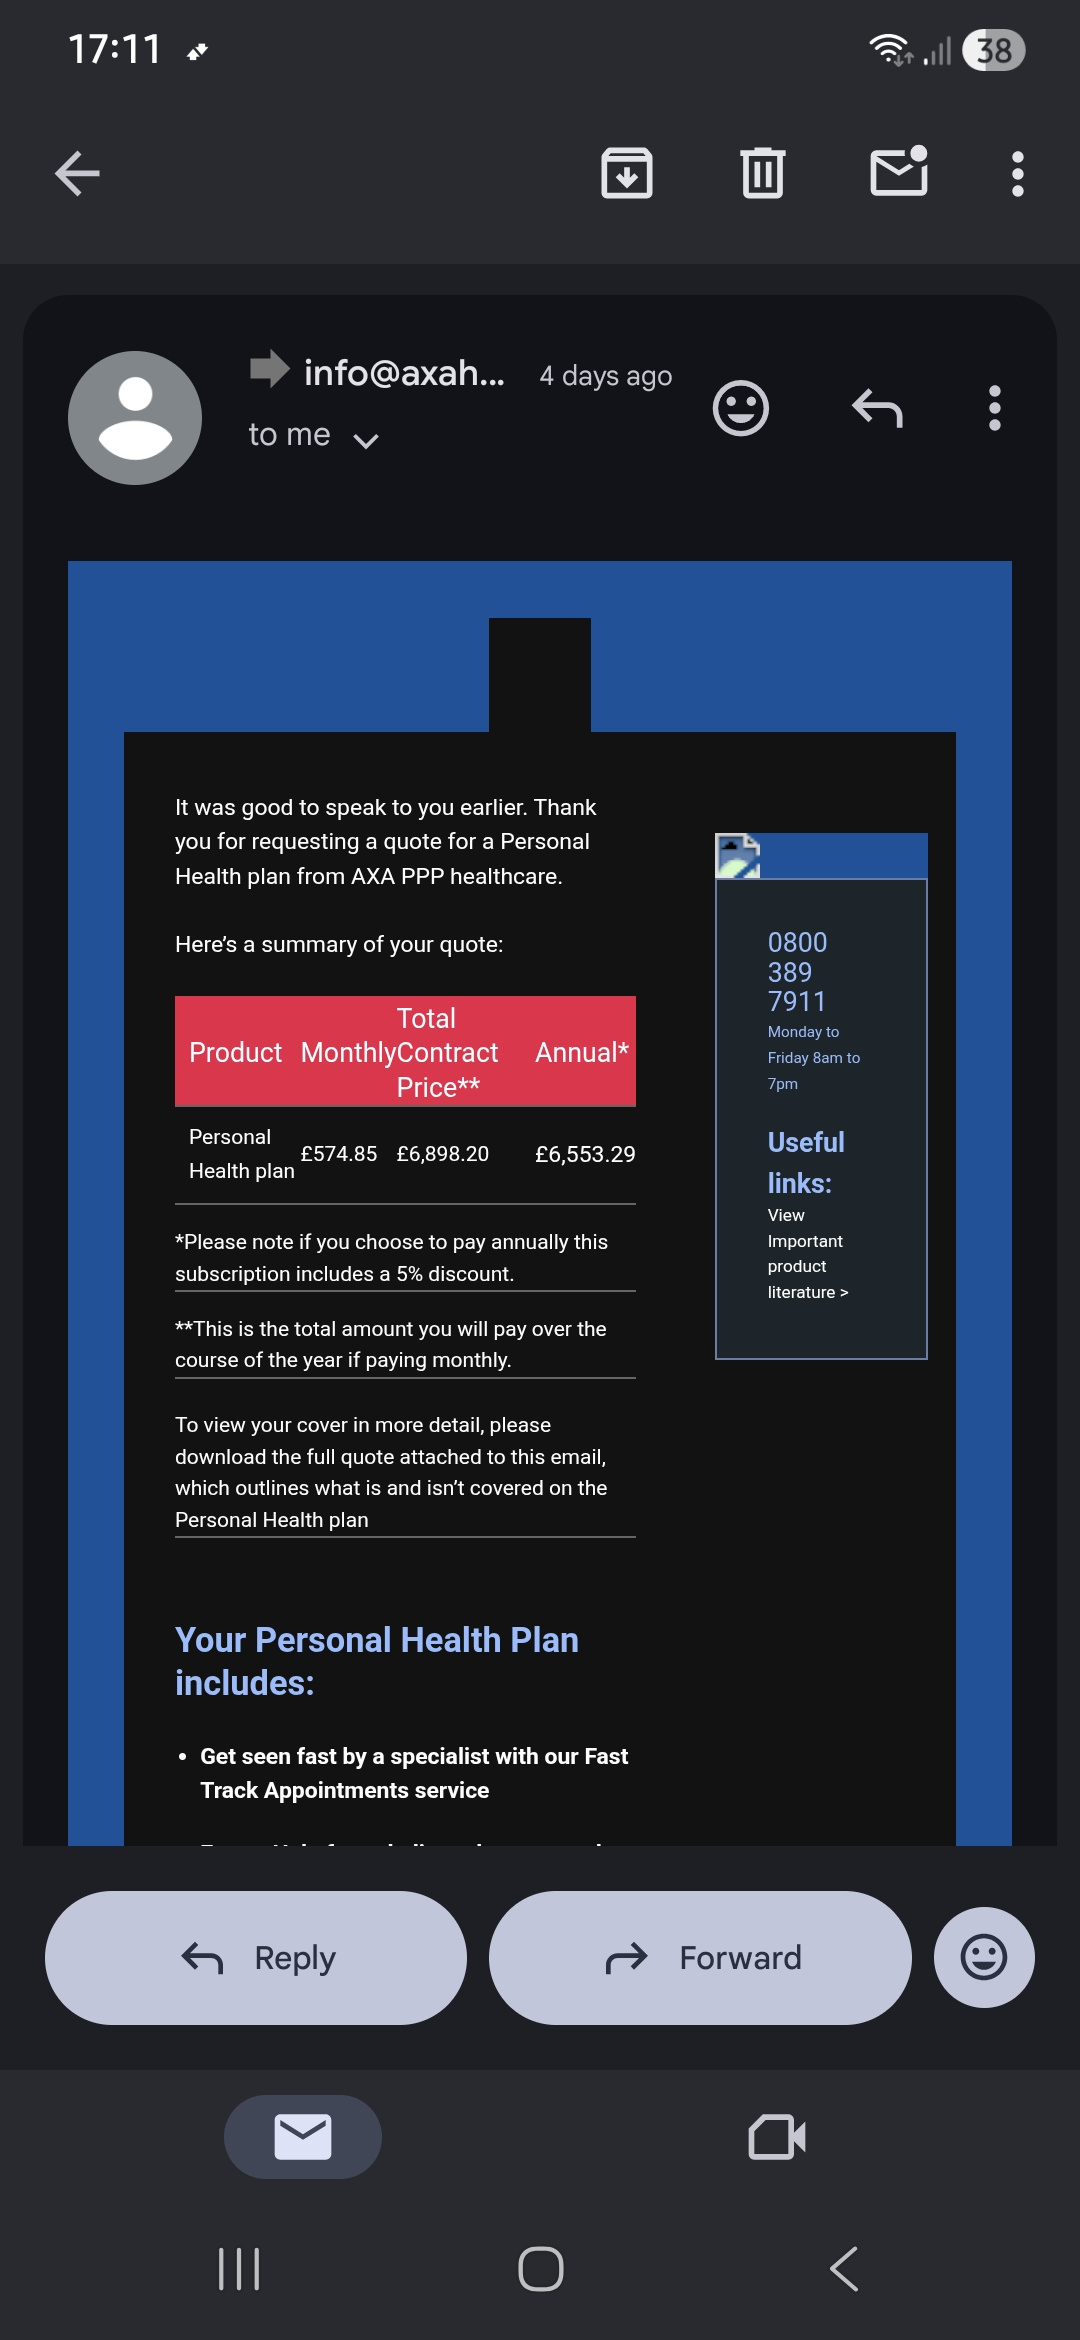
Yes, Equipsme do not offer personal insurance, I have contacted Axa as underwriter, but carry on with an existing condition is leading to the £570pcm to have a like for like policy. The quote is in the ball park with every other insurer. I can cut that to £390pcm stripping everything out.
By comparision, have like for like but excluding existing conditions is £83pcm.
I am in communication with my union about it, who are chatting to parties on my behalf, but no idea what outcome to expect - its been 8wks.
0 -
I had a similar situation but I was made redundant. I was able to continue cover at a much reduced rate for 12 months which covered the time period I needed. That unfortunately doesn't seem to be the case for the OP, although 'the much reduced rate' was £100 per month in 2005! After that time it increased to over £300 per month. I hate to think what that equates to now.
0 -
-
i realise that you have replied to @Woodstok2000 above, but I’m going to make a very similar observation, and I wonder if it comes down to what you mean by having started treatment.
I had a colleague who was made redundant 5 years ago who was mid treatment with a series of back treatments. He called up our insurer and they confirmed he was covered through to the end of treatment even though that was past redundancy.
I suppose if your low impact course of treatment is “the treatment” and the surgery is not directly linked that would be a break point in insurance cover, but did you ask / argue for them to be a continuous treatment?
finally have you asked how much the hip surgery might be as a standalone treatment? It might be worth it to you to self-fund that part alone while keeping the cheaper ongoing cover for everything else.
0 -
Is that carrying on the healthcare with an existing condition, or the price to complete the treatment thats already under a claim?
Maybe you've already done this, but you need to be very clear with them about whether youre looking for ongoing healthcare cover for all conditions into the future, or if you just want them to continue to cover the cost of treatment for the existing hip injury.
0 -
Well the operation would be about £3k and would be 6mths of rehab following. Would be fair to say I wouldn't get much change out of £5k
0 -
I TUPE’d into the Civil service and as part of the negotiations they had to agree to continue my BUPA cover. They asked me to get a quote and set it up myself and they paid me the full amount every month uplifted to account for tax and NI.
0









Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.6K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards