We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Getting ready to do the Lowell dance on a 5 year old default, what should I prepare for?



Hello all!
Long time reader, first time poster.
I defaulted on a PayPal credit account in July 2021, for £1600 (ish). Life took a turn for the absolute worst, and I didn't have the bandwith to advocate for myself, so I made the poor choice of just sticking my head in the sand. The account defaulted, all letters from PayPal stopped (apart from a random £5 refund a few years ago because my account was one of many identified to have been poorly handled by customer service 🤔)
In Feb, the account status changed to settled, with around a year left on the clock before it becomes statute-barred. I called PayPal to close my account, and they refused as I'd been banned permanently with a balance still there. I noticed my address was wrong, and they refused to change that too. They kept telling me to call Lowell - I'd really rather not at this early stage.
I've moved home a couple of times since, but I'm easy to trace. There hasn't been any communication from the time it defaulted to now, and I've kept a keen eye on my credit file(s), there have been no CCJs without my knowing.
There's a couple of things I wanted to know first, ahead of them starting the campaign against me. I've done a lot of reading on what type of company this Lowell is, so I'm apprehensive to say the least!
- Am I better off not engaging unless they contact me? I figured the harassment would have started in earnest by now, with a year remaining.
- If they do contact me, what’s the safest way to respond without accidentally acknowledging the debt?
- Is there a risk they could go straight for a CCJ applied to my old address?
- I can hold out until they start threatening legal action, as I don't mind paying a percentage to settle it.
- How should I play this?
- Thanks everyone 🙂
Comments
-
- Am I better off not engaging unless they contact me? I figured the harassment would have started in earnest by now, with a year remaining.
Yes ,but you may then get a CCJ if the letters go to your old address. It is common for a debt collector to wait until the last year in the hope that your finances will have improved by then and knowing you will not want your credit ruined for another 6 years with a CCJ
- If they do contact me, what’s the safest way to respond without accidentally acknowledging the debt?
You can put the word "alleged" before "debt" in everything you write,
- Is there a risk they could go straight for a CCJ applied to my old address?
Yes
- I can hold out until they start threatening legal action, as I don't mind paying a percentage to settle it.
One plan would be to ask them to produce the CCA agreement for the debt, and if they can, offer a settlement amount.
1 -
Thank you so much for replying. Slimy business practice if you ask me!
I've read up on CCJs and have seen they can be set aside if the creditor didn't make a genuine attempt to locate the debtor? I realise this comes at a cost too, though.
I'm a little stuck between engaging and giving correct address information to avoid any CCJ risk but I worry that may ping that I'm contactable and active on the system.
They haven't phoned or emailed yet, I could wait for either of those then ask for the CCA agreement first?
0 -
I've read up on CCJs and have seen they can be set aside if the creditor didn't make a genuine attempt to locate the debtor?
Business Debtline gives a good explanation here
https://businessdebtline.org/guides/setting-aside-a-ccj-ew/#when_might_the_court_agree
Unless you have a defence to the claim, there may be little point in a set aside, as the case will just restart with the correct address.
2 -
I would ignore anything from Lowell, why respond at this late stage?
If they are going to get legal with you, they will first pass the account to Overdales, who are their "inhouse" solicitors, there should be plenty of warning of impending legal action, so if it gets to that stage, and your not yet over the line, well its up to you what you do next.
Its been said many times on here, companies such as Lowell operate on an numbers basis, the same applies to their enforcement of CCJ`s, the vast majority that are granted just sit on your credit report for 6 years with no further enforcement action.
Only if they think you can pay, but won`t will they try for an attachment of earnings, or possibly a charging order if you own property, they have 100`s of 1000`s of accounts that they buy, they have to be selective on what they pursue, and they don`t.
I’m a Forum Ambassador and I support the Forum Team on the Debt free wannabe, Credit file and ratings, and Bankruptcy and living with it boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com. All views are my own and not the official line of MoneySavingExpert.For free non-judgemental debt advice, contact either Stepchange, National Debtline, or CitizensAdviceBureaux.Link to SOA Calculator- https://www.stoozing.com/soa.php The "provit letter" is here-https://forums.moneysavingexpert.com/discussion/2607247/letter-when-you-know-nothing-about-about-the-debt-aka-prove-it-letter1 -
Thank you both so much for your replies. I definitely don't want to go down the route of a CCJ as I want to start considering a mortgage, but it's clear I've got plenty of time.
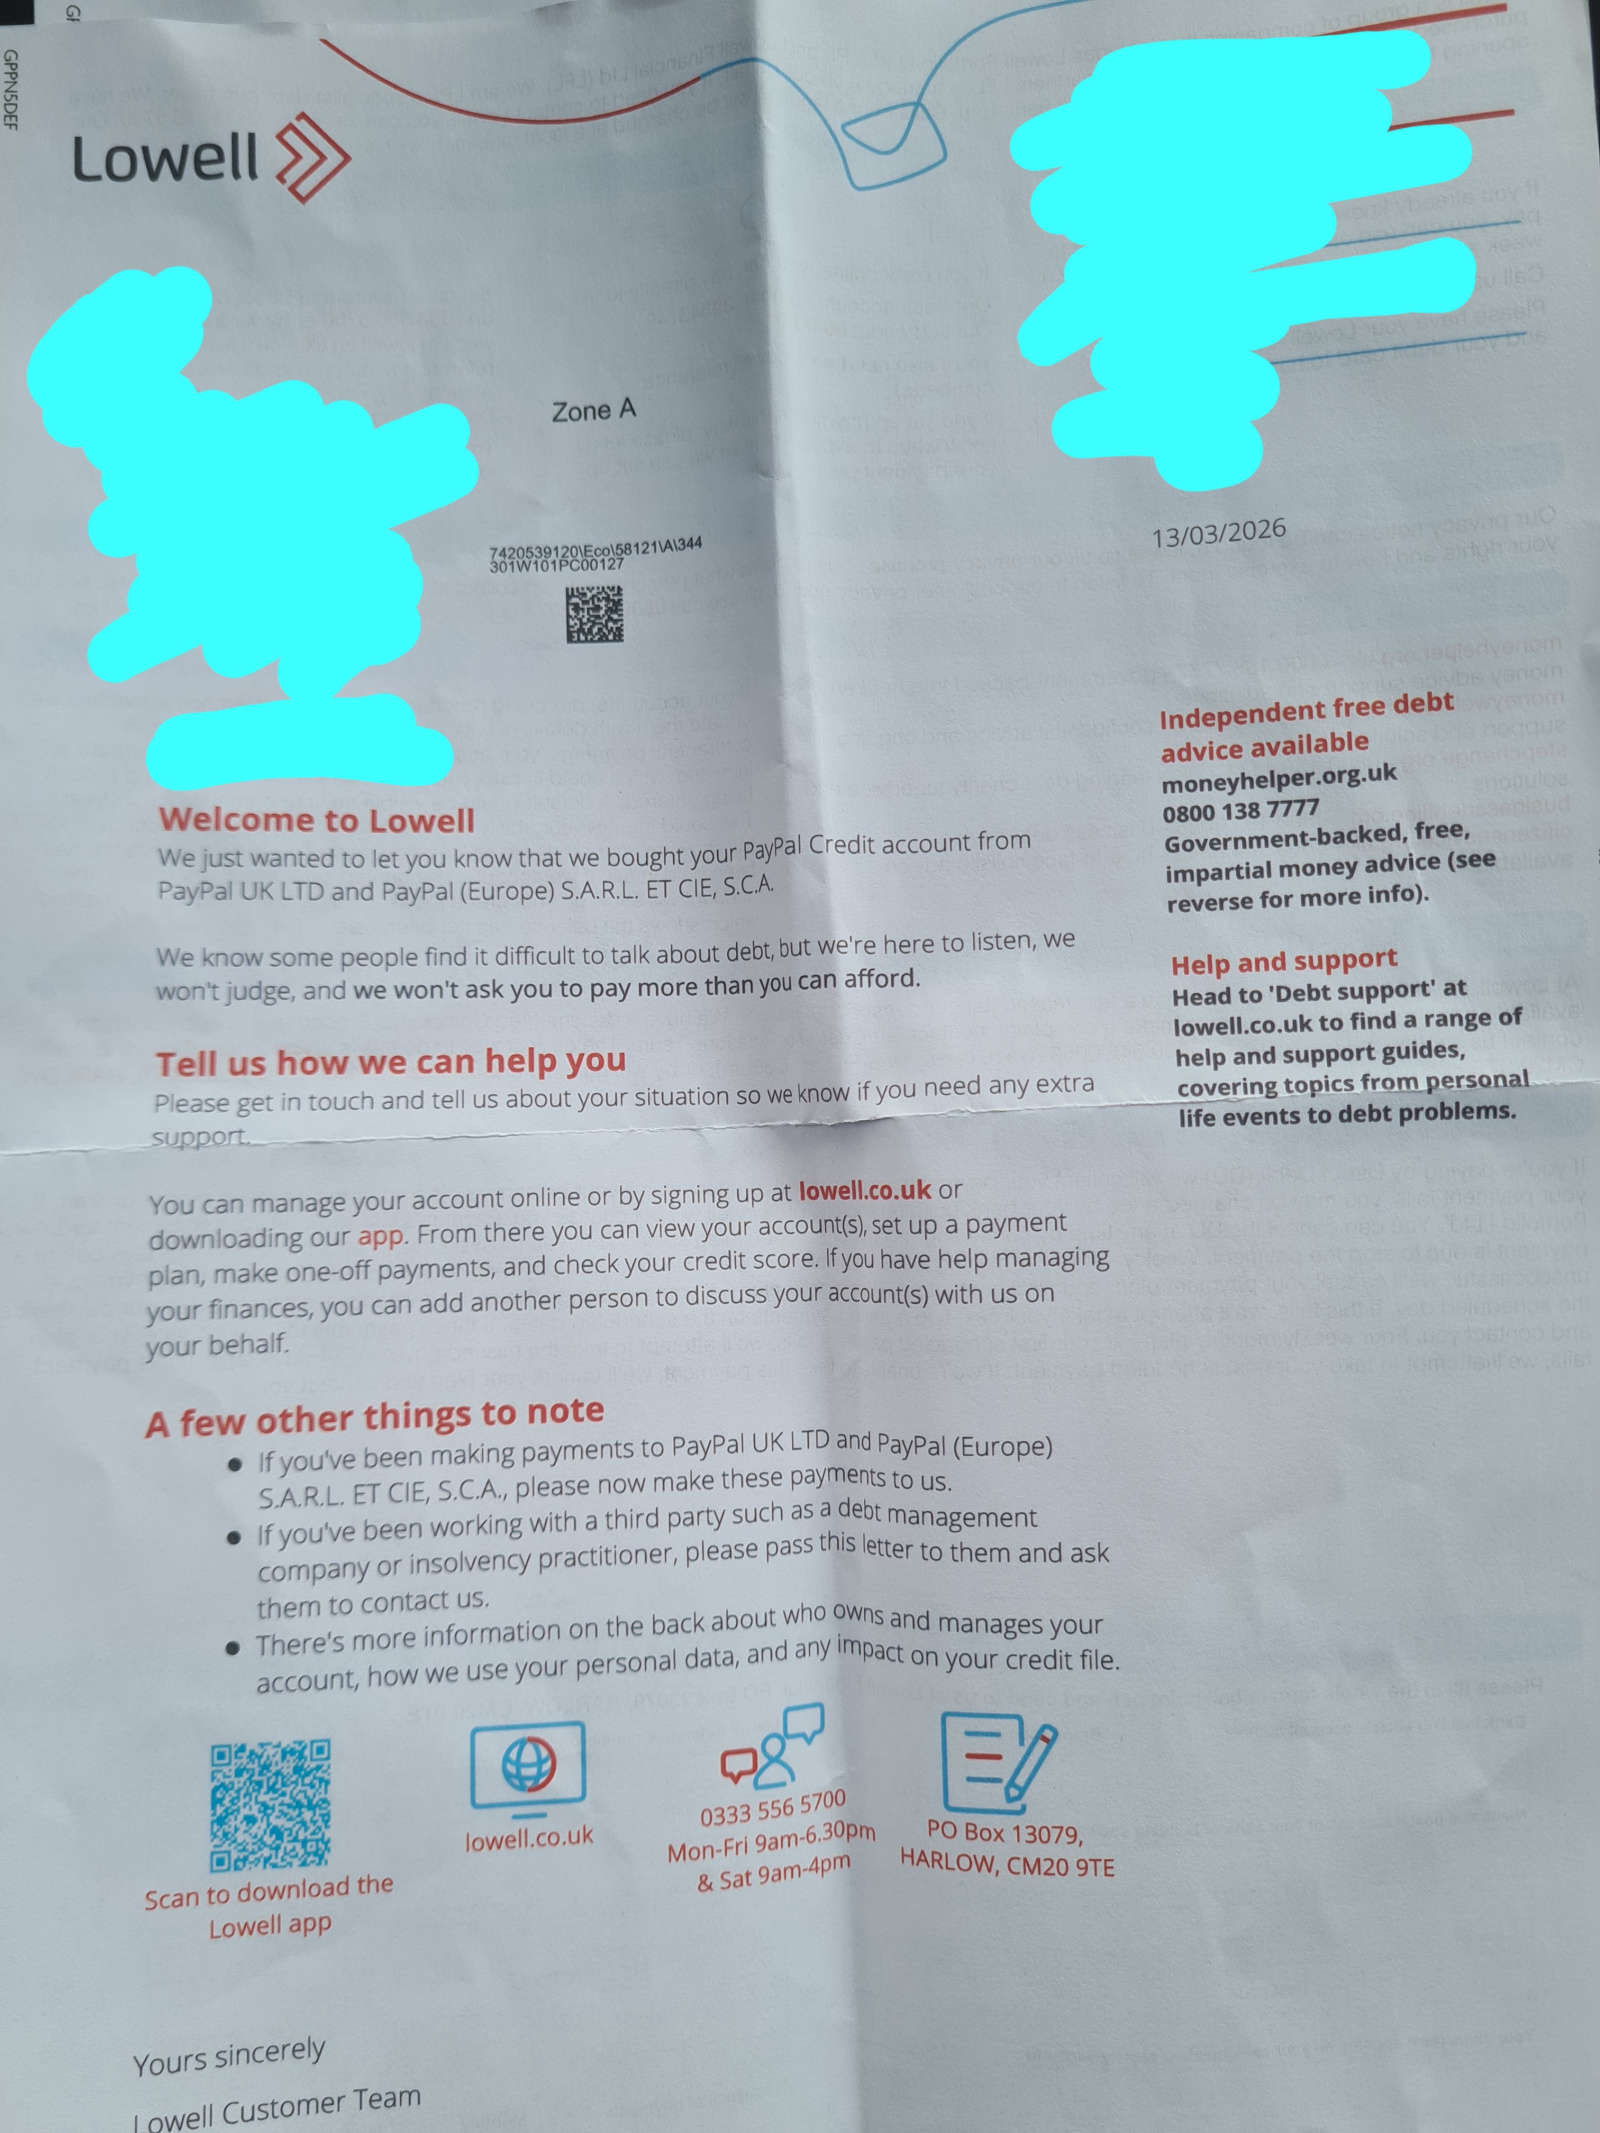
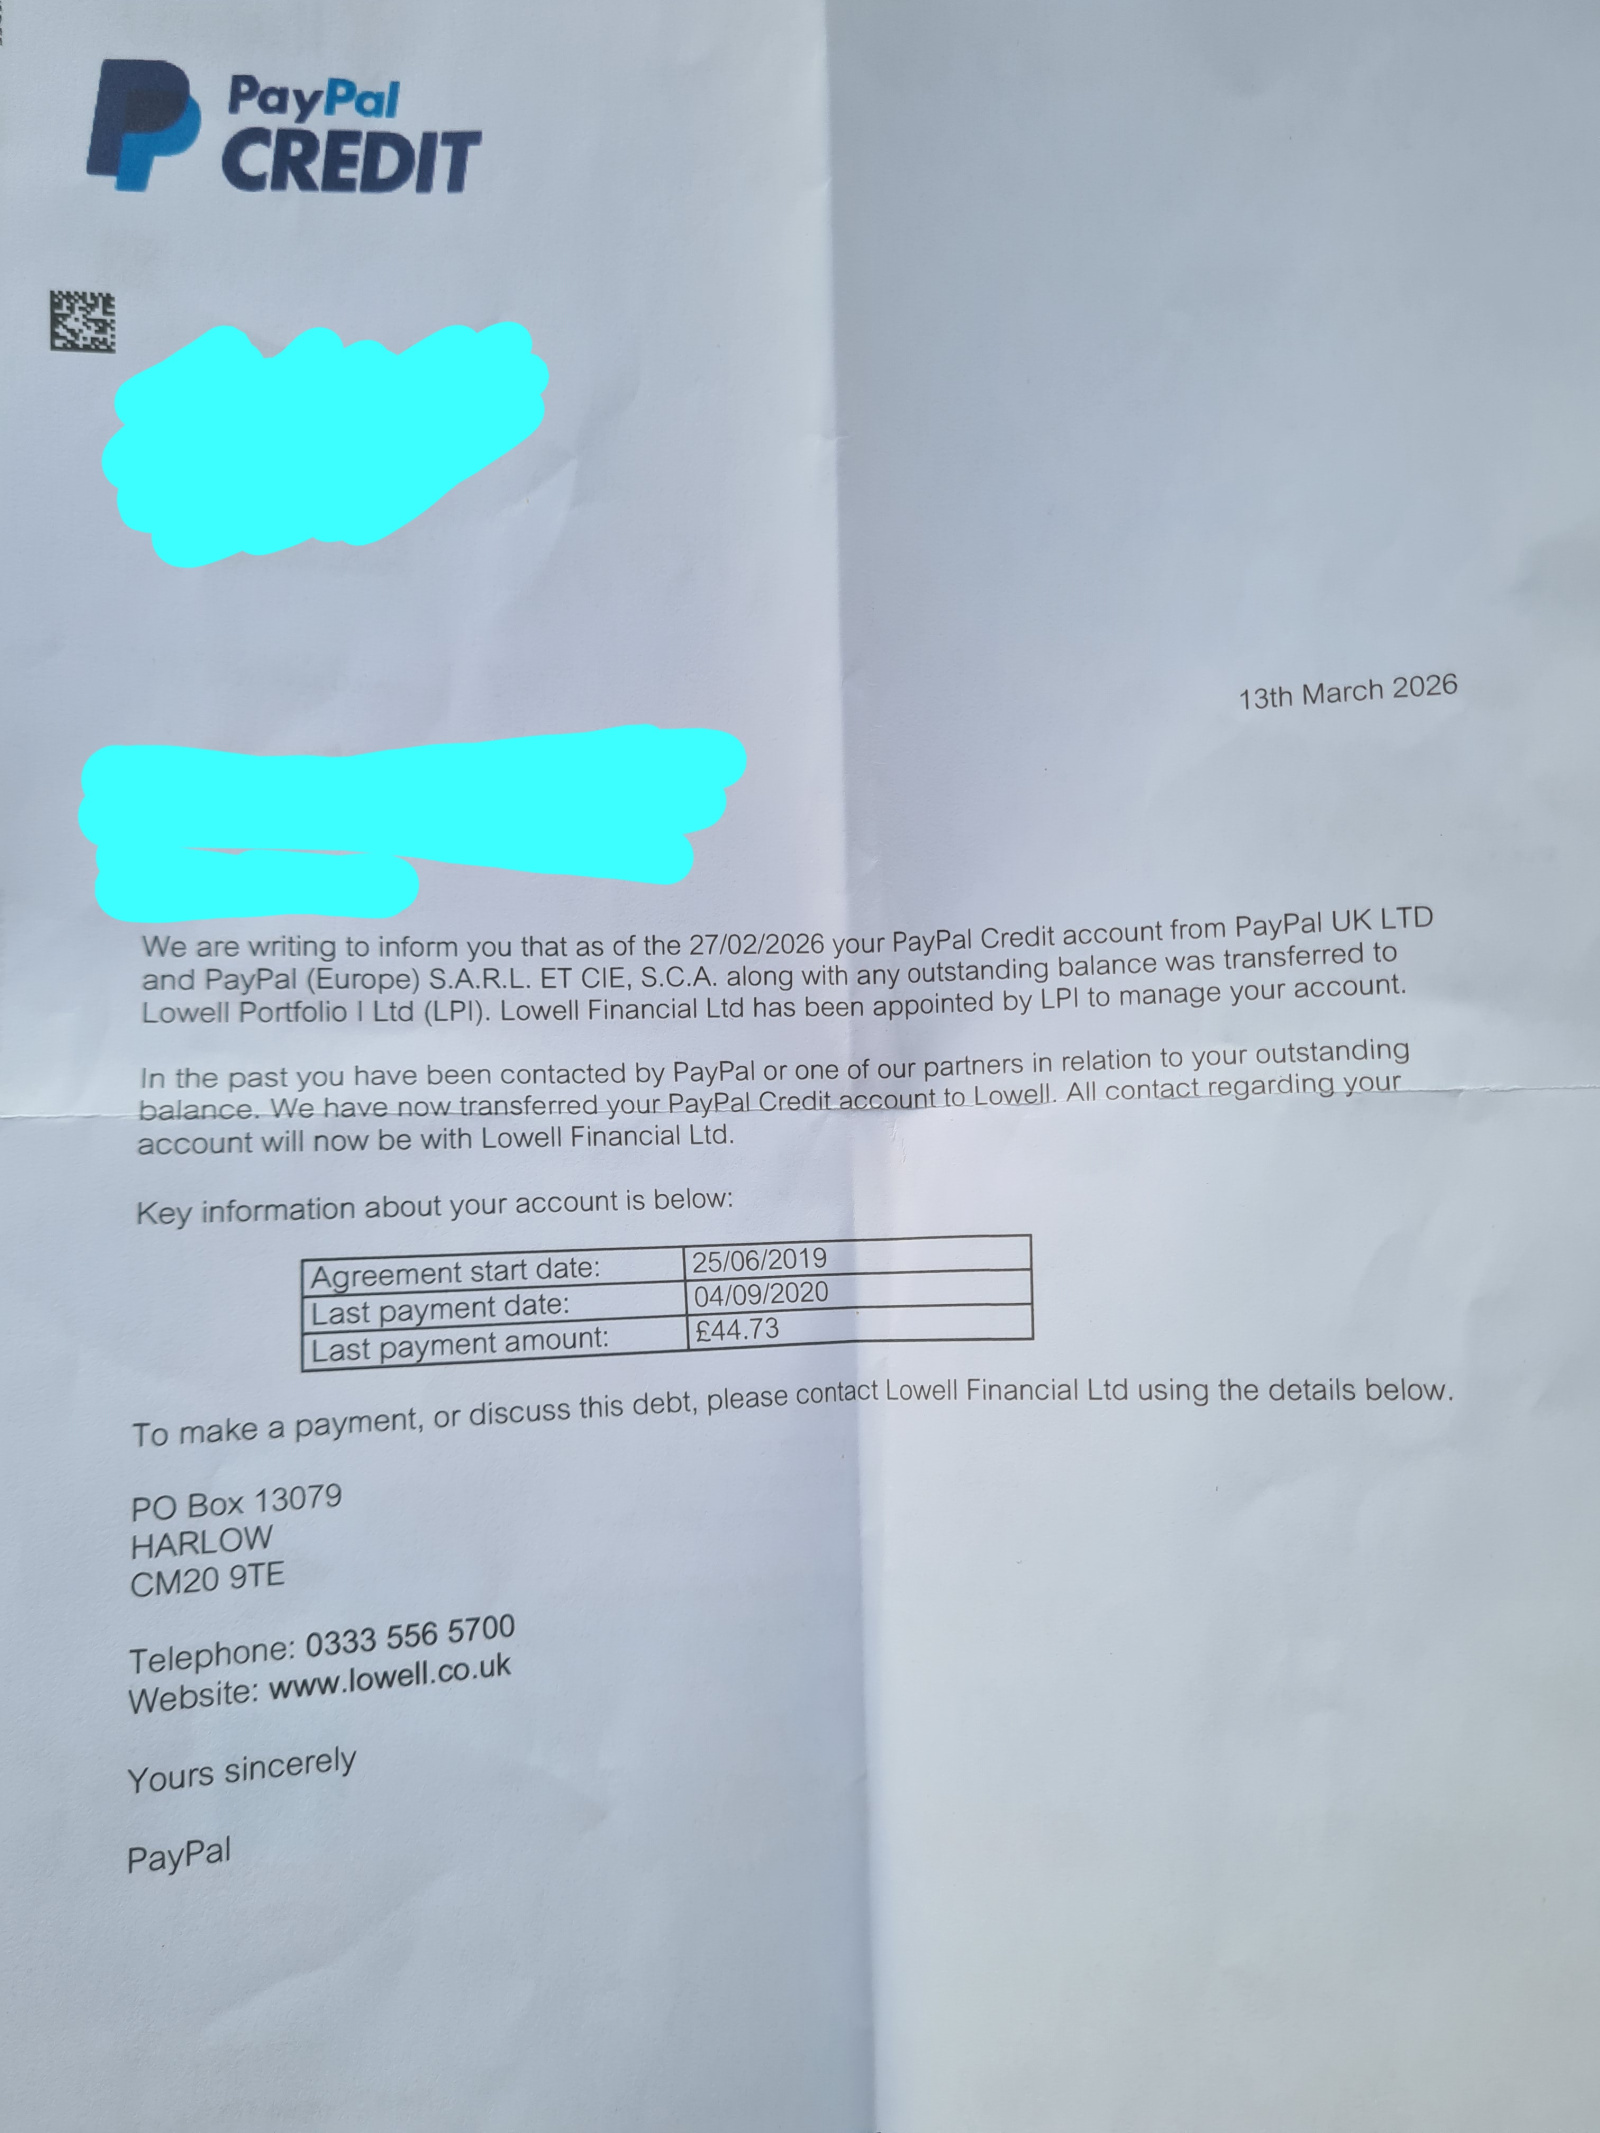
I've just had these in the post today, does the PayPal headed one suffice as proof? Or can I still request a CCA?
Also the last payment date is way earlier than I thought, am I right in saying that the last payment doesn't matter in terms of statute barred debts, rather it's the default date?
Thank you again both :)
0 -
You can think of it like a 6 year timer that starts counting down when the debt defaults. Any payment after the default will reset the timer back to 6 years and the debt only becomes statute barred once the 6 years has elapsed.
1 -
Those are just letters informing you your debts have been assigned or sold to Lowell.
Section 77/79 of the CCA , is an entirely different piece of legislation altogether, and one has no bearing on the other whatsoever.
You can make a request under the above sections of the act whenever you wish, the only stipulation, is that a balance must still exist on the account, thats it.
I’m a Forum Ambassador and I support the Forum Team on the Debt free wannabe, Credit file and ratings, and Bankruptcy and living with it boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com. All views are my own and not the official line of MoneySavingExpert.For free non-judgemental debt advice, contact either Stepchange, National Debtline, or CitizensAdviceBureaux.Link to SOA Calculator- https://www.stoozing.com/soa.php The "provit letter" is here-https://forums.moneysavingexpert.com/discussion/2607247/letter-when-you-know-nothing-about-about-the-debt-aka-prove-it-letter1 -
Forgive my confusion, are when the payment defaulted and when PayPal initially registered the default officially on my credit file different dates?
0 -
The date of default is now regarded as the "cause of action" date, confirmed by appeal court ruling a few years ago.
It used to be the date of your last payment to the debt, but that has now changed.
However it does depend on individual circumstances, as one or the other of the above, could apply.
I’m a Forum Ambassador and I support the Forum Team on the Debt free wannabe, Credit file and ratings, and Bankruptcy and living with it boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com. All views are my own and not the official line of MoneySavingExpert.For free non-judgemental debt advice, contact either Stepchange, National Debtline, or CitizensAdviceBureaux.Link to SOA Calculator- https://www.stoozing.com/soa.php The "provit letter" is here-https://forums.moneysavingexpert.com/discussion/2607247/letter-when-you-know-nothing-about-about-the-debt-aka-prove-it-letter2 -
Shoot, the cause of action date is unknown to me here. I could go by the default date to be safe, which means I've got quite ways to go until statute barred.
Forgive me (again) for getting my dates wrong, I was too hasty to get posting! This is what they should be:
- Last payment: 04/09/2020
- Default date (credit file): 16/07/2021
- Debt purchased: Jan 2026
So it could be either of those, or somewhere in between?
0







Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards