We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
PLEASE READ BEFORE POSTING: Hello Forumites! In order to help keep the Forum a useful, safe and friendly place for our users, discussions around non-MoneySaving matters are not permitted per the Forum rules. While we understand that mentioning house prices may sometimes be relevant to a user's specific MoneySaving situation, we ask that you please avoid veering into broad, general debates about the market, the economy and politics, as these can unfortunately lead to abusive or hateful behaviour. Threads that are found to have derailed into wider discussions may be removed. Users who repeatedly disregard this may have their Forum account banned. Please also avoid posting personally identifiable information, including links to your own online property listing which may reveal your address. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Renting a UK property while overseas or just sell
Comments
-
splinters said:One last question before we start the process of selling the house. Are there any practical options to keep the house at minimal cost to us while overseas? We like the flexibility of still having a property (visits home, fallback in case the jobs don't work out here etc.) but no one wants to be paying council tax, utilities etc.Empty properties
You’ll usually have to pay Council Tax on an empty home, but your council can decide to give you a discount - the amount is up to them. Contact your council to ask about a discount.
If your home has been empty for at least one year
You can be charged additional Council Tax if your home has been empty for at least one year. This is also known as the empty home premium.Utilities - you need a tariff with the smallest standing charge.And insuring an empty house can be problematic.
2 -
Thanks @grumpy_codger. My sensible head says sell it and move on, we paid 37k for it back in the 90's and its worth at least 5 times that now with the mortgage paid off a decade ago. It was a family home but they have all flown the nest.
My cautious side says it's wise to keep a house you own outright. The option to let my family live there was the best of both worlds but sadly doesn't look like a viable option for either party.0 -
Thanks, we neither like the build quality of their new house where they live or the area (a key reason they want to move on) despite the fact it's a lovely house inside cosmetically and in terms of size, facilities etc.mlz1413 said:I agree with selling your house, if your don't want to come back to it.
You could let your daughter live there for free if she pays the bills and looks after it, but Poseidon1 does set out a good argument not to and I definitely agree with that post.
You could make a contract with your daughter that she has to save her current mortgage value and has to have bought somewhere within the 5 years ... but again what would the reality be if she dipped into the savings for a car, holiday, etc.
If you do want to own somewhere, could you agree to buy the daughters house? Same deal as living in yours but you will own it and be coming back to it in 5 years. That way daughter needs to be out but it gives you a breathing space to buy the perfect retirement home. Difference with this is you and daughter won't keep this house and it only betters her life by financial easing their current situation.
Lastly I would not rent either house out. Being a reluctant landlord in the current changing landscape would be stressful and there is no guarantee tenants will leave (in today's rules let alone what is to come).
Enjoy the wedding and Zurich, it sounds like quite an adventure!
We have given them one more option. Sell their property, live in ours covering just the costs (no rent) and save at least their existing mortgage which is about to jump to around £800+ a month. That gives them the chance to live in a furnished house, save around £60k+ over 5 years and they maintain the property. Their property is also worth a little more than they paid 3 years ago so no negative equity.
Win, win? Only catch is they are getting married (I meant husband to be) and the idea of moving into your parents home after getting married is hardly romantic (we have a smaller home, but an older build in a better area).
Zurich is very snowy today, but clear, clean and healthy air here.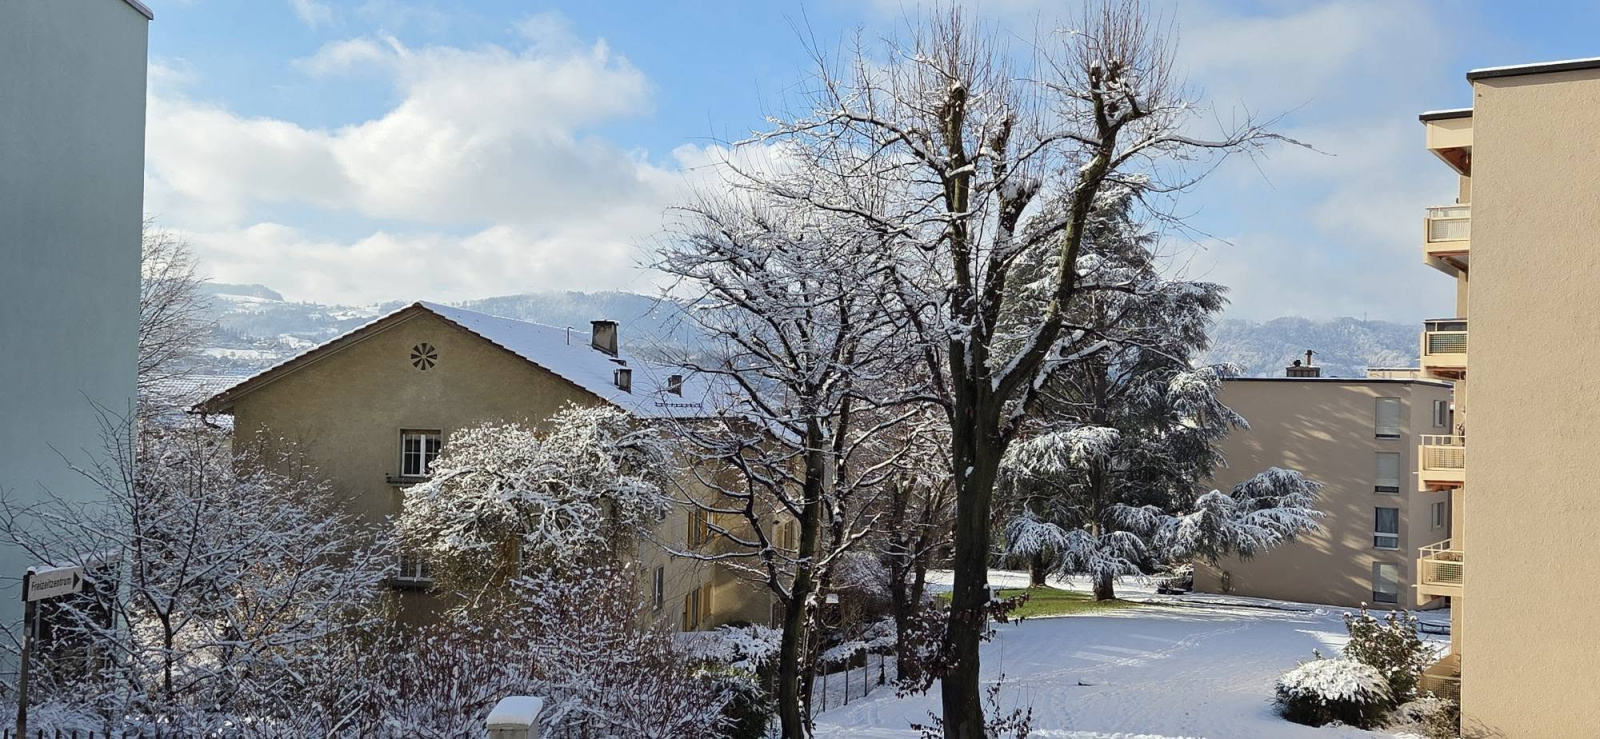
4 -
Remember you could be liable to Capital Gains Tax , when you sell, for the period it was not your main home .splinters said:One last question before we start the process of selling the house. Are there any practical options to keep the house at minimal cost to us while overseas? We like the flexibility of still having a property (visits home, fallback in case the jobs don't work out here etc.) but no one wants to be paying council tax, utilities etc. and we would need to have the property checked for leaks, damage etc. but our children live quite near to us.
I think I know the answer but, having never sold a property before, I thought it worth asking for some advice.
I guess that this will just be dead money (and unwanted costs) for the 'convenience' of a place to stay when we come home. Likely to reduce its value too if its left too long and isn't there a big tax hit if you sell a vacant property while overseas? We also really need to stop sentimentality creeping in :-)2 -
On the numbers you quote your property is currently in the £185k - £200k range?splinters said:Thanks @grumpy_codger. My sensible head says sell it and move on, we paid 37k for it back in the 90's and its worth at least 5 times that now with the mortgage paid off a decade ago. It was a family home but they have all flown the nest.
My cautious side says it's wise to keep a house you own outright. The option to let my family live there was the best of both worlds but sadly doesn't look like a viable option for either party.
For those of us that live in London and and it's environs that is a modest number for a mature family home.
On the income trajectory for your daughter and her husband over the next 5 years, is it really beyond their capabilities to buy your home for say £200k once you return?
I would certainly agree that had we been talking about London prices in the situation you outlined, keeping the house for daughter to occupy rent free did look problematic, but at such a much lower potential sale price is there no way your idea can be made to work based on your daughter eventually being able to buy it? Of course your daughter and her husband to be, would need to be attracted to this idea in the first place.
In passing, should you decide to sell think carefully what you will do with the proceeds.
As a Swiss resident you are aware you are taxable on your worldwide income sources. However, Switzerland does not tax capital gains on disposal of personalty ( eg stocks and shares). Therefore, although ISA and GIA interest and share dividends are declarable and taxable in Switzerland, gains on disposals of shares etc are not. In short, a growth orientated GIA/ISA portfolio could be a taxed advantaged option for property sale proceeds, compared to simply holding funds on bank interest bearing deposits.
4 -
We live in Yorkshire where house prices are much more reasonable. They wouldn't want our home just as we won't and their own property is about the same value circa £200k. They want a better home in a nicer area just as we do. The reason for working in Zurich is to afford a better home on our return and possibly retire early with the remainder of the savings, pensions etc My teacher pension starts in 4 years. Letting them live there while saving their mortgage payments would give them a financial boost.1
-
A no brainer, just sell it, it is really not worth the effort of being a single property landlord. (IMHO).."It's everybody's fault but mine...."1
-
Unless the kids take my plan C offer, we are now looking into a sale and, as my wife it still living in it, there shouldn't be much vacant time before sale. Properties in the area tend to get snapped up quick.Stubod said:A no brainer, just sell it, it is really not worth the effort of being a single property landlord. (IMHO)0 -
OP, just a slightly different view. My son is in the armed forces and owns a home in the UK. He hasn't lived in it for a good 10 years as he has been deployed around the country and overseas. However, he sees the house as his nest egg and is currently making a modest profit all in, but profit nonetheless. He is in a slightly advantageous position in that he won't have any CGT liability on it, but even so, he always has the option of moving back in should he ever need to. The house is managed by an agency but he oversees any major repairs etc. The upside being the house is in an armed forces area so his tenants are invariably military personnel. I think financially, if you can get a better return on the proceeds of sale than if you kept the house, that's fine, but bear in mind any rent on a mortgage free property will give you an additional income alongside any rise in value that may occur over the next 5 years while you are overseas. Presumably you've asked your daughter what they would prefer.1
-
You could let it out as a Short Term / Holiday Let via a specialist agency. So long as you get enough visits Council Tax can go away because you move it onto Business Rates and claim small business relief. Energy, Water, Insurance are still a cost but should be well covered by rental income. You can still book yourselves for owner visits and you can keep your furniture and non-personal stuff. So long as you choose a decent agency it should be looked after OK.splinters said:One last question before we start the process of selling the house. Are there any practical options to keep the house at minimal cost to us while overseas? We like the flexibility of still having a property (visits home, fallback in case the jobs don't work out here etc.) but no one wants to be paying council tax, utilities etc. and we would need to have the property checked for leaks, damage etc. but our children live quite near to us.
1












Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards