We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Lloyds adding 2 months extra to my 2 year fix duration - losing out!!!
Cash_Cow
Posts: 131 Forumite



Took a 2 year fix with Lloyds that started March 1st 2024. Obviously I want to re arrange this asap to get the rate down from 4.94. They say I can do this from MAY 1st. They have added 2 months to the fix's duration. This is v disadvantageous to me especially as I want extra drawdown on a new product asap. How can they make it 2 years and 2 months when the product sold was a 2 year fix? 
0
Comments
-
What was the end date stated in the contract you signed in 2024?1
-
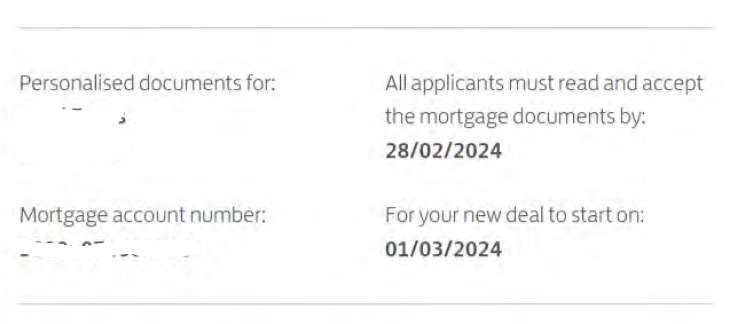
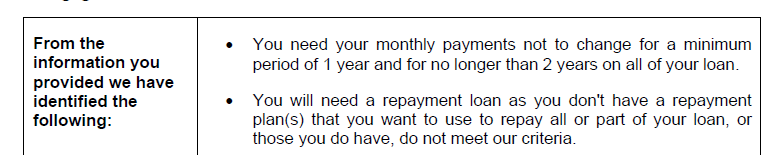
This was one document I signed agreeing to the 2 year fix but yes they seem to have sneaked in an extra 2 months term on other documents. Why have they sneaked in an extra 2 months on a product sold as a 2 year fix (and see the 'no longer than 2 years' wording below too) Yes they got me and its now an issue... :'(
0 -
Have a look at the original illustration. Sections 3 and 6 and possibly 8 will confirm when your deal finishes.
If this is different to what you are being told, you are right to take it further. If not, then its on you for not querying it at the time.
Its not uncommon for larger lenders to have fixed end dates rather than a dead on 24/36/60 months for a variety of reasons.
What date does the illustration say you are tied in until?I am a Mortgage AdviserYou should note that this site doesn't check my status as a mortgage adviser, so you need to take my word for it. This signature is here as I follow MSE's Mortgage Adviser Code of Conduct. Any posts on here are for information and discussion purposes only and shouldn't be seen as financial advice.1 -
Thanks. The illustration states:
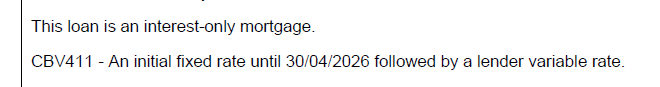
Actually I do think I queried this hard at the time but was desperate to get off the variable rate default.. It seems inconsistent and misleading and I could really do with it ending 2 months earlier as was fair to anticipate in my view. Reckon I can get them to honour a 2 year term? Worth a shot?0 -
They raise £x millions of pounds. Whether that be money they buy in or through savings accounts. They have to pay that interest for the duration. So letting you out 2 months early means they are not getting interest from you, but they are paying it someone else.
Then you have the fact that you are 1 customer of thousands. They cant alter their processes just for you. And if they did, they would have to do it for everyone. As good as regulation can be, there is something that came out a few years back which basically means everyone has to be treated the same. So regulation is not helping here either.
But if we just take all the complexity away from it and look at it on a pragmatic level. You queried it when you were not tied in to them and could have gone anywhere (theoretically). They told you nothing can be done. Why would they do it now you are tied in? - That is not the reason, the 2 paragraphs above are more accurate. But I just thinking you can argue and ask all you like, your not going to get anywhere because their systems do not allow for it. Even if rolls were reversed and rates had rocketed, they would still not let you leave early to get you on a higher rate.I am a Mortgage AdviserYou should note that this site doesn't check my status as a mortgage adviser, so you need to take my word for it. This signature is here as I follow MSE's Mortgage Adviser Code of Conduct. Any posts on here are for information and discussion purposes only and shouldn't be seen as financial advice.2 -
To be fair they never explained it on any level but its on record that it caught me out and I wasn't happy about it and didn't want them to add 2 months on to my term - and now it actually bites where I thought it might not be an issue. As you suggest I'll be on a 99.99% loser but even a loser's gotta try! Thanks for the input though. Appreciated.0
-
Best of luck.
If you get them to back down make sure you come and rub it in my face! But I think 0.01% is overstating your odds. Good luck! You dont get if you dont ask and all that.I am a Mortgage AdviserYou should note that this site doesn't check my status as a mortgage adviser, so you need to take my word for it. This signature is here as I follow MSE's Mortgage Adviser Code of Conduct. Any posts on here are for information and discussion purposes only and shouldn't be seen as financial advice.1 -
They haven't added 2 months to your term, you just didn't understand what you were signing up for. If interest rates went up and they had tried to put you on a higher rate 2 months before the expiry date of your contractual end date do you think that would be acceptable?Cash_Cow said:To be fair they never explained it on any level but its on record that it caught me out and I wasn't happy about it and didn't want them to add 2 months on to my term - and now it actually bites where I thought it might not be an issue. As you suggest I'll be on a 99.99% loser but even a loser's gotta try! Thanks for the input though. Appreciated.0 -
It's perfectly normal to have a fixed end date that isn't exactly 2 years from the start date, you'll find quite a few savings accounts that that have a fixed date to end regardless of the start date.
I'm afraid you can't blame Lloyds for you not reading the T&Cs and it certainly looks from what you posted above that they told you the end date. If interest rates were going up you'd be very happy that your fix was 2 months longer than you thought. At lest the B of E have indicated they won't be going down again any time soon.1 -
Lloyds Banking Group run all fixed rates to set dates and not as 24 or 60 months contracts - a common Practice with the majority of Lenders. This helps them plan their business strategy as they can calculate how much debt will be refinanced in the first four months of 2026.
If you ask them, and they run the same process as Halifax, they will let you secure a new rate in February to start 1st March without penalty.I am a Mortgage Broker
You should note that this site doesn't check my status as a Mortgage Broker, so you need to take my word for it. This signature is here as I follow MSE's Mortgage Adviser Code of Conduct. Any posts on here are for information and discussion purposes only and shouldn't be seen as financial advice.0








Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.6K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards