Ready, steady… save!
You don’t need a chart to join in. Here are 2 ways to record your savings:
1. Cross it off
Pop a chart into your first post. Saved an amount? Cross it out! Read more »
£0.01 £0.02 £0.03
2. Write it down
Skip the chart and add updates to your first post. Read more »
“Another +£3 saved today. Go me!”
Use +£ before each new saving so it counts towards your total.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Claiming Pension Contribution refund 2024/25
Comments
-
Which would be wrong for the type of contribution your daughter has apparently made.tetrarch said:Finally some movement from the HMRC, but no resolultion
HMRC have extended my daughter's 20% taxable band by the post-tax contribution amount
PLEASE REMEMBER THAT THIS HAS COME ABOUT AS A RESULT OF A COMPANY TAKEOVER
Exact numbers - I've ignored some savings and small benefit in kind values
Gross Income £149,985
Employer Pension Contribution £4,847.26
Employee Pension Contribution £19,388.80
Employee Payment out of net income to Smart Pension £35,750
Summary:
Total Income £149,985
Total Pension Contribution £59,986.06 (maximised under £60K limit)
Taxable Income
By my maths that makes total Income Tax Liability: £94,846.20
12,570 @ 0% = 0.00
37,700 @ 20% = 7,540.00
44,576.20 @ 40% = 17,830.48
Total Tax = 25,370.48
Regards
Tet
You seem to be referring to some figures that simply aren't relevant to any of this.
What does her P60 show her taxable was?0 -
Attached are pics of the P45 (no P60 as change of company)
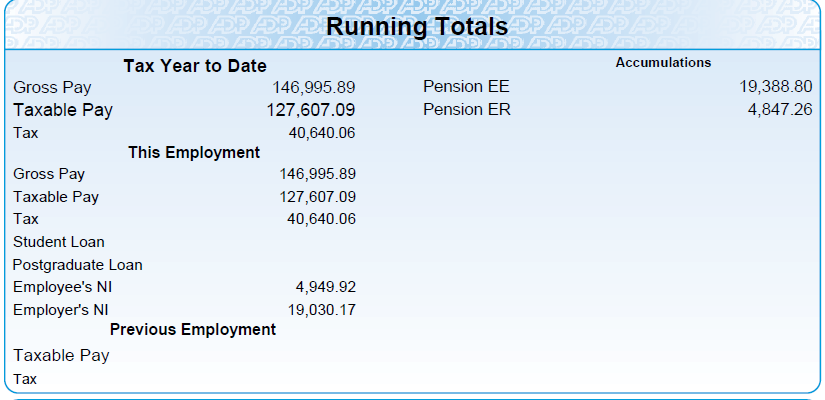
Using the above I can replicate the new HMRC numbers exactly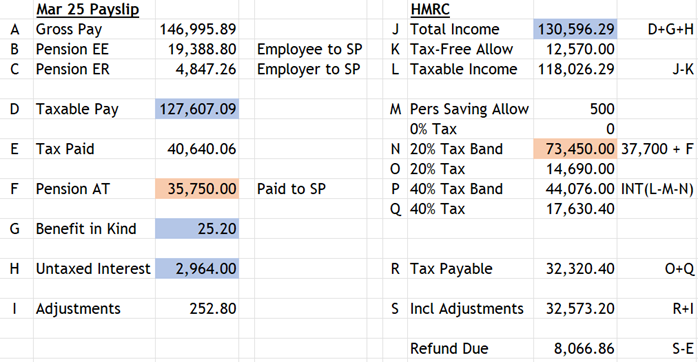
These are my numbers: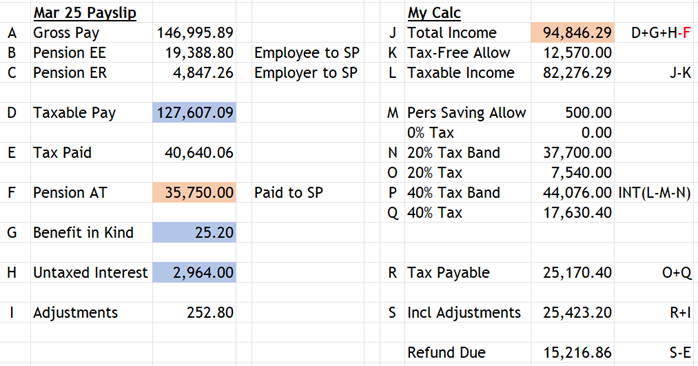
Regards
Tet0 -
HMRC have clearly treated the pension contribution as being made using the relief at source method, with the £35,750 being treated as the gross amount not the net amount.tetrarch said:Attached are pics of the P45 (no P60 as change of company)
Using the above I can replicate the new HMRC numbers exactly
These are my numbers:
Regards
Tet
From what you have posted she isn't entitled to an increased basic rate band but the pension contribution would reduce the income that falls to be taxed at 20/40%.
I'm not sure why you are persisting with including utterly irrelevant details, which can only serve to confuse HMRC.
What does the adjustment of £252.80 relate to? Is it underpaid tax from a prior year?0 -
HMRC have clearly treated the pension contribution as being made using the relief at source method, with the £35,750 being treated as the gross amount not the net amount.
From what you have posted she isn't entitled to an increased basic rate band but the pension contribution would reduce the income that falls to be taxed at 20/40%.
I'm not sure why you are persisting with including utterly irrelevant details, which can only serve to confuse HMRC.
What does the adjustment of £252.80 relate to? Is it underpaid tax from a prior year?
I was providing details so as to have you guys check my maths and understanding. Your emboldened comments above are exactly the right basis for a conversation with the HMRC
The adjustment is from previous year
As it stands they've "offered" £8k when my daughter is entitled to £15.2K, It's is probably best to query and get it corrected at this stage rather than formally claim the £8K and then get it re-corrected
Thanks for the assist
Regards
Tet0 -
There shouldn't be a problem if she claims the £8k. All that that will mean is when the correct calculation is issued it will include an extra line to reflect the fact that £8k has already been repaid.tetrarch said:HMRC have clearly treated the pension contribution as being made using the relief at source method, with the £35,750 being treated as the gross amount not the net amount.
From what you have posted she isn't entitled to an increased basic rate band but the pension contribution would reduce the income that falls to be taxed at 20/40%.
I'm not sure why you are persisting with including utterly irrelevant details, which can only serve to confuse HMRC.
What does the adjustment of £252.80 relate to? Is it underpaid tax from a prior year?
I was providing details so as to have you guys check my maths and understanding. Your emboldened comments above are exactly the right basis for a conversation with the HMRC
The adjustment is from previous year
As it stands they've "offered" £8k when my daughter is entitled to £15.2K, It's is probably best to query and get it corrected at this stage rather than formally claim the £8K and then get it re-corrected
Thanks for the assist
Regards
Tet0 -
Update:
Obviously my daughter was "important to them" for her call to be eventually answered
They have agreed that she is able to reclaim 40%
They agree that the advice in the "Do I need to complete a self-assesment" workflow contradicts the information on the "personal pension taxation guidance" blurb
They say that she must now complete a self-assessment form and that she won't be penalised for doing so
She will claim the £8,000 offered and she's doing her first ever Self Assessment Tax Return this weekend
Thanks for all the help
Regards
Tet0 -
I don't know why you would think she could be penalised but if she goes down that route it's key that she remembers to include the refund of £8k on her Self Assessment return.tetrarch said:Update:
Obviously my daughter was "important to them" for her call to be eventually answered
They have agreed that she is able to reclaim 40%
They agree that the advice in the "Do I need to complete a self-assesment" workflow contradicts the information on the "personal pension taxation guidance" blurb
They say that she must now complete a self-assessment form and that she won't be penalised for doing so
She will claim the £8,000 offered and she's doing her first ever Self Assessment Tax Return this weekend
Thanks for all the help
Regards
Tet
Easy pickings for HMRC investigators if she omits that and gets the £8k twice.0 -
The saga continues.
My daughter's application for self-assessment has been rejected as she is "not eligible" as her situation does "not satisfy the criteria for self-assessment"
A long phone call to the HMRC mae no progress. The advisor on the phone stated that filling in a self-assessment would not elicit a tax refund.
They also were expressed doubts that any registered pension provider would NOT reclaim basic rate tax, even querying whether or not Smart Pension were a registerd provider
The solution offered was to reopen my daughter's existing complaint. The inference being that the (already provided) proof that Smart Pension did NOT claim basic rate tax be reinvested by a specialist
Regards
Tet
0





Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.9K Banking & Borrowing
- 255K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.4K Work, Benefits & Business
- 606.1K Mortgages, Homes & Bills
- 179.1K Life & Family
- 264K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards