We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Lifesight Pension - any good?
Comments
-
That seems unlikely because IFAs can get figures in the 0.2x%-0.3x% ballpark and with an index tracker, you'd expect that to be better.
Are you sure it was an IFA that you saw, or was it an FA? That said, if the value is not very much, then it's a lot of faff for the IFA to do anything, and it's easier for them to say go with the workplace pension.
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.0 -
I've got a company scheme administered by WTW and they're pointing me towards WTW Lifesight for drawdown.
At the moment I'm expecting to use them as the charges do seem very reasonable. For most funds the 'annual fee' is around 0.1% per year, so just £100 per £100,000 invested, which covers all funds management charges and other admin. I'm pretty sure most other drawdown providers charge more, but I can't find a comparison right now so would be pleased if someone could point me towards one.
The funds on offer are mostly unique indices designed by WTW and executed by LGIM. All of the funds need a unit-linked ‘wrapper,’ hence they are badged by L&G as the legal owner and operated/priced by their unit-linked pension platform. There are a couple of HSBC funds in the mix due to their unique approach to Shariah principles.
Fund performance seems on about par with other providers, but I'm still doing my research on that.
As far as my experience with WTW over the last 12 years, they seem to run the administration on an absolute shoestring and emailing them is basically pointless as you've forgotten exactly what you needed by the time they reply. Phoning them is better, but not everyone who answers the phone has all the information you need and callbacks don't seem to happen in my experience.
0 -
Typical charges for a mainstream pension provider, are between 0.2% and 1%. There maybe some extra charges for Drawdown, especially for the ones with lower charges.
Normally there is a charge for the pension provider and a charge for the investment fund chosen. Sometimes there is just one charge. Sometimes there is a discount as the size of the pot gets bigger.
0.1% all in seems cheap, but maybe it is the reason for their poor reputation for customer service. I have two mainstream pension pots and any e mails are answered in 12 to 48 hours.
0 -
I have just commenced drawdown via LifeSight spending. Everything is done online or via the app. You can set one-off or regular withdrawals and specify end dates or increases as needed:
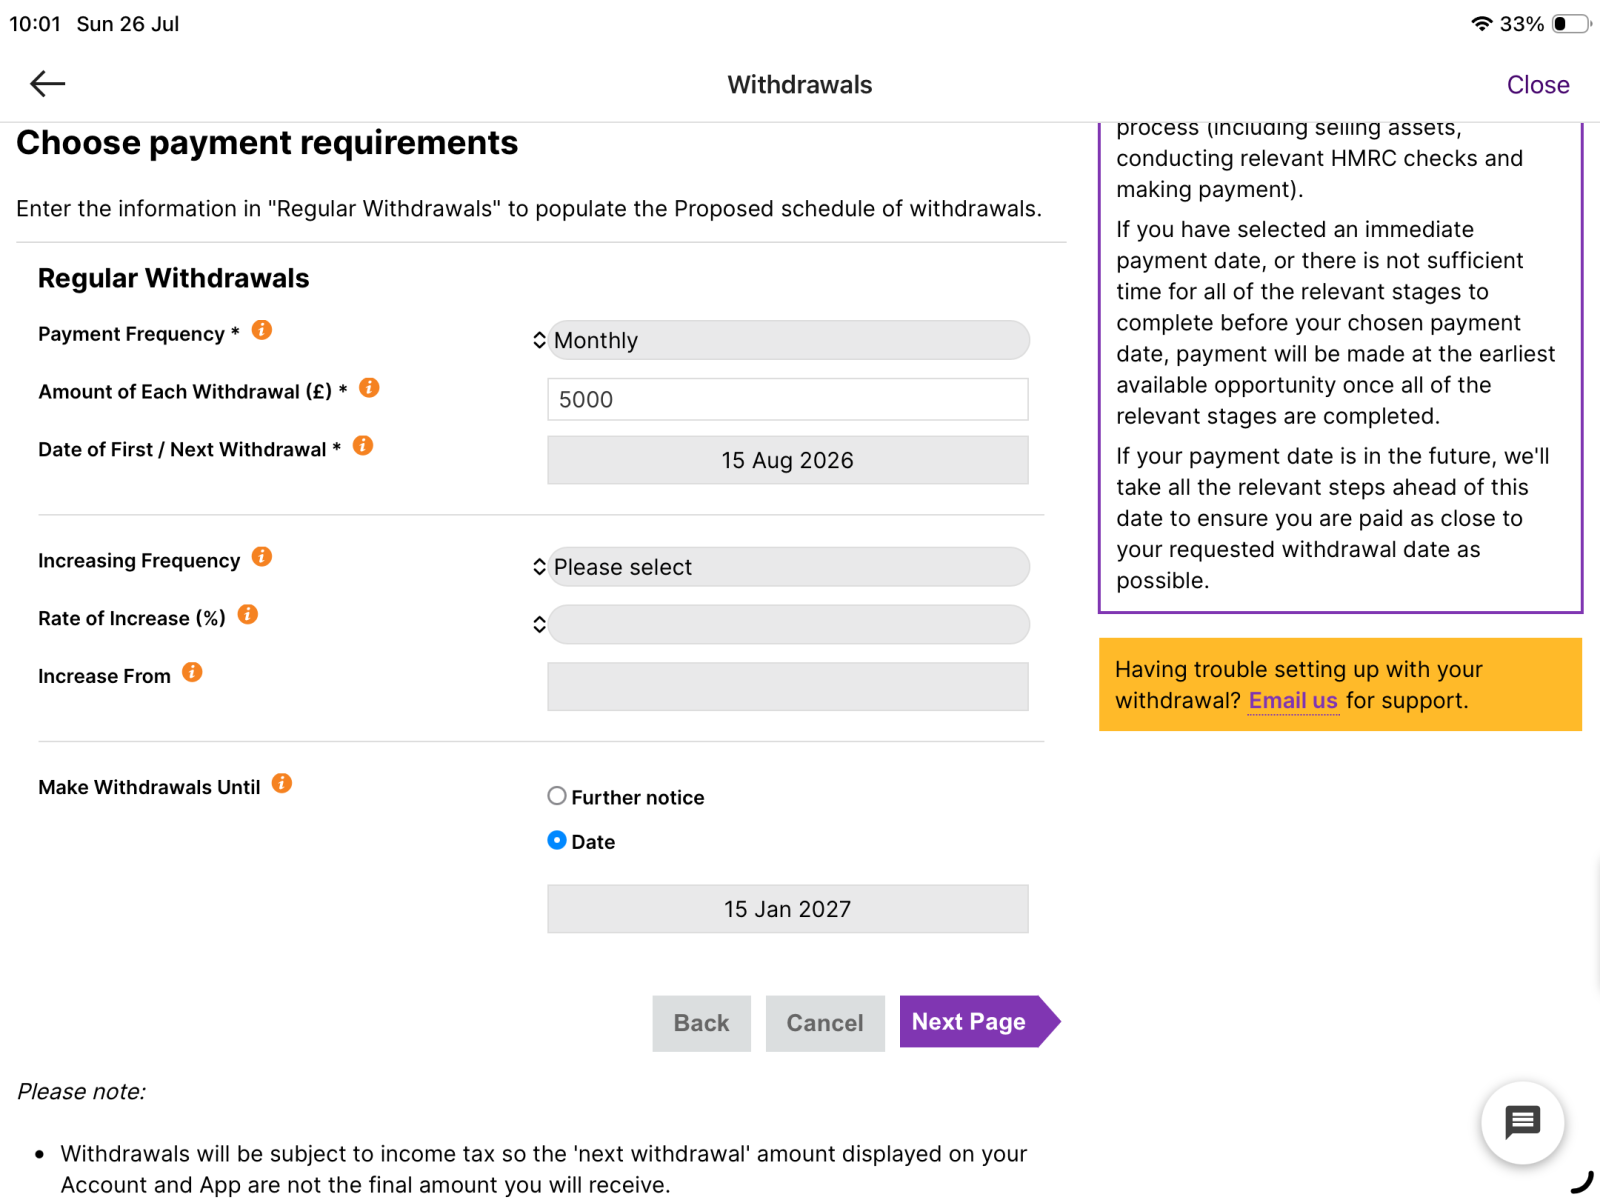
, no hassles, 1st instalment arrived when expected.
I was a bit unsure beforehand because there is a bit of a lack of info available until you actually start but can honestly say it's all very straightforward and easy to use. Far easier than Mrs GenX dealing with her Wealthify robosipp. As you stated, very low charges as well.
2 -
I've got a company scheme administered by WTW and they're pointing me towards WTW Lifesight for drawdown.
They would do. They are not going to point you to independent options.
At the moment I'm expecting to use them as the charges do seem very reasonable.
The guide you linked indicates a 0.48% member fee with fund charges on in house funds around 0.1x% on top of the member fee.
£35 chaps fee (most platforms dont charge a Chaps fee nowadays).
pension sharing orders are excruciatingly expensive compared to retail schemes.
So, if you are paying those charges, then its not as reasonable as you think.
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.1 -
Pretty sure that 0.48% was "as an example"…..
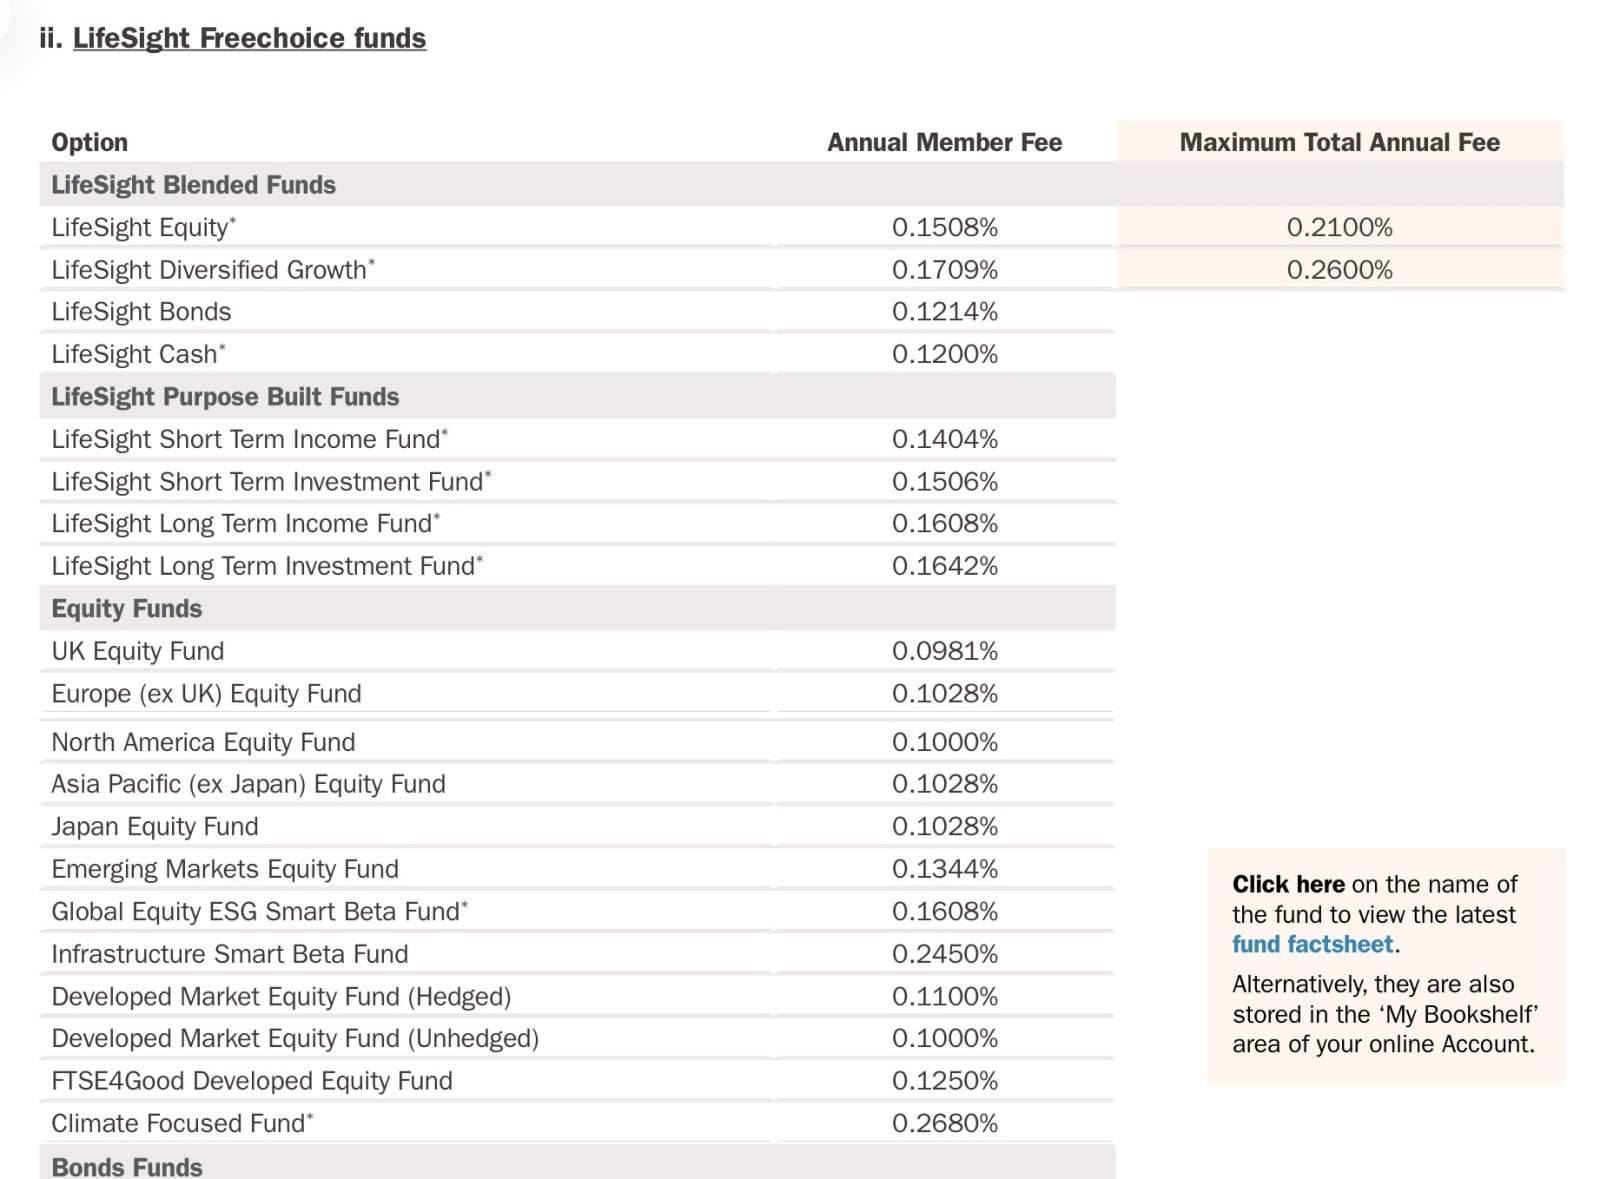
It depends which funds you invest in. Heres the list of annual charges for their Freechoice (managed) funds :
EDIT: Also not sure why you would need CHAPS rather than just nominate your current account to receive withdrawals
0 -
The annual fee covers all admin, communication and fund management fees. There are no charges to pay out to UK bank accounts.
0 -
Thanks @GenX0212
I'm not quite sure why they used 0.48% in the example because I can't see any funds that charge more than 0.39%.
There are some that incur 'additional variable expenses' which aren't detailed, so I'd steer clear of those personally!
But for bog standard equity funds the total annual fee is 0.1% or less, and their performance seems good. Compare the US equity fund which has done 17% annually since launch to vanguard S&P 500 ucits etf which has done just under 15% annually.
So I'm struggling to find a reason not to give them my money, especially after your thumbs up on the actual experience
0 -
This screen I assume means you took your 25% in its entirety as they are stating all withdrawals are subject to income tax.
I can't establish from the literature if you can to UFPLS and FAD - i.e. take a certain amount of tax-free cash (to pay off a mortgage, for example), crystallising the remainder to be drawn at a later date and all subject to income tax AND do UFPLS on the remaining uncrystallised funds.
Does the website/app have different pots for crystallised and uncrystallised funds?
0 -
No. The default is UFPLS so 25% of each withdrawal tax free. It's another thing their documentation isnt great on but I had previously raised a query to confirm as UFPLS is what I wanted.
They only crystalise when each withdrawal is due so for example they crystalised £5k in August and they will do the same next month. The app/website shows your remaining uncrystalised pot balance less any withdrawals which are 'in process' for the current month, for my first withdrawal there was a gap of about 2 weeks between them selling assets and actually making payment, this doesnt show in your balance but there is a seperate view showing upcoming payments.
I presume they will issue an annual statement confirming how much LSA you have used/remaining.
1








Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.5K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards