We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
LGPS Prudential AVC Funds





Finding this site and the help/guidance/tips I have received has made it easier for me to navigate through the Pensions Minefield!
I have just over 2 years till I take retirement at 60, this could be just over 1 year as there is talk of redundancies in March 26.
I have SSAVC's which has been invested in the Prudential S3 UK Equity Pen for the last 8 years which is higher risk. I started investing £100 per month and gradually increased it to £1300 per month.
As I only have 1-2 years left, I think its time to move my investments to a 'safer' fund as I want to take the amount as a TFLS.
For context I have invested £67800 and the current value is £80k.I am happy with that and would like to 'lock in' any gains I have made.
Prudential have giving me 17 funds I could invest in - see below
| BlackRock Aquila UK Equty Index | ||||
| Prudential Dynamic Global Equity Passive | ||||
| Prudential Dynamic Growth I | ||||
| Prudential Dynamic Growth II | ||||
| Prudential Dynamic Growth IV | ||||
| Prudential Dynamic Growth V | ||||
| Prudential Positive Impact | ||||
| Prudential S3 All Stocks Corporate Bond Pen | ||||
| Prudential S3 Cash Pen | ||||
| Prudential S3 Discretionary Pen | ||||
| Prudential S3 Fixed Interest Pen | ||||
| Prudential S3 Index-Linked Pen | ||||
| Prudential S3 International Equity Pen | ||||
| Prudential S3 Long-Term Bond Pen | ||||
| Prudential S3 Long-Term Gilt Passive Pen | ||||
| Prudential S3 North American Equity Index Pen | ||||
| Prudential S3 UK Equity Index Pen | ||||
Has anyone got any tips on good 'safe' fund options. What do I need to look for? Etc
Will I lose money if I invest it all in Cash? Do I mix and match in different funds? Or is it best to seek advice from an IFA?
I would appreciate any feedback.
Maria
Comments
-
If it were me then I'd switch everything into the S3 cash fund. This is a money market fund and you'd expect to gain ~ 3-4% per year over the next two years after charges. It's the lowest risk fund by far.
All the other funds have the potential to fall and with only 1-2 years before withdrawal, wouldn't have time to recover.0 -
As a guess I'd say that split will give you a return anywhere between £4k higher and £8k lower than a 100% cash fund.
That UK fund has averaged just under 6% a year over the last 10 years. In the last year it's returned just under 15%, so it's been an exceptional year.
My £4k figure assumes that the exceptional year is repeated over the next two years. My £8k figure assumes a ~50% drop as per the financial crisis from 2007-2009.1 -
Hi hope its ok to use this discussion to ask a follow-up question, seemed relevant to the above. A couple of years ago, as I approach retirement I switched my Pru AVC to the Cash S3 fund. I thought this was basically like a fairly low interest savings account but over the last few days I've been logging in to the Pru portal daily and notice that the amount in my AVC has been decreasing - only by small amounts per day but since Thursday its gone down about £8. I'm clearly not understanding how it works and sure there is a good reason for this but I'm not aware of what is is! Can someone help explain? TIA
0 -
Is there a fund sheet for the Cash S3 fund? I make LGPS AVC contributions (not with the Pru though) and there are fund sheets for each of the funds that are available to invest in. Does the Pru have something similar that you could read and double check it is similar to a low interest savings account.
I don't believe that your annual fees would be greater than the interest you would earn in the Cash S3 fund but that may possibly be an explanation but I think unlikely.
Might be worth doing the above and I also hope that somebody knows more than me re the Cash S3 fund and can answer your question.0 -
I'm clearly not understanding how it works and sure there is a good reason for this but I'm not aware of what is is!
Note that the OP didn't understand it either. They believed they would receive a return similar to a market-leading short-term money market fund (STMM), but this is not a STMM fund.
In addition to investing in interest‑paying deposits, it can also use short‑term UK government bonds. UK government bonds have cooled again, just as they did in late 2021–2023, when this fund last suffered losses. Last time it was because of the switch from quantitative easing to quantitative tightening, inflation and rising interest rates. This time, it is market sentiment about the current government's ability or willingness to address spending. This leads to lower demand from the markets, which pushes yields higher but unit prices lower.
It is a pretty dire fund and the type of one you would only want for a very, very short period, assuming you cannot transfer the pension to an alternative with better options.
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.1 -
Slightly harsh @dunstonh given that the fund has performed on par with Royal London short term money market fund over the last year and is only marginally behind over 3.
Why would anyone transfer to an alternative provider and give up the opportunity to take their entire holding tax free ?
0 -
I looked it up. 1 year is 1.7%
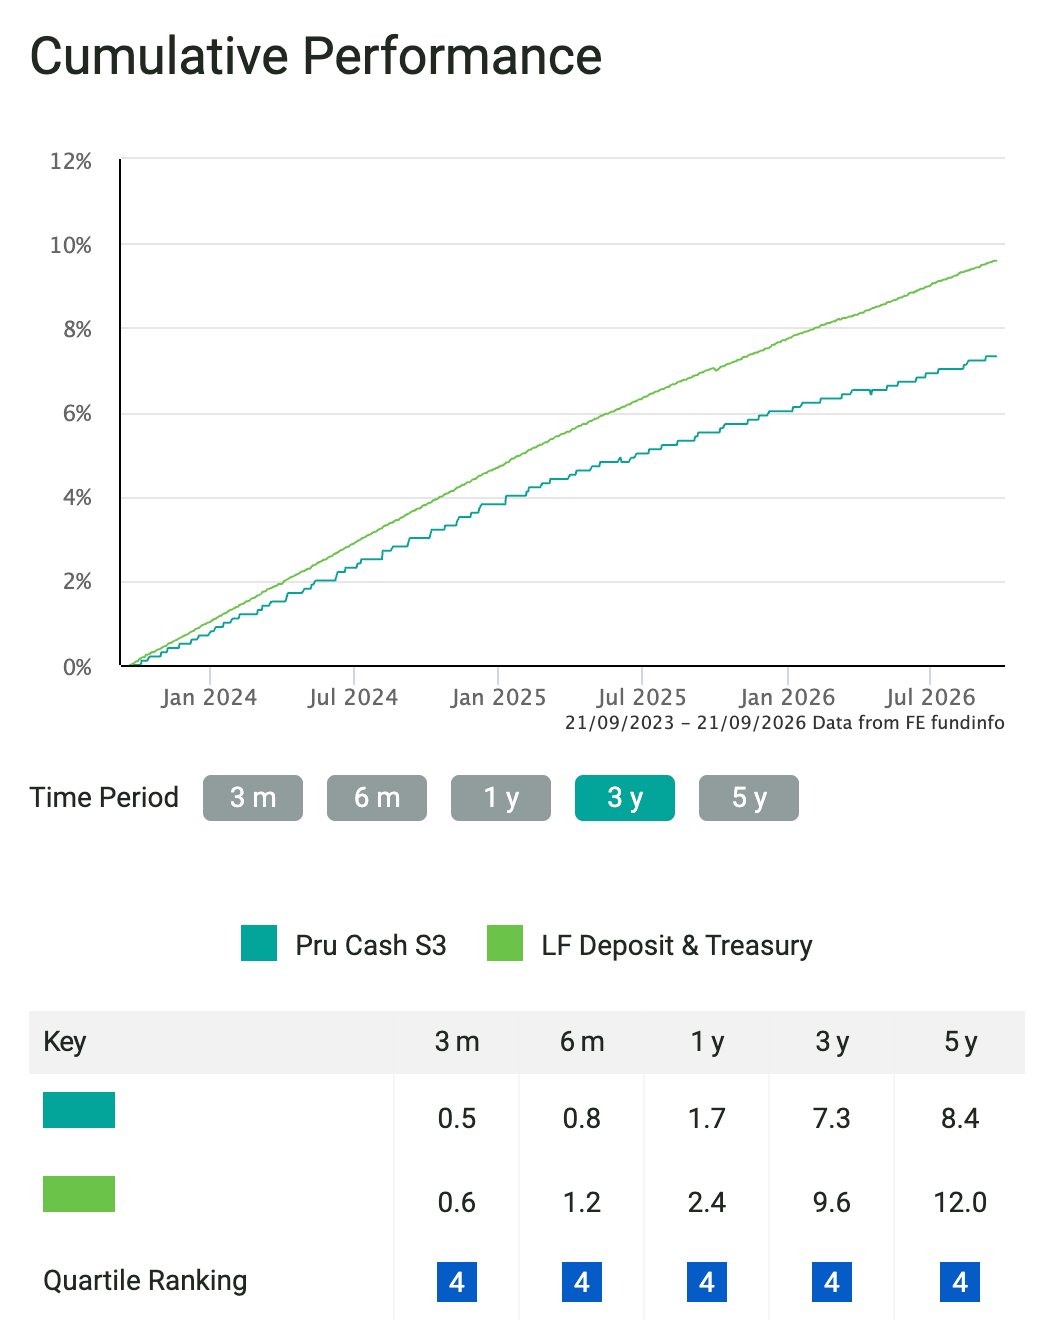
However, checking other links, there are multiple Pru Cash S3 funds with different ISINs. One of which is closer to RLSTMM in terms of performance. However, that one isn't running a short term loss.
Why would anyone transfer to an alternative provider and give up the opportunity to take their entire holding tax free ?
There are a small number of reasons why you would transfer but most wouldn't. That is why i worded it the way I did.
However, you frequently find public sector workers invest far too cautiously for long term money. So, you need to be careful that the tax tail isn’t wagging the dog.
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.2 -
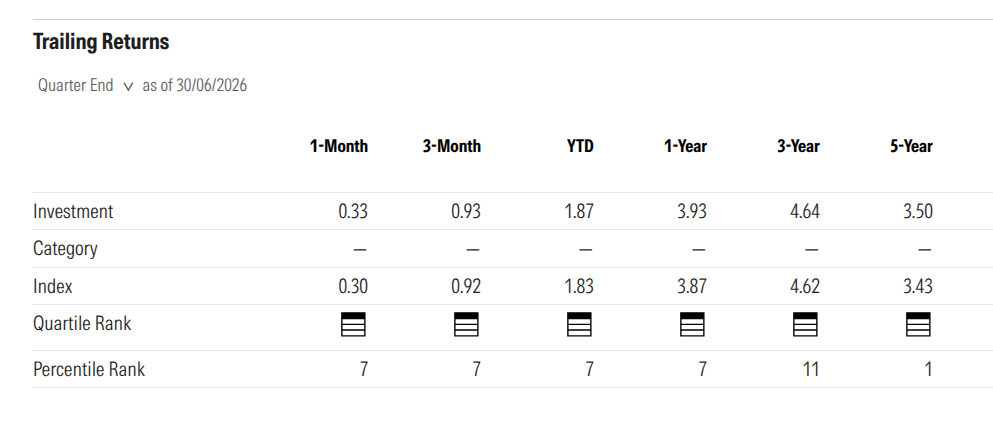
This is the s3 cash fund I can see on the lgps Pru AVC site, ISIN GB0031681108. As you say it shows no short term loss, so the £8 loss could be something else. Payments are usually added around 18th-20th of each month, although they're not likely to be showing yet. I've known the Pru to completely mess up the changes, so worth the OP checking the number of units held.
 0
-
Hi Maria, I also have an LGPS SCSS with the Pru. I started my AVC at 62 years of age because the tax break is very attractive, tax free in tax free out ( when taken with full pension ). Initially I stuck with their default fund but following the Liz Truss downturn I switched to 100% cash s3. I’m far too risk averse at 66 years so the modest growth coupled with my personal “ free “ £310 tax gift into the fund each month is very welcome.
0







Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.7K Mortgages, Homes & Bills
- 179K Life & Family
- 263.5K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards