We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
IHT mitigations (Inheritance Tax)
Comments
-
The problem is that you cannot predict when a 30% or worse crash will happen. ….also the danger that you lose out on equity growth if you derisk for a crash that does not happen……..
……..That’s exactly true. You can’t predict, but I think some things are so obvious that a market crash is coming, for example Covid. Or individual companies crash like Ratners. It’s more a protection lever.
The way I deal with this is to split my investments according to the timescale when I plan to use them……….
……..I think I am about the same. I have short term cash / liquidity. I think of it as say 4 boxes of money. The first box is for 1 – 10 years and has cash and lower risk funds. Box 2 is for 10 – 20 years out and is 100% equity. Similarly for box 3 and 4. As time moves forward box 2 starts to look like box 1 etc. Not all the boxes are the same size as box 4 has 30+ years growth potential. And spending profile / pension drawdown changes as well over time.
0 -
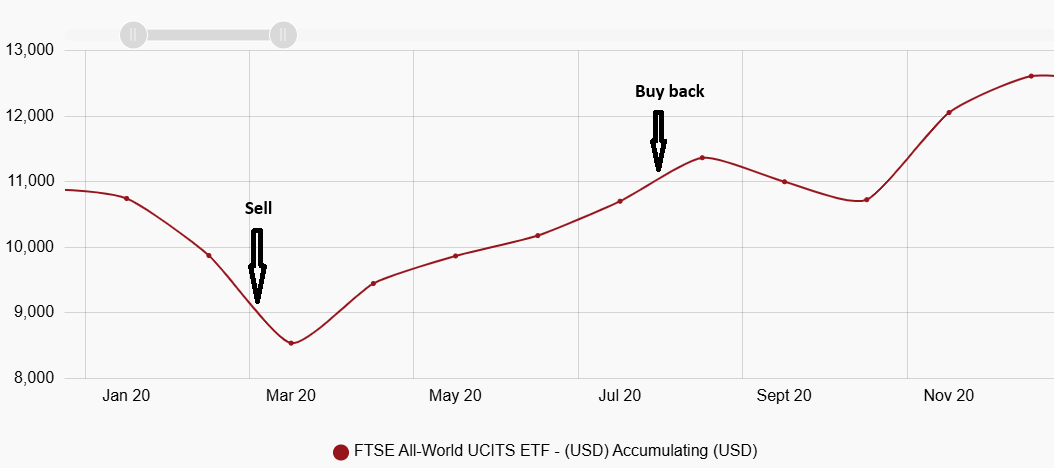
……..That’s exactly true. You can’t predict, but I think some things are so obvious that a market crash is coming, for example Covid.
I always think of Covid as a pretty good example of why it's dangerous to try to predict stock market crashes myself. In spite of a crash which quicky reversed, 2020 was a very good year for stock markets overall. By trying to get out as the Covid panic was setting in, and then not knowing when to buy back in as it looks like the world might not be ending after all, you risk missing out on a year of lovely growth, or worse doing something like this and losing a fortune.
 0
-
I am with the group believing pensions were given a massive tax break so they could have a good retirement so it’s only ‘fair’ they pay it back via IHT if its not used for that purpose. The ‘double taxation’ though is a bit of an unnecessary ‘kick in the nuts’. I am in the boat where i have a decent DB so have no real need for my DC other than spend/gift.
Ps - Am keeping 100k to one side to buy an AI robot for ‘care’ in old age - though how wise that is, i am not sure.
0 -
I am with the group believing pensions were given a massive tax break so they could have a good retirement so it’s only ‘fair’ they pay it back via IHT if its not used for that purpose. The ‘double taxation’ though is a bit of an unnecessary ‘kick in the nuts’.
Ordinarily money is subject to income tax when earned and inheritance tax when passed on.
Money paid into a pension however is free of income tax when earned - it's taxed on withdrawal instead. Subjecting the money to IHT on death then income tax on withdrawal isn't some vindictive kick in the teeth - it just means that the money is returning to broadly the tax position it would have been in had it not been paid into a pension in the first place.
I say "broadly" because there's still one tax advantage - the years (or decades) of tax free growth that is enjoyed within the pension don't get clawed back, so your beneficiariea will still be better off than they would have been had you not put the money into a pension. Unless you'd put it into an ISA instead I suppose, but it still acts as a nice little bonus on top of the standard ISA aloowancem
2 -
Spot on. People get sucked in by the illusion that the money in their pension is 'their money', forgetting that a big chunk of it has always been the government's money, in the form of deferred taxation. This is a necessary fiction to persuade people to save in the first place - the apparent 25% instant return (£80⇒£100) looks a lot more attractive than what's really just a 6.25% return for most people (£80⇒£85).
1







Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.3K Work, Benefits & Business
- 606K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards