We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
ILGs
Comments
-
Yes, it's telling you the capital loss, but in real terms. With ILG, you always need to think in real terms.
So with T27, if we pretend there is one year to maturity (for simplicity), you'll be getting:
- a loss of about 1.6% in capital, based on the clean price
- a gain of 1.25% from the coupon
- the gain or loss of the inflation linking
So if inflation is 3%, in nominal terms you'll get a little less than that, call it 2.8%.
The clean price and real yield make most sense when you think of them as the premium or discount you are paying for inflation protection.
0 -
Presumably you bought T27 to give you a guarantee that you would beat inflation for the period you were holding it?
If that is so - then the reason for holding it still exists.
ILGs tend towards the £100 clean price the closer they get to maturity, as most of the uncertainty about inflation is already known, with only 13 months to go.
The dirty price, which is what you buy and sell at, includes all the inflation to date. So the only thing that still has to be played for is inflation from now to maturity in November 2027.
For knowing what is best - the closest conventional gilt for maturity date to T27 is TR27
It is showing a yield to maturity of 4.582%
If you take the real yield for T27 away from the yield to maturity for TR 27 you get:-
4.582 - (-0.207) = 4.789.
So the market is pricing in inflation of 4.789% pa over the timescale until maturity. If you think inflation is going to be less than that - buy the conventional gilt. If you think it will be more, buy the Index-linked.
I must admit I'm surprised at that and the very short timescale may be skewing it. I'm usually looking at longer-dated ones, where the market assumption for inflation over the piece is more like 3.5% pa.
1 -
This site allows you to estimate the actual return (in £) you would get with various inflation assumptions.
1 -
The clean price is important because that enables you to compare one ILG with another. If 2 ILGs were offering identical terms but issued on different dates the two dirty prices would be different because the older one would have more accrued inflationary rises, but the clean prices would be the same.
When buying ILGs you can ignore the dirty price completely and just think in terms of buying £x worth. Whether this is 10 gilts with a dirty price of 100 or 5 gilts with a dirty price of £200 is irrelevent.
1 -
The reason I bought T27 (and other ILGs) was for inflation security and because my break-even calculation at the time of purchase was around 3.7% - I think!. I believed inflation would be higher than that over the term of holding the ILG - so I bought it. I am assuming the price I paid for T27 at that time was also less. Does this have an effect?
I too am surprised at the current 4.789% pricing - so does that mean I was correct in my assumption at the time of purchase?
0 -
As you can tell from my questions I am probably the last person to try to answer this.
I think the fact that the implied RPI growth figure is higher now than when you bought the ILG just means it was a better buy when you bought it than it is now (compared to the equivalent dated conventional gilt). The implied RPI growth figure is not the same as saying RPI will actually grow by this amount between now and maturity. It is how much it would have to grow by to match the conventional gilt.
I also believe that as the gilt gets closer to maturity some of these figures like implied RPI growth and real return get skewed because the RPI stops being measured three months before maturity. I don't know if that is affecting T27 yet.
1 -
If you buy £100 of T27 today, you will receive about:
£98.40 in Nov ‘27
inflation between now and then £3.50
coupon payments in Nov, Mar and Nov. The first coupon effectively goes mainly to the current owner (you pay extra when you buy the bond, then receive a coupon pmt almost straight away). So you end up with about two payments: 1.125% × 0.984 ÷ 2 (two pmts per year) × 2.2 (inflation since the bond was born). That’s £1 times 2 = £2
So, over the course of a year or so, you turn £100 into £104. Roughly the same as you would have got from TR27. Or a decent savings account.
3 -
Comparing ILG with similarly dated conventional gilts, here's the inflation rate I get in my spreadsheet
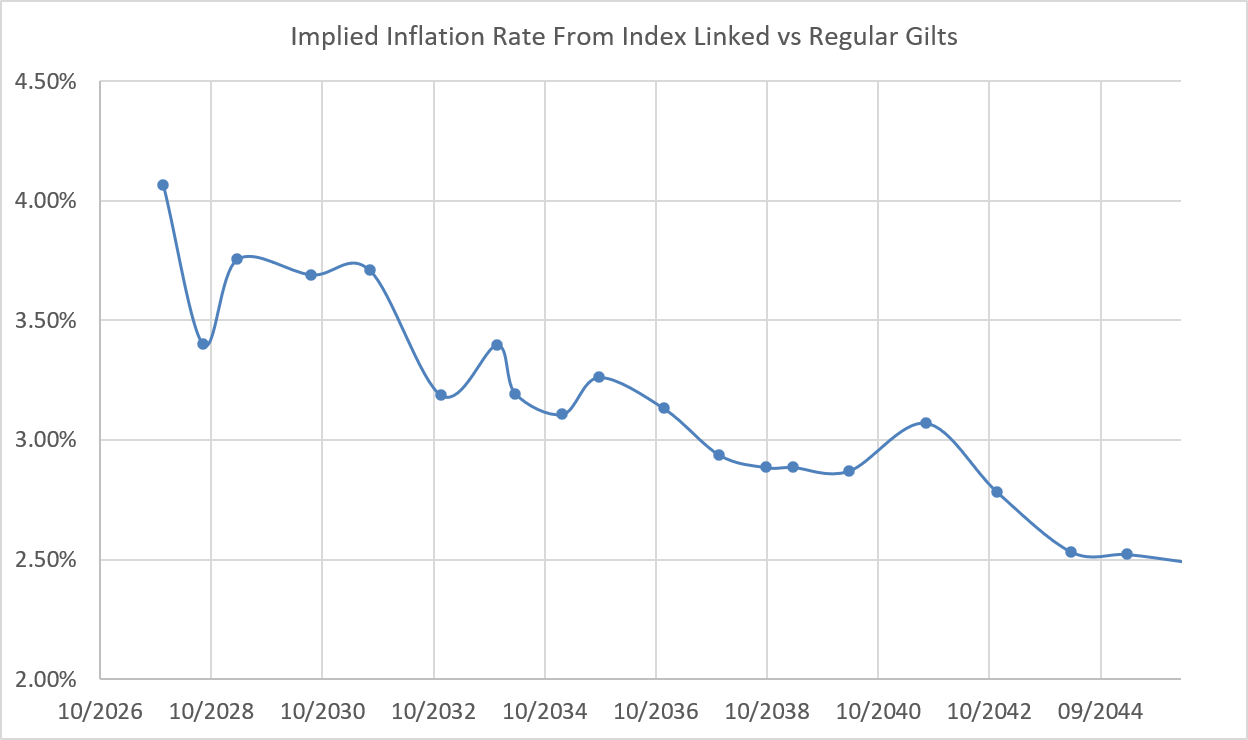
Arguably people who buy ILG's are paying extra for insurance or certainty, so the expected actual inflation rate is perhaps lower than the implied rate.
1 -
Not much to add.
You do have to be a bit careful when index linked gilts are nearing maturity in interpreting the real yield. The 2 month lag does have an affect depending on whether inflation for the past 2 months turns out to be more or less than inflation for the 2 months immediately before T27's maturity in November 2027.
And you do have to be careful with the seasonal aspect of inflation, although that's more relevant when say there is 6 months left to maturity and 6 month inflation can't be assumed to be half of annual inflation.
As it stands the clean price of T27 at yesterday's close was £101.68. But as you can see from the chart (the amounts to scale bit on the right) most of that excess over £100 is recouped via the remaining 2 full coupons in May and November, leaving a very small negative real return of -0.26%pa.
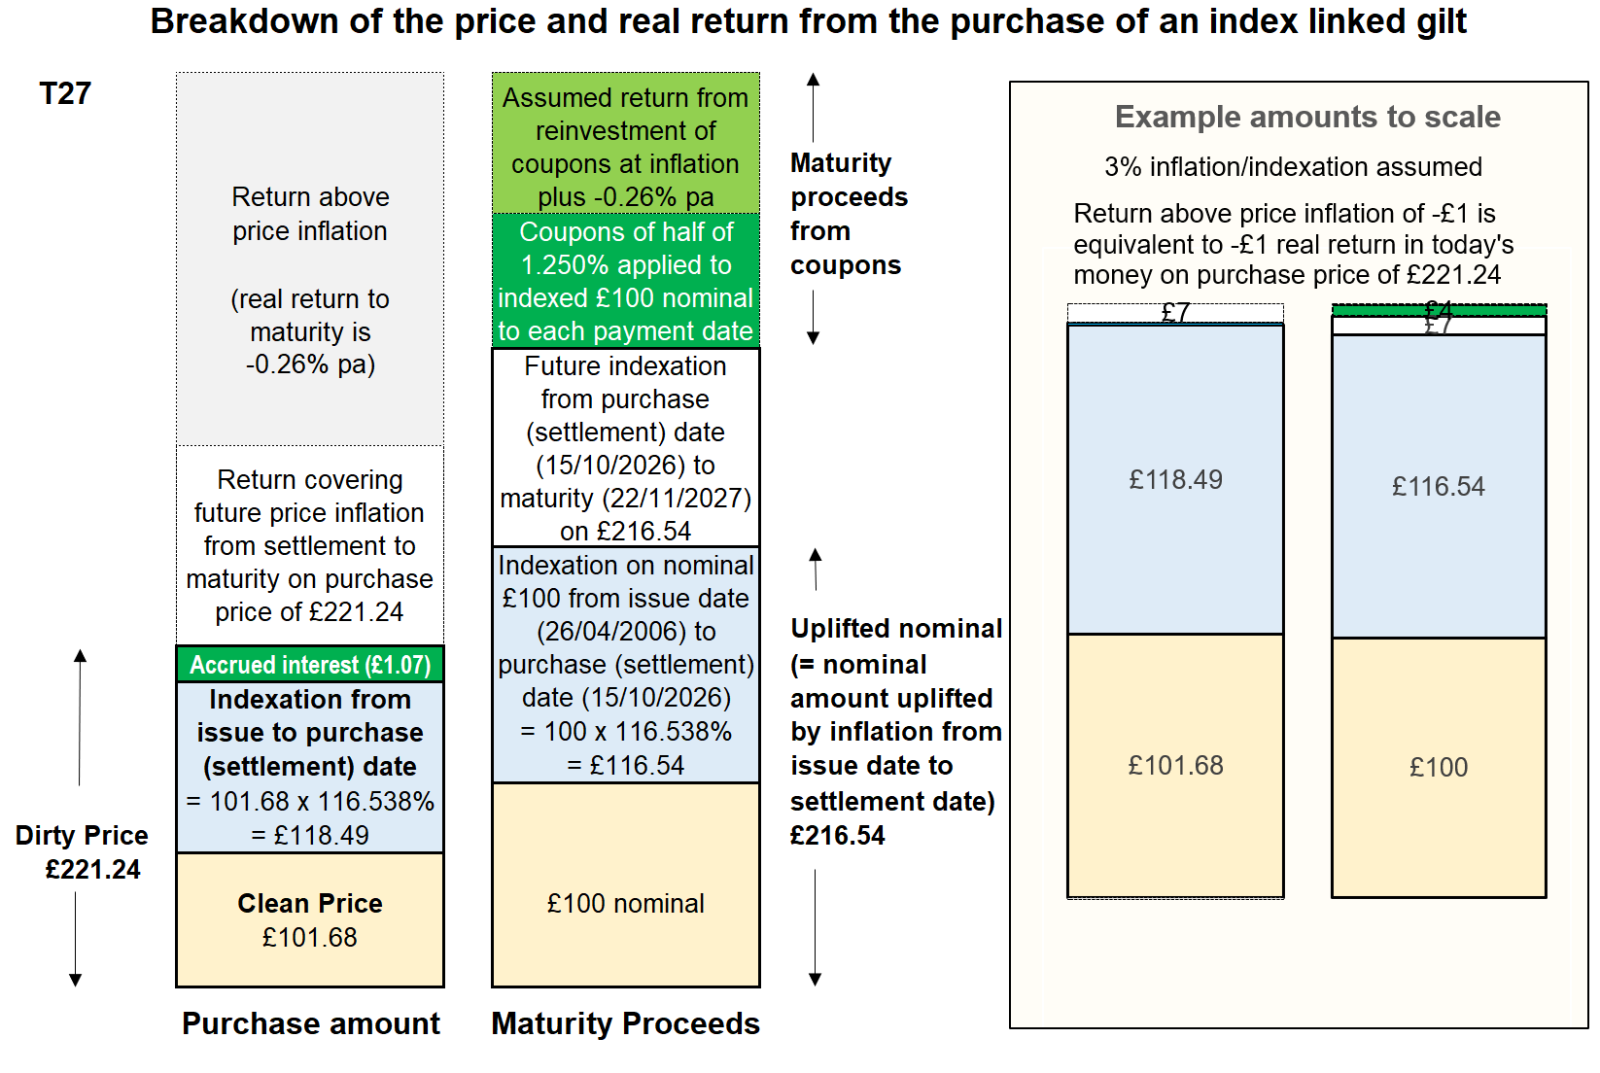
So roughly priced to almost cover RPI inflation remembering that RPI is currently 3.4%, CPI is 3.1% and CPIH is 3.3%. And inflation is rising. Usually the gap of RPI over CPI is a little higher.
I think it would be dangerous to try and draw too many conclusions about T27's current pricing and probably the pragmatic approach would be to assume that it is priced reasonably compared to conventional gilts of the same term.
I came, I saw, I melted3 -
All excellent stuff for my understanding, so many thanks. To answer my own original question, the most pragmatic course would seem to be to simply wait until T27 matures. As aforesaid, I have other ILGs maturing annually over the next 5 years, so perhaps one course of action would be to keep half an eye on RPI/CPI. If it drops markedly and if I believe likely to remain that way until they mature, then perhaps consider selling for the equivalent conventional gilt?
0












Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.3K Work, Benefits & Business
- 606K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards